
Envision Energy bringt die Onshore-Windkraftanlage Model T - EN175/8.0 auf den Markt und treibt damit die anlagenweite Optimierung sowie die Wertschöpfung über den gesamten Lebenszyklus für zukünftige Energiesysteme voran
Source: PR Newswire
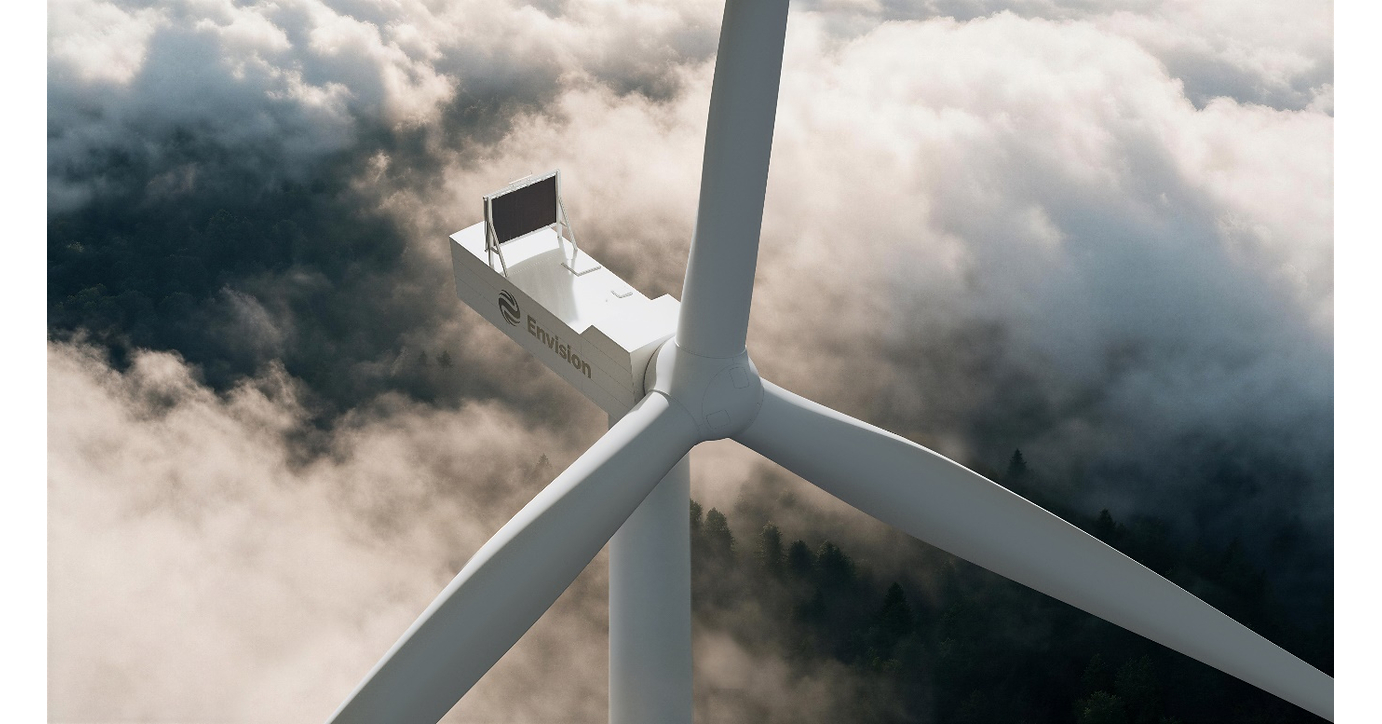
Envision Energy launched its Model T EN175/8.0 onshore wind turbine, an 8.0-MW unit with a 175-meter rotor designed for medium-wind and challenging sites. The company says the turbine can deliver 2–12% higher energy yield versus existing models, while Galileo AI-based autonomous controls aim to improve operating efficiency, reliability and lifecycle value. The turbine also incorporates grid-forming controls, low-noise blades targeting 107 dB(A), and optional cold-climate and anti-icing configurations.
Analysis
This is strategically more relevant to European turbine pricing than to Envision's near-term financials, which are not directly investable. A credible high-capacity Chinese onshore offering raises the risk that Vestas (VWS.CO), Nordex (NDX1.DE) and Siemens Energy's wind business (ENR.DE) face renewed bid pressure in lower-wind European projects, where larger rotors can lower balance-of-plant cost per MWh. The second-order consequence is potentially weaker service-margin protection: lower upfront equipment pricing often expands the installed base but shifts more lifecycle-performance and warranty risk back to OEMs.
The claimed energy-yield and autonomous-control benefits should not be capitalized until independently validated through project-level availability, wake-loss and degradation data. Grid-support functionality can improve project interconnection economics in constrained markets, but it does not eliminate the need for storage; rather, it increases the value of developers able to package turbines, BESS and energy-management software. This favors integrated developers and grid-equipment suppliers such as Prysmian (PRY.MI), Schneider Electric (SU.PA) and Hitachi Energy exposure within ABB (ABBN.SW) if it accelerates renewable build-outs.
Over the next 1-3 months, the material catalyst is whether European tenders show Envision winning orders at prices meaningfully below incumbent bids, particularly in Germany, Spain and Eastern Europe. Over 6-18 months, EU trade, cybersecurity, local-content and bank-financeability requirements remain the critical constraint: Chinese hardware can be technically competitive yet fail to convert into profitable European share without accepted warranty backing, local service capacity and lender approval. Consensus may overstate immediate disruption because developers generally prioritize delivery certainty and long-term service guarantees after recent turbine-quality failures.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No standalone directional trade on the launch: treat it as a competitive-intelligence alert until disclosed European order wins, turbine ASPs and third-party availability data establish commercial impact.
- Maintain a 3-6 month relative-value watch: short VWS.CO versus long ENR.DE only if Vestas cuts margin guidance or reports order-price deterioration while Siemens Energy's grid business continues to offset wind volatility. Thesis target is 10-15% relative downside; cover if Vestas backlog pricing or service-margin guidance improves.
- Prefer grid-capex exposure over pure-play turbine OEM exposure: accumulate ABBN.SW or SU.PA on renewable-sector weakness for a 6-18 month horizon, as higher variable-generation penetration requires grid automation, electrification and connection equipment regardless of turbine vendor share. Falsifier: sustained European permitting/build-out slowdown or material grid-capex deferrals.
- Monitor Nordex (NDX1.DE) tender disclosures most closely: its mid-market onshore concentration makes it more sensitive to aggressive Chinese pricing. A confirmed loss of share in core European markets or a 100bp-plus gross-margin guide reduction would justify a tactical short; absent that evidence, avoid forcing the trade.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Houthi attack on Mecca, Medina would cross ‘red line’, Pakistan PM tells UN
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying