
VSI® Expands Surgical Capabilities to Meet Growing Patient Demand, Welcomes Spine Surgeon Dr. Alexander Upfill-Brown
Source: PR Newswire
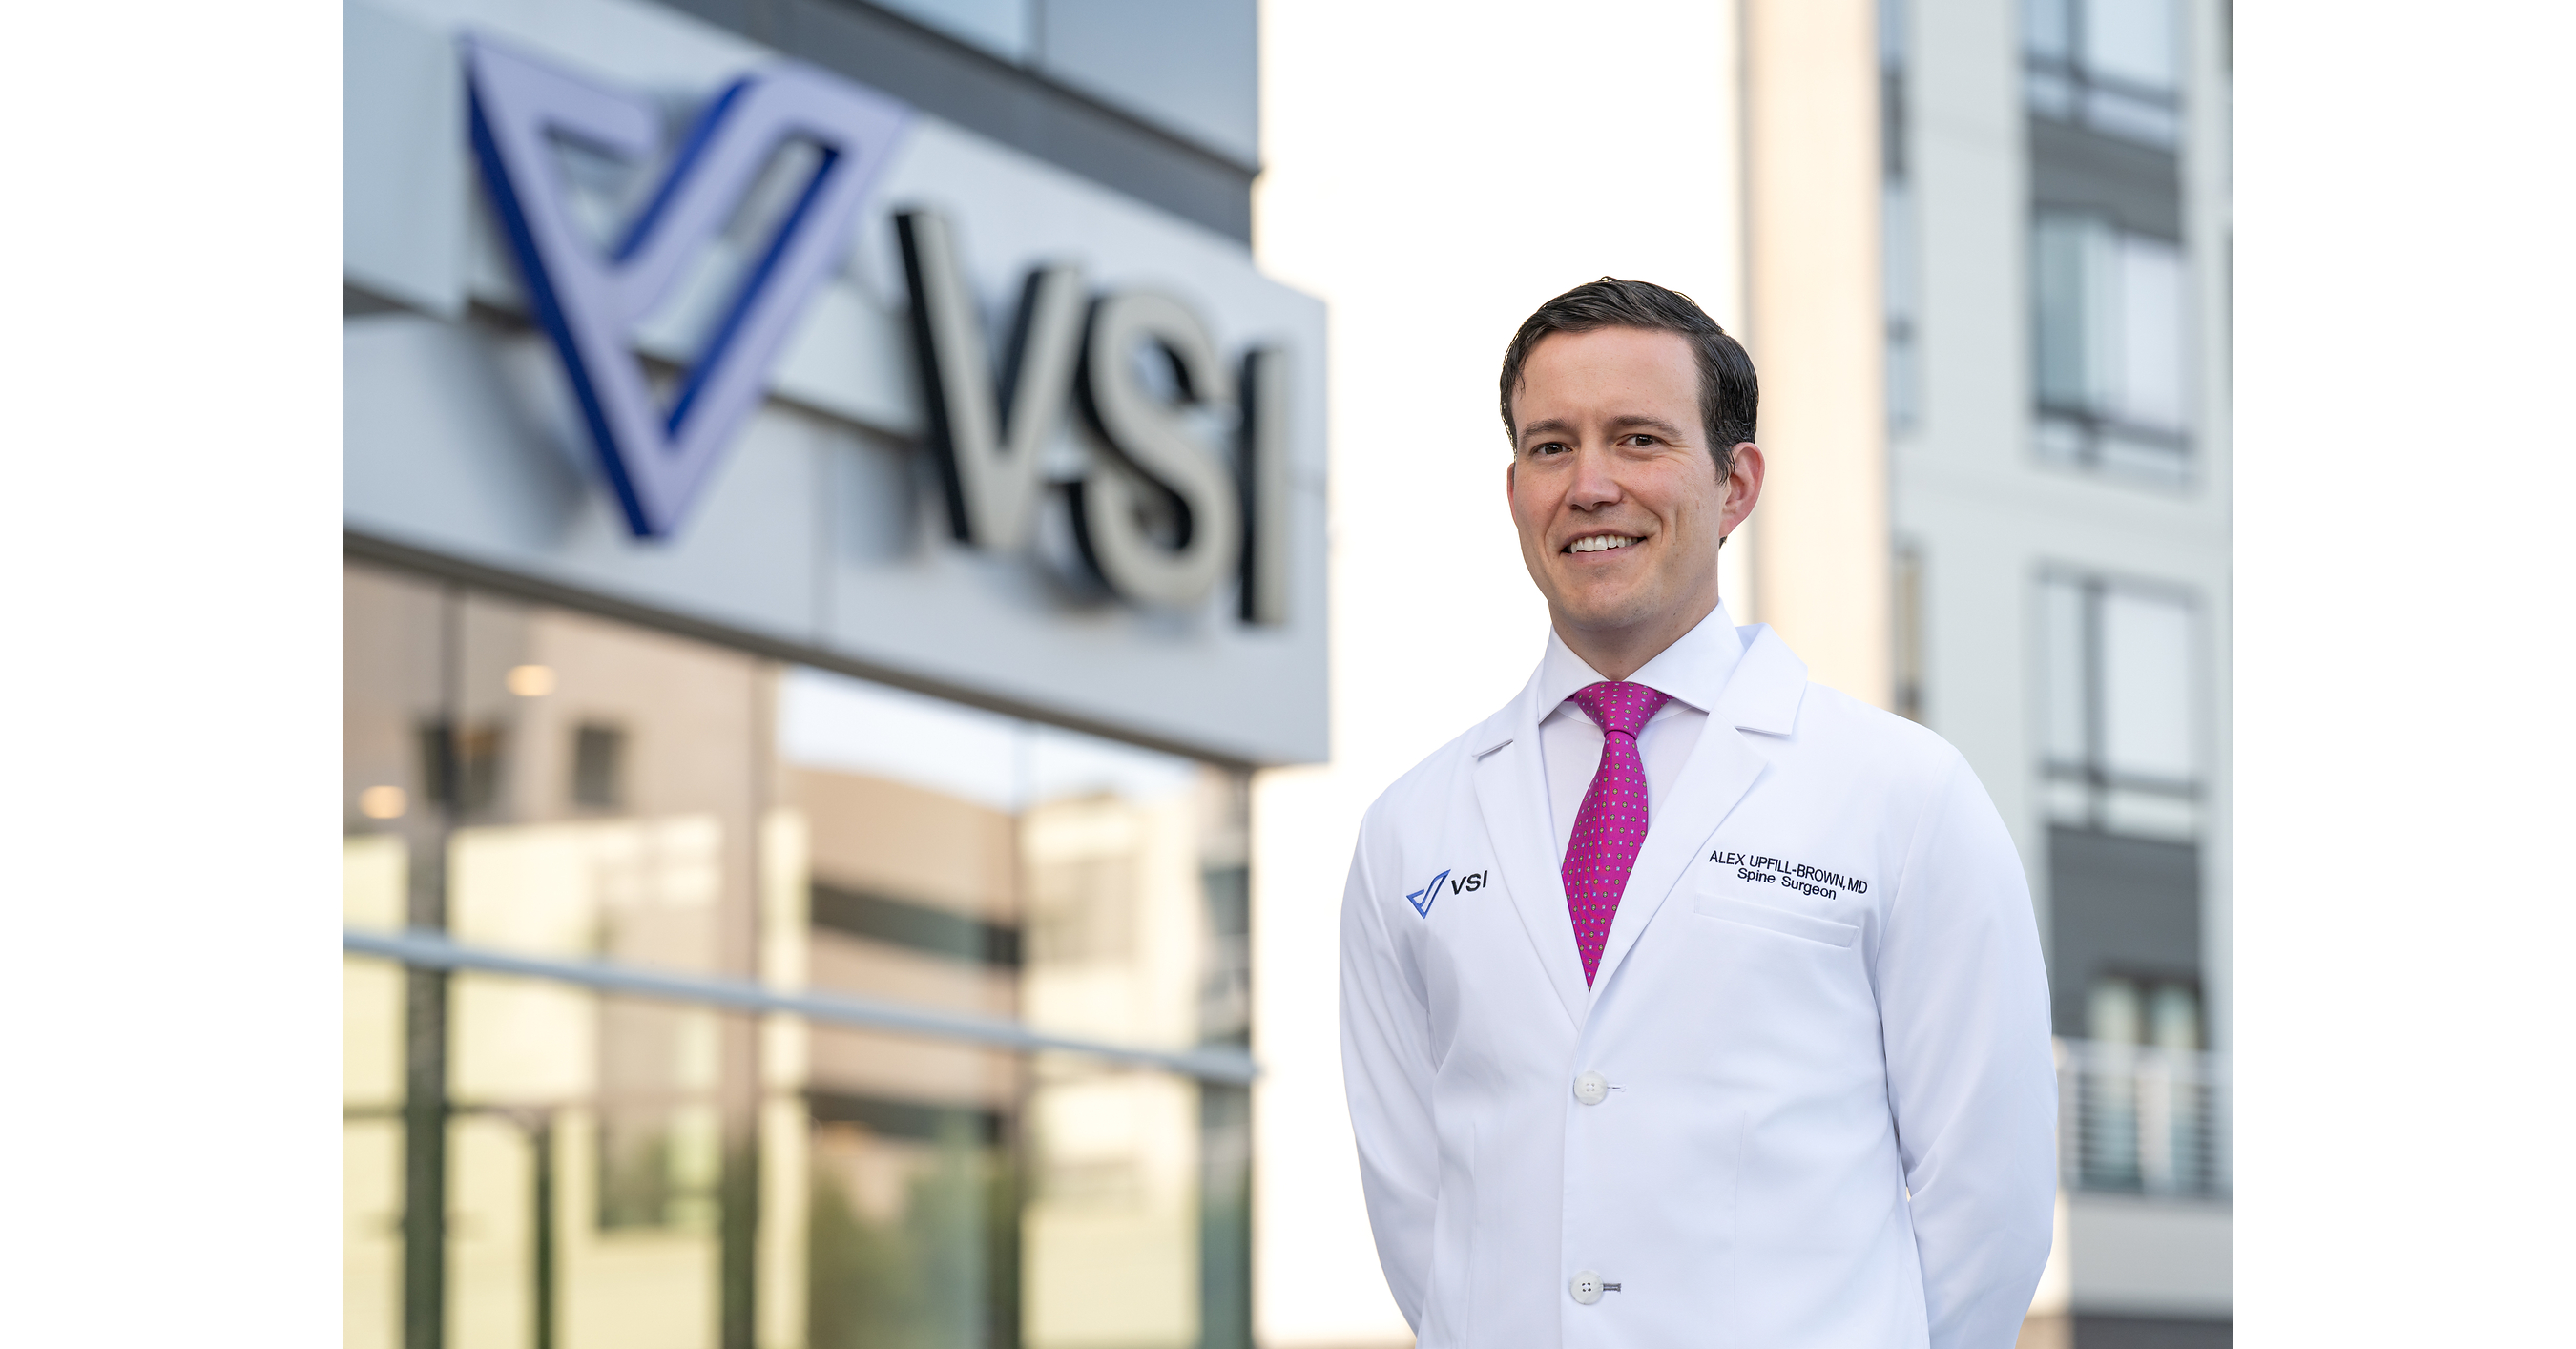
VSI Spine Solutions added orthopedic spine surgeon Alexander Upfill-Brown, MD, MSc, to expand surgical capacity amid rising patient demand at its Reston center. He brings minimally invasive and endoscopic spine surgery expertise and has authored or co-authored nearly 100 research publications. The announcement describes a practice expansion but provides no financial figures.
Analysis
The economic signal is incremental capacity at a private specialty practice, not evidence of a material change in the investable healthcare outlook. A new surgeon creates value only if VSI can translate demand into additional staffed operating-room time, payer-authorized cases, and profitable utilization; hiring alone does not establish any of those. Minimally invasive techniques could improve throughput or shift cases toward outpatient settings, but that may also require equipment, training, and facility investment, while reimbursement and case mix determine whether the margin benefit accrues to the practice or facility.
The competitive read-through is local: adding specialist capacity may help VSI retain referrals and compete for complex cases, while nearby hospitals and spine practices could face modest referral pressure if access is a binding constraint. There is no evidence here to quantify market-share gains, procedure volumes, or effects on any public company. The announcement is promotional and provides no financial or utilization data.
Near term, this is unlikely to be a standalone catalyst for listed healthcare names. Over 1–3 months, the useful checks are hiring continuation, operating-room availability, payer mix, and procedure volume. Over 6–18 months, broader adoption of minimally invasive and navigation-assisted procedures could change equipment and outpatient demand, but this hire alone does not establish that trend. The contrarian point is that specialist recruitment can signal demand, yet may also be defensive capacity expansion with returns dependent on execution.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No direct trade: VSI is not identified as a listed issuer in the supplied data, and the announcement does not support a measurable earnings revision for public equities.
- Treat as a watch item for regional healthcare operators and spine-related medtech exposure; do not infer a supplier winner without evidence of equipment purchases or procedure growth.
- If monitoring the thesis, seek subsequent evidence on incremental cases, operating-room utilization, payer mix, and recruitment costs before attributing revenue or margin upside.
- Falsification: no sustained increase in procedure volume or access capacity, or evidence that added staffing and facility costs rise faster than realized case revenue, would undermine the expansion thesis.
More News
- Elon Musk blames Indian 'oligarchs' for stalling Starlink launch
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
- Anthropic will be 'most ridiculous IPO' of year, analyst says
- Levi Strauss hikes profit guidance after tariff refunds, but its sales outlook is less optimistic
- Samsung Q3 profit surges to record high, but misses lofty expectations
- Brazil is having its Argentina moment. How to play it