
Next Africa: Trump’s Aversion to UK Island Handover Puts Burnham in a Fix
Source: Bloomberg
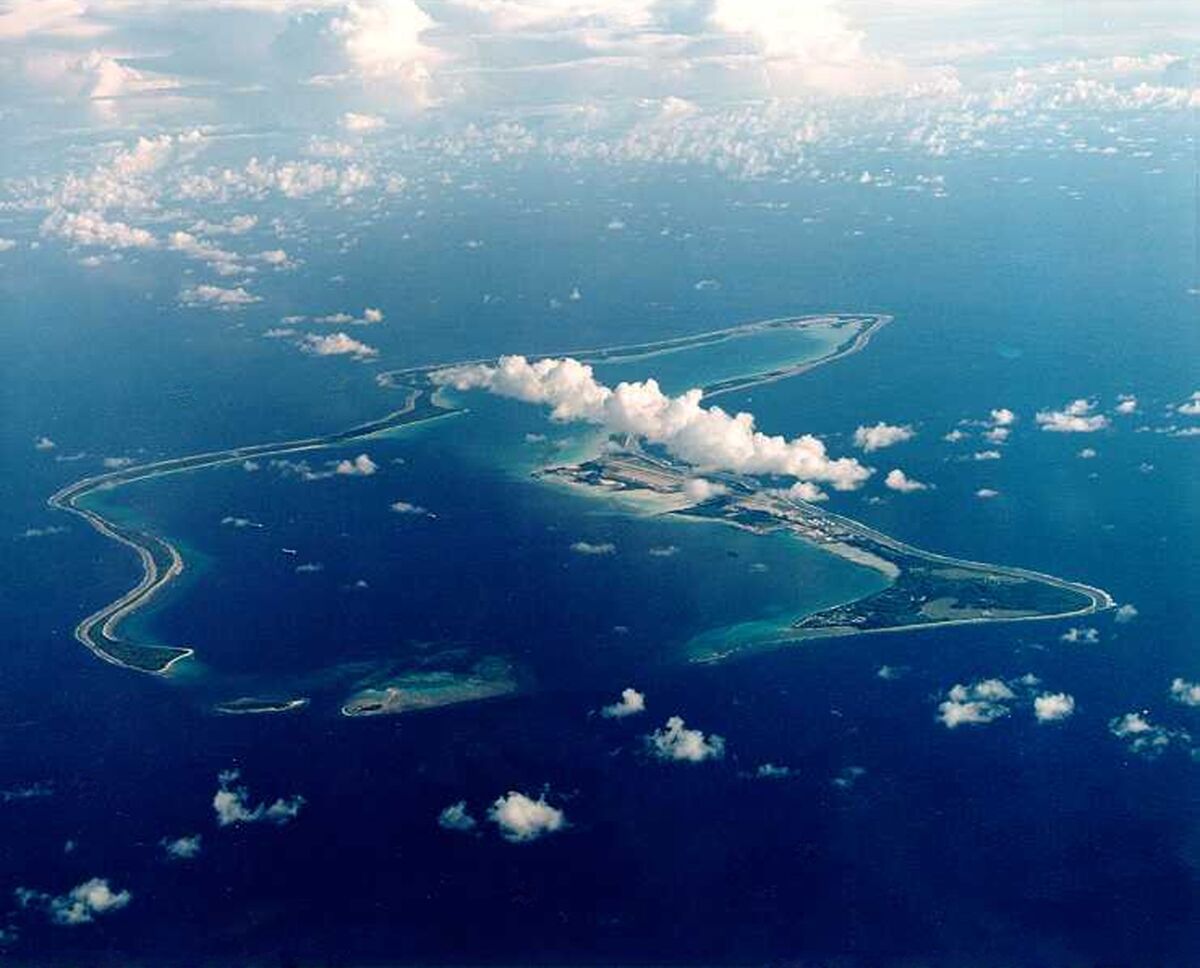
UK plans to transfer sovereignty of the Chagos Islands to Mauritius have stalled amid opposition from President Donald Trump, creating political pressure for Andy Burnham. Burnham reaffirmed the UK’s commitment to cede ownership, but the dispute adds uncertainty to the timing and implementation of the handover.
Analysis
The market consequence is not Mauritian sovereign exposure; it is a modest increase in policy uncertainty around the Indian Ocean basing network and UK-US defense coordination. The most direct listed sensitivities are BAE Systems (BAESY), Lockheed Martin (LMT), Northrop Grumman (NOC), and RTX (RTX), but any revenue effect is likely immaterial relative to existing defense backlogs unless negotiations disrupt access, force new infrastructure spending, or alter force-posture requirements.
Over the next 1-3 months, political friction could create incremental demand for contingency planning, logistics, surveillance, communications, and base-modernization work. That is directionally supportive for defense-services exposure, particularly UK-listed Babcock (BAB.L) and QinetiQ (QQ.L), but the procurement path is too opaque to underwrite a trade on this development alone. The more investable transmission channel would be a broader UK-US defense-policy divergence, which could raise the discount rate applied to UK defense contractors despite stable earnings.
The contrarian point is that a delayed settlement may be more supportive than adverse for defense equities: prolonged ambiguity often preserves current operational arrangements while increasing the probability of transition-related spending. Conversely, a rapid political resolution that guarantees long-duration access would remove the contingency-spending narrative but should be fundamentally neutral-to-positive for contractors through lower operating risk. This is a watch item rather than a standalone catalyst; no material cross-asset repricing is justified at current information depth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.10
Key Decisions for Investors
- No standalone directional trade: maintain existing defense exposure rather than adding risk solely on the territorial-policy headline; the expected earnings sensitivity for LMT, NOC, RTX, and BAESY is below materiality absent a disclosed contract or basing-capex program.
- Set an event-driven alert for any treaty language affecting basing tenure, operational access, or required infrastructure investment. A confirmed multiyear modernization or relocation program would favor a basket long BAESY/QQ.L/BAB.L, with position sizing contingent on contract value and funding source.
- For UK-defense holdings, monitor relative performance of BAESY versus LMT over the next 1-3 months. A widening underperformance gap without order-book deterioration could present a tactical long BAESY / short LMT pair, but only if UK-US policy tension remains rhetorical rather than procurement-related.
- Thesis falsifier for any defense-services long: a binding agreement that preserves access without new capex, combined with no incremental UK or US defense-budget authorization, would eliminate the principal route to earnings upside.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Dollar holds near 2-month high as markets weigh rate hikes, Iran diplomacy
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Vendor Landscape for Institutional Investment Teams
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk