
STRATEGISCHE PARTNERSCHAFT MIT CARESTER ZUR ENTWICKLUNG DER OXIDTRENNUNG UND 10-JAHRES-ABNAHMEVERTRAG
Source: PR Newswire
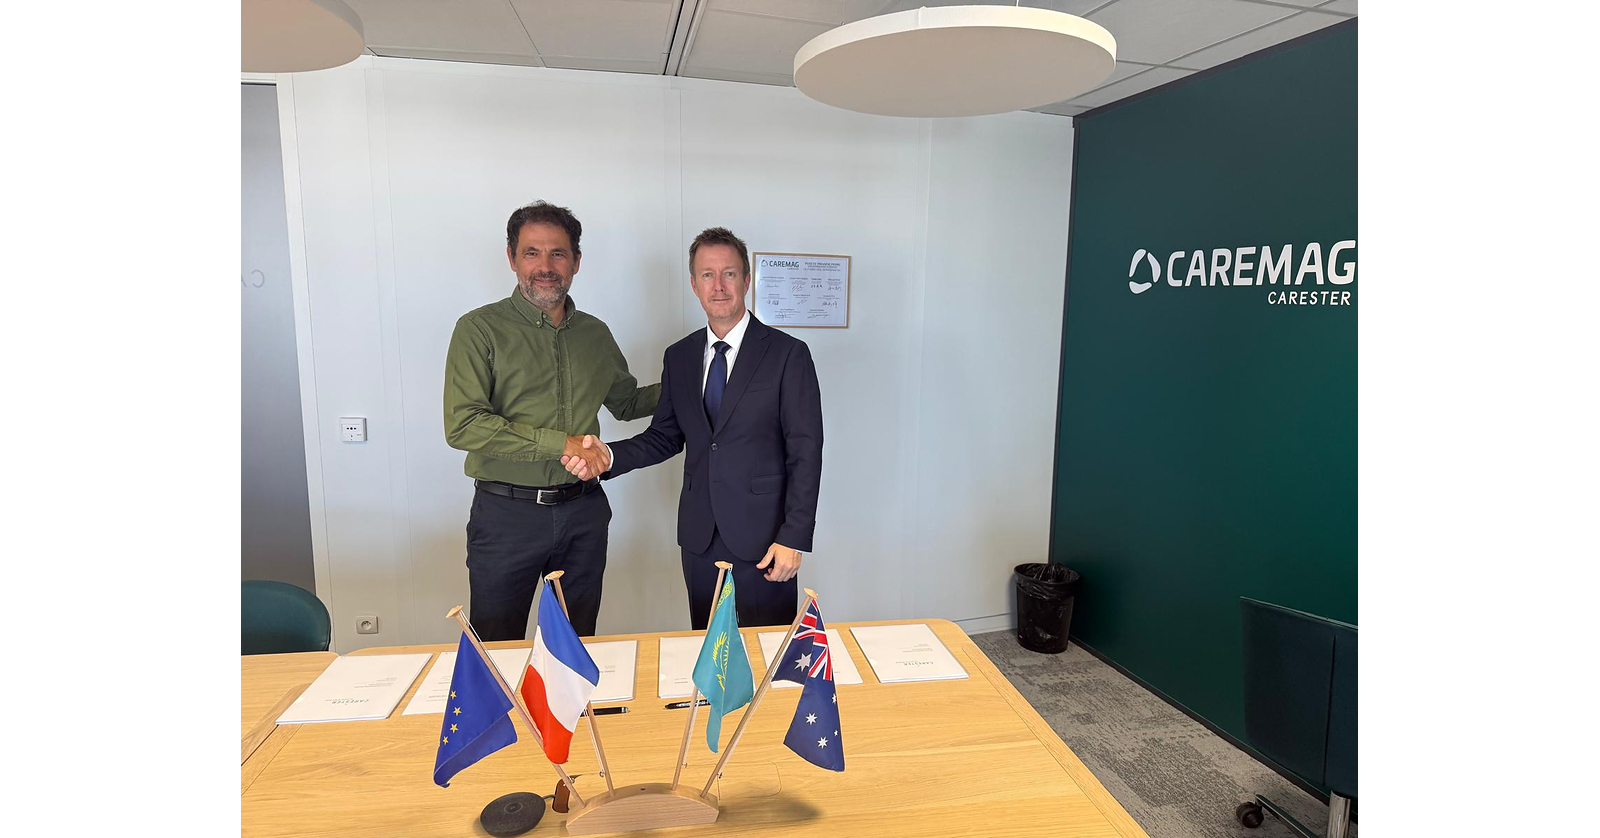
Lindian Resources secured a long-term offtake and technology/engineering partnership with Carester to develop an 8,000 tpa rare-earth oxide separation (REO) SX plant in Stepnogorsk, Kazakhstan, with the DFS targeted for completion in Q4 2026. Carester will buy 70% of SEGH output under a binding contract (10-year term plus two 5-year extensions) and holds RoFR on 70% of MHREC volumes, strengthening revenue visibility into higher-value NdPr, Dy/Tb and Y products. The related Caremag refinery in France is reportedly funded with €216m and is intended to cover ~15% of global Dy/Tb oxide demand, positioning Lindian as a more vertically integrated supplier with financing supported by AUD 125m in undrawn Nico credit lines and operating cash flows.
Analysis
This is primarily a de-risking event, not a near-term earnings inflection. The economic value is in lowering project-failure probability and improving financing terms, which matters more for a pre-cash-flow junior than for the engineering counterpart. TTEK should see only a modest direct benefit from study work, but the headline can broaden its niche credibility in complex process consulting; the bigger upside is a higher win rate on adjacent critical-minerals scopes over the next 12-18 months.
For the rare-earth supply chain, the second-order effect is that a credible non-China separation path strengthens the whole western magnet-material ecosystem, especially heavy-REE pricing power. That said, a single 8ktpa plant is too small to change global supply balances in the next 1-3 years; the real market impact is on valuation multiples for integrated developers that can show downstream optionality. If management can show capex discipline and on-time commissioning, the discount rate on the equity should compress; if not, the market will reprice this as another long-dated optionality story with funding risk.
Contrarian view: consensus is likely overweighting the strategic rhetoric and underweighting execution complexity. A binding offtake before DFS completion can be read as industrial validation, but it is not the same as bankable economics; the key variable is whether the project can be funded without dilution once real capex is disclosed. The thesis breaks if the DFS slips materially beyond Q1 2027, if commissioning dates move, or if heavy-REE pricing softens enough to impair the value of the downstream split.
Near term, this is more of a sentiment catalyst than a fundamental one; over 6-18 months it could matter if it lowers Lindian’s cost of capital and attracts third-party feedstock. Until then, the market is likely to trade the story as a positive option on Western rare-earth processing rather than assign full NPV credit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Small tactical long TTEK for 1-3 months into DFS follow-through; treat the headline as a credibility trade, not an earnings step-up. Risk/reward is favorable if the market rewards specialty-process visibility, but trim quickly if no follow-on contract language emerges.
- Do not chase IWTNF on the headline alone; wait for the DFS and capex disclosure. Enter only if the study confirms materially lower-than-peers capex intensity and no financing gap, otherwise the equity is likely to remain dilution-sensitive.
- Use a pair trade: long TTEK / short a basket of high-beta rare-earth juniors that depend on 'future downstream optionality' rather than operating cash flow. The goal is to own the consultant with current-fee visibility and fade projects that are still years from self-funding.
- Set an alert on any evidence that the downstream plant will require external equity or project debt on punitive terms; that would be the first sign the market is overpricing the strategic narrative.
- If the sector rallies on the news, consider fading the move in pure-play rare-earth producers after 1-2 sessions; the incremental physical supply is remote, so immediate price impact on oxide benchmarks should be limited.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China’s Coal Output Drops as Concerns Build Over Winter Supply
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- Brent crude hovers near $109 a barrel as Ukraine resumes energy strikes, tankers attacked in Middle East