
Envision Energy odnotowuje postępy na rynku energetyki wiatrowej w Europie Południowo-Wschodniej z chwilą zamknięcia finansowego największej inwestycji obejmującej elektrownię wiatrową w Macedonii Północnej
Source: PR Newswire
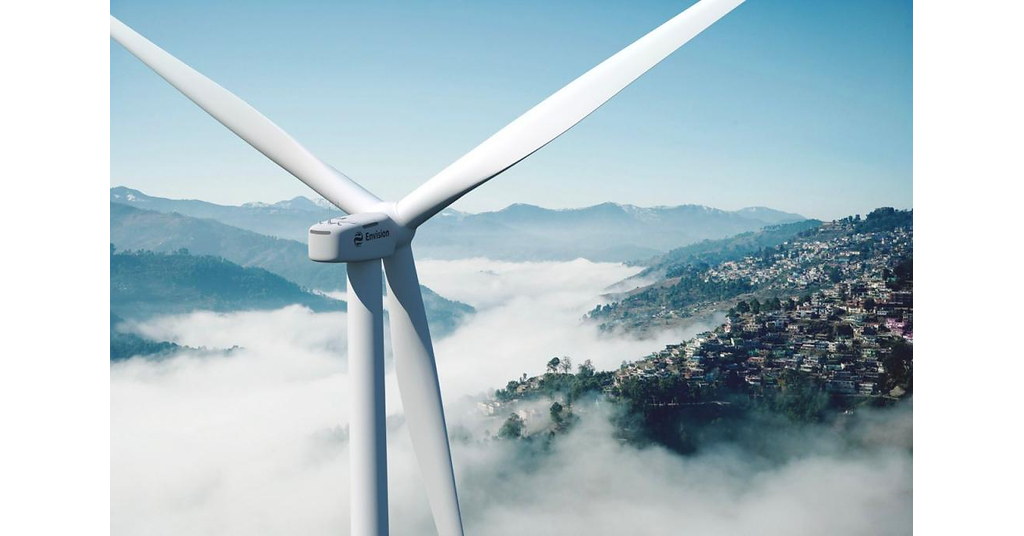
Envision Energy and Alcazar Energy Partners reached financial close on the 131.25 MW first phase of the Štip wind farm, the largest wind-power project in North Macedonia. Envision will supply 21 EN182 turbines rated at 6.25 MW each, while the planned three-phase project could reach 396 MW and more than quadruple the country’s installed wind capacity. The project is supported by a long-term private corporate PPA and financing recognition from EBRD, IFC and Erste, strengthening the commercial bankability of utility-scale renewables in Southeast Europe.
Analysis
The relevant signal is not the project’s near-term earnings contribution but lender acceptance of a Chinese turbine platform in an EU-adjacent, development-finance-backed transaction. That can reduce perceived financing friction for Envision in Southeast Europe, where projects are often constrained more by cost of capital and offtaker credit than by equipment availability. The read-through is strongest for Envision’s private-market order pipeline; EBS is not a clean listed proxy for this exposure, so the supplied ticker should not be treated as a direct beneficiary.
For European listed OEMs, incremental bankability for Envision is marginally negative because it expands credible bidding competition in a region where procurement remains price-sensitive. Vestas (VWS.CO) and Nordex (NDX1.DE) are more exposed to potential pricing pressure than Siemens Energy (ENR.DE), whose wind segment’s project-selectivity and service backlog make the direct impact limited. The second-order beneficiary is regional grid and transmission capex: a larger intermittent-generation base raises the probability of investment in balancing, interconnection, and storage over the next 2-5 years, favoring Schneider Electric (SU.PA), Siemens Energy and selected Balkan utilities—but only after permitting and grid-connection commitments become visible.
Over the next 1-3 months, this is primarily a private-market validation event rather than a catalyst for liquid equities. The thesis would strengthen if Envision wins additional EBRD/IFC-supported European orders or if comparable project-finance debt spreads tighten; it is falsified by construction delays, turbine availability/warranty issues, or an inability to replicate private corporate PPAs at comparable pricing. The contrarian view is that the financing milestone may be overinterpreted: development-finance participation can be project-specific and does not necessarily translate into broad Western European market access, where local-content requirements, cybersecurity scrutiny and service-network depth remain material barriers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Key Decisions for Investors
- No directional position in EBS: confirm issuer identity, liquidity and direct economic linkage to Envision before treating the news as investable.
- Place VWS.CO and NDX1.DE on a 3-6 month competitive-risk watch: initiate no short solely on this event; consider a short only if subsequent Envision awards coincide with renewed OEM pricing concessions or order-margin guidance pressure.
- Maintain/consider a 6-18 month overweight in grid-enablers SU.PA and ENR.DE versus European wind OEMs, expressed as long SU.PA or ENR.DE / short VWS.CO basket. The trade requires evidence of Southeast European transmission tenders and grid-connection capex; without that, the project is too small to move earnings.
- Monitor EBRD/IFC disclosures and regional PPA pricing quarterly. A second financed Envision project or a disclosed multi-project framework would be a stronger catalyst than this single award; conversely, project debt repricing higher by roughly 100bp or material construction slippage would invalidate the regional-financing read-through.
More News
- Why is Booking stock sliding today?
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- Japan's 10-year bond yield hits 30-year high following sell-off in Treasurys
- America’s Asian allies want a Trump-Xi truce — but not at their expense
- US Debt Selloff Spans Most Maturities: Evening Briefing Americas
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Build an Automated Research Process for a Fund
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search