
Grid Metals Announces Maiden Cesium Resource at Falcon West; Establishes Lucy South Cesium Deposit as the World's Second Largest Cesium Resource in Active Development
Source: Newswire
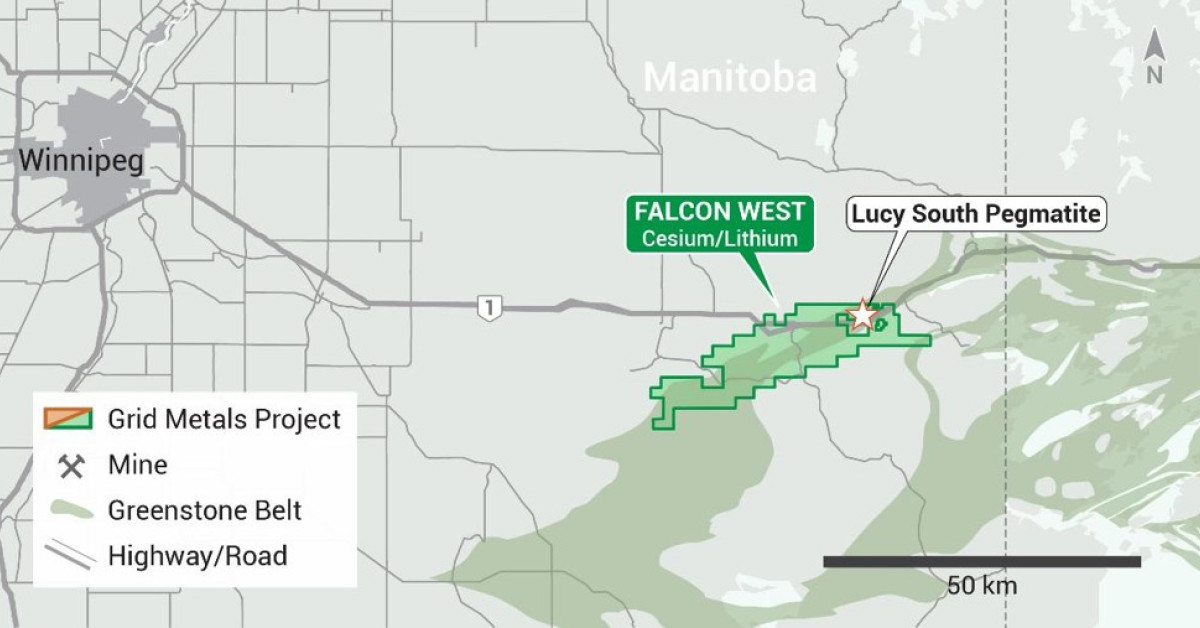
Grid Metals announced a maiden measured resource at its Lucy South cesium deposit of 51,500 tonnes grading 2.58% Cs2O and 1.47% Li2O, containing 1,322 tonnes of Cs2O. The higher-grade pollucite zone contains 15,600 tonnes at 5.19% Cs2O, is roughly 20 metres below surface, and is considered amenable to conventional open-pit extraction. Grid, which holds an 85% interest alongside Agnico Eagle-owned Avenir, plans metallurgical testing, permitting preparation, stakeholder engagement and winter drilling as it targets commercial production into a constrained global cesium supply market.
Analysis
GRDM’s likely equity rerating is driven less by contained-metal arithmetic than by whether it can establish a qualified concentrate specification and a contracted downstream buyer. Cesium is an unusually opaque, small-volume market: a new source can command strategic scarcity value, but its addressable revenue is capped by customer qualification cycles and incumbent inventory behavior. The lithium co-product provides optionality, yet it should not be credited at full value until recoveries, separation costs and concentrate penalties are demonstrated.
The near-term setup is favorable for GRDM because a measured resource reduces geological-risk discounting, but the next valuation gate is metallurgical proof rather than additional drilling. Ore sorting could materially reduce capex and permitting footprint; failure to achieve a saleable, consistent concentrate would turn a headline resource into a stranded specialty-mineral asset. PMET is the closest public read-through: competing Canadian supply could weaken eventual pricing power, while any western-government procurement or offtake initiative would validate both assets and expand strategic multiples.
AEM’s indirect minority exposure is immaterial to NAV and should not move the stock; TECK.A and BOL similarly have no actionable earnings sensitivity. The contrarian issue is that “supply shortage” does not automatically mean high realized margins: a concentrated buyer base can exercise monopsony power, particularly before GRDM secures an offtake. Over 6-18 months, successful permitting and an offtake could justify a step-change in GRDM’s multiple; absent those, financing dilution is the dominant risk for a junior developer.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.67
Ticker Sentiment
Key Decisions for Investors
- Initiate only a small, liquidity-adjusted long in GRDM/MSMGF following confirmation of adequate trading liquidity; target a 6-12 month catalyst window around metallurgical results, permitting milestones and a binding offtake. Size as venture-risk capital, with thesis invalidated by sub-commercial concentrate results, a material equity raise ahead of offtake, or permitting delays beyond management’s disclosed timeline.
- Do not use AEM as a cesium proxy: its indirect interest is too small to affect consolidated earnings or NAV. Any news-driven strength in AEM attributable to Falcon West should be viewed as an opportunity to avoid chasing rather than a basis for a position.
- Monitor PMET as a relative-value comparator rather than establish a pair immediately. A long GRDM/short PMET trade requires comparable data on recoveries, expected concentrate grade, capex and customer commitments; without these, resource-grade comparisons are not economically meaningful.
- Set an event alert for a binding cesium offtake with minimum pricing or government-backed procurement. That would be the first externally verifiable evidence that specialty-mineral scarcity converts into cash flow and would justify increasing GRDM exposure; exploration extensions alone are lower-quality catalysts.
More News
- European shares set for first monthly loss in six as bond yields weigh
- Evolve Royalties at Mining Forum Americas 2026: copper push gains pace
- UK Prime Minister Burnham says Iran 'played a part' in British air base incident
- South Korea’s exports hit record high on AI boom
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices