
Jacob's Pardon, the Whiskey Born From an FDR Pardon, Releases Its First-Ever Bourbon
Source: PR Newswire
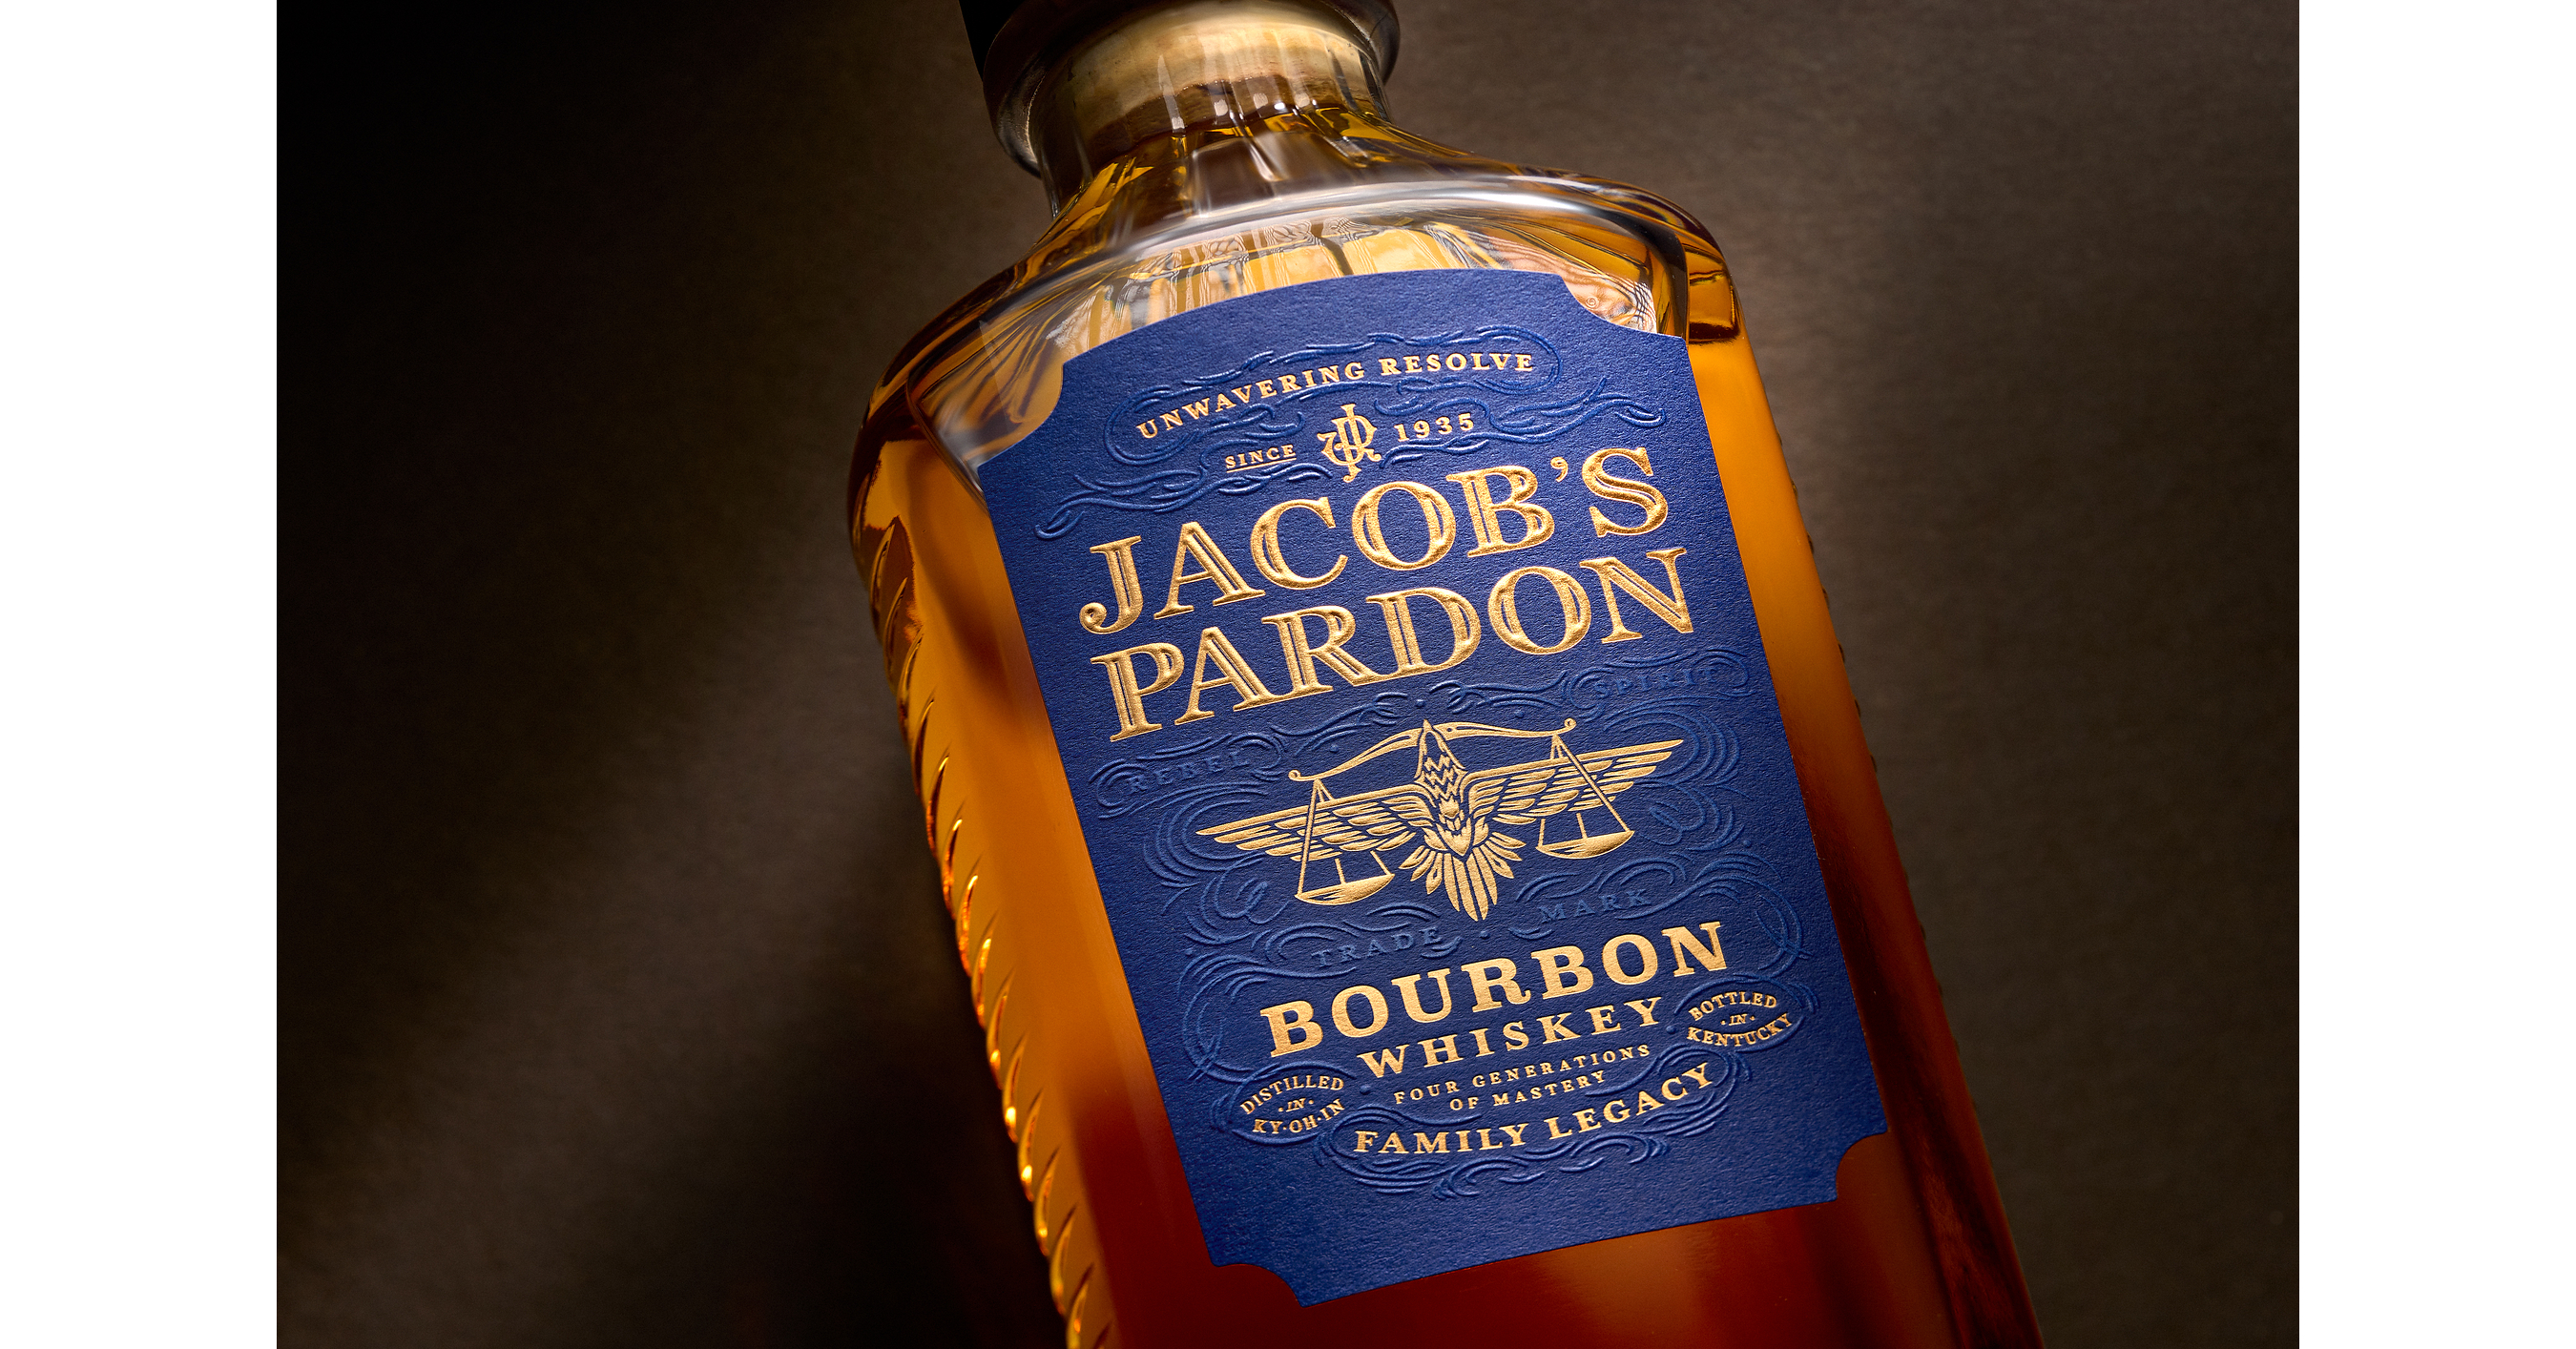
Jacob's Pardon launched its first nationally available bourbon, a 90-proof four-grain blend sourced from Kentucky, Ohio, and Indiana, at a suggested retail price of $59.99. The release expands the brand beyond its limited Heritage Collection offerings into the premium, broader-distribution bourbon market. The announcement is a positive brand-expansion development but is unlikely to materially affect public markets.
Analysis
This is not investable public-equity news: Palm Bay International and Jacob's Pardon are privately held, and a single premium SKU launch carries no measurable read-through for listed spirits companies. The relevant mechanism is category competition at the $50-$70 shelf: a nationally distributed, sourced blend can win trial through distributor execution and storytelling, but its economics are likely constrained by purchased-whiskey costs, retailer/distributor margins, and promotional spend rather than signaling broad premium-bourbon demand.
For listed peers, the more relevant second-order point is that independent brands are increasingly targeting the premium price tier without the aging-capital burden of owning distilleries. That marginally raises shelf-space and on-premise competition for Brown-Forman (BF.B), Diageo (DEO), and MGP Ingredients (MGPI), but is too small to alter earnings expectations. MGPI is the only plausible positive read-through if the product’s Indiana component is sourced from its network; that supplier relationship is unconfirmed and should not be assumed.
Over the next 1-3 months, watch retailer velocity, depletion data, and evidence of sustained discounting. A rapid national rollout at a $60 price point can create channel inventory without consumer pull; that would be a negative signal for premium-whiskey elasticity, particularly if it coincides with weaker holiday sell-through. Over 6-18 months, successful sourced brands could reinforce the strategic value of flexible bulk-whiskey supply, but this launch alone does not justify a sector position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No immediate trade: treat the announcement as non-material until third-party depletion, distribution-door count, and repeat-purchase data emerge.
- Set an alert on MGPI for confirmed sourcing or a disclosed supply agreement; a verified multi-year volume commitment would be incrementally supportive to utilization and mix, but absent disclosure remains speculation.
- Maintain BF.B and DEO as category-demand watch items rather than shorts: only revisit if syndicated data show broad $50-$70 bourbon velocity weakening through the holiday period, which would challenge premiumization assumptions.
- For a consumer-staples risk hedge, monitor U.S. spirits retail scanner data versus beer/RTD share over the next two quarters; a sustained premium-spirits slowdown would be more actionable through relative underweight of BF.B/DEO versus broader staples than through this brand-specific event.
More News
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today