
Elke zonnestraal optimaal benutten, energie brengen waar die ontbreekt: 2026 Global Low-Carbon Industry Forum verkent mogelijkheden om de wereldwijde elektriciteitskloof te overbruggen
Source: PR Newswire
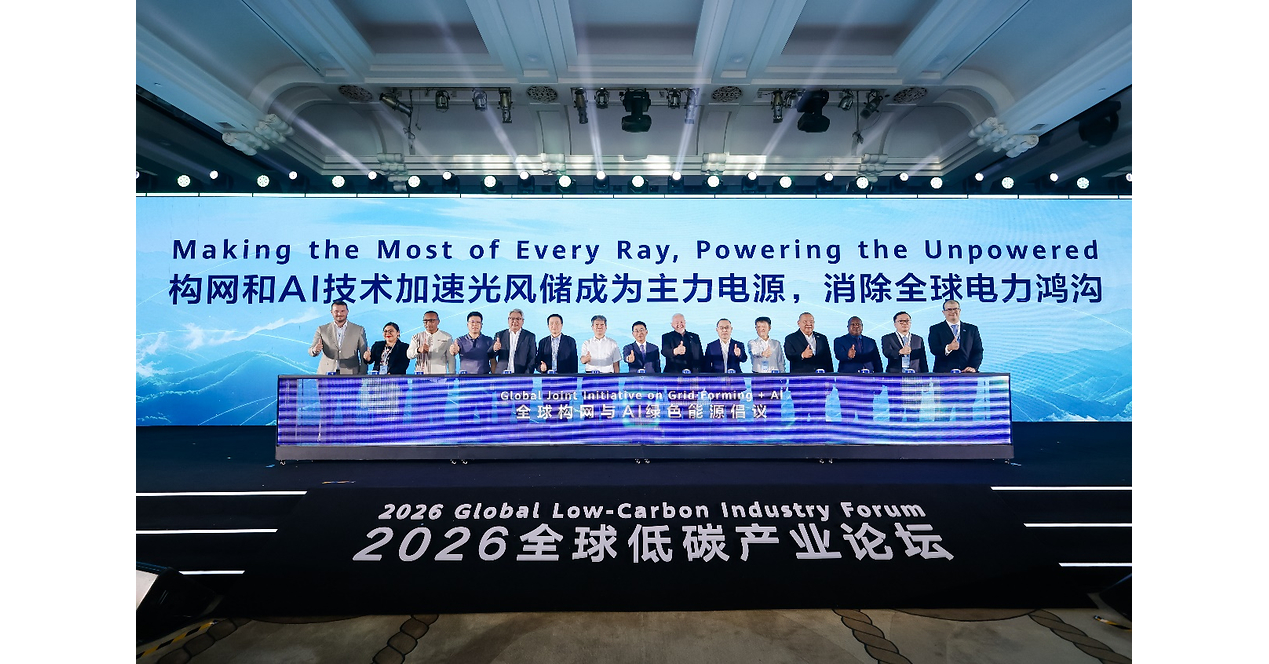
Het Global Low-Carbon Industry Forum lanceerde een gezamenlijk initiatief om grid-forming-technologie en AI sneller te standaardiseren en toe te passen, gericht op betrouwbare, betaalbare hernieuwbare elektriciteit voor onder meer bijna 700 miljoen mensen zonder stroomtoegang. Het MTerra Solar-project in de Filipijnen heeft fase 1 met 2,5 GWp zonnecapaciteit en 3,3 GWh batterijopslag in commerciële operatie gebracht; het volledige project omvat 3,5 GW PV en 4,5 GWh ESS. Volgens de projectontwikkelaar kan het circa 2,4 miljoen huishoudens van elektriciteit voorzien en jaarlijks meer dan 4,3 miljoen ton CO2-uitstoot vermijden, waarmee grootschalige PV-plus-opslag als netondersteunende energiebron wordt gevalideerd.
Analysis
This is promotional rather than investable evidence, but it reinforces an important procurement shift: storage is moving from an energy-arbitrage asset toward a grid-services asset. Where regulators create explicit payments for synthetic inertia, fast-frequency response, and islanding capability, revenue stacks improve and projects with compliant inverter controls should clear ahead of commodity BESS installations. Near-term beneficiaries are likely grid-equipment suppliers with certified power-electronics portfolios—SMA Solar (S92.DE), Siemens Energy (ENR.DE), GE Vernova (GEV), and Fluence (FLNC)—rather than upstream solar module manufacturers, whose economics remain dominated by oversupply and price deflation.
The underappreciated second-order implication is AI-load growth: hyperscale data centers increasingly need to fund on-site storage, UPS upgrades, and flexible-load controls to secure interconnection and avoid curtailment. This supports electrical-balance-of-plant demand for Eaton (ETN), Vertiv (VRT), Schneider Electric (SU.PA), and ABB (ABBN.SW), but the benefit is likely to emerge over 6-18 months as grid operators formalize connection requirements. The risk is that “grid-forming” remains a feature without a standardized, bankable capacity payment; in that case customers will favor lowest-cost inverters and batteries, limiting pricing power.
Consensus may over-credit battery-cell producers for this theme. Grid-forming value accrues principally to inverter software, controls, certification, and project integration, while cells remain exposed to Chinese supply, declining ASPs, and volatile utilization. The immediate market impact should be negligible; the actionable catalyst is European tender design and evidence that grid-services revenues materially lift storage-project IRRs over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain a 6-18 month overweight in ETN and VRT versus battery-cell exposure: data-center power-quality and on-site resilience spend has clearer pricing power than commodity storage. Reassess if hyperscaler capex guidance falls by more than 10% or backlog conversion weakens for two consecutive quarters.
- Watch-list long FLNC only after verification that new European grid-forming tenders award contracts with recurring availability payments and that FLNC discloses positive project gross margin/backlog quality. Entry should follow tender wins, not conference claims; downside is further margin pressure from fixed-price EPC commitments.
- Pair trade over 3-9 months: long GEV or ENR.DE / short TAN ETF. Grid-stability capex favors transmission, turbine, and power-electronics suppliers while broad solar-equity baskets retain module-price and financing-rate sensitivity. Exit if European storage-service rules fail to translate into funded procurement by mid-2027.
- Do not add directional solar-module exposure on this signal. A durable bullish case requires independently observable module-price stabilization, falling channel inventory, and sustained project IRRs—not technology-standardization announcements.
More News
- Iran vows 'painful' retaliation as Trump piles on pressure ahead of UN General Assembly meeting
- Oil falls as crude flows remain 'surprisingly strong'
- Trump & Xi to Meet Amidst Friction on Wars, Tech, Trade
- US Diesel Tops $6.50 a Gallon as Wars Worsen Global Fuels Crunch
- Here are the 3 big things we're watching in the stock market this week
- Tech leads shares higher in Asia, oil eases