
Smashburger Gives Its Signature Smash the New York Deli Treatment with New Pastrami Lineup
Source: PR Newswire
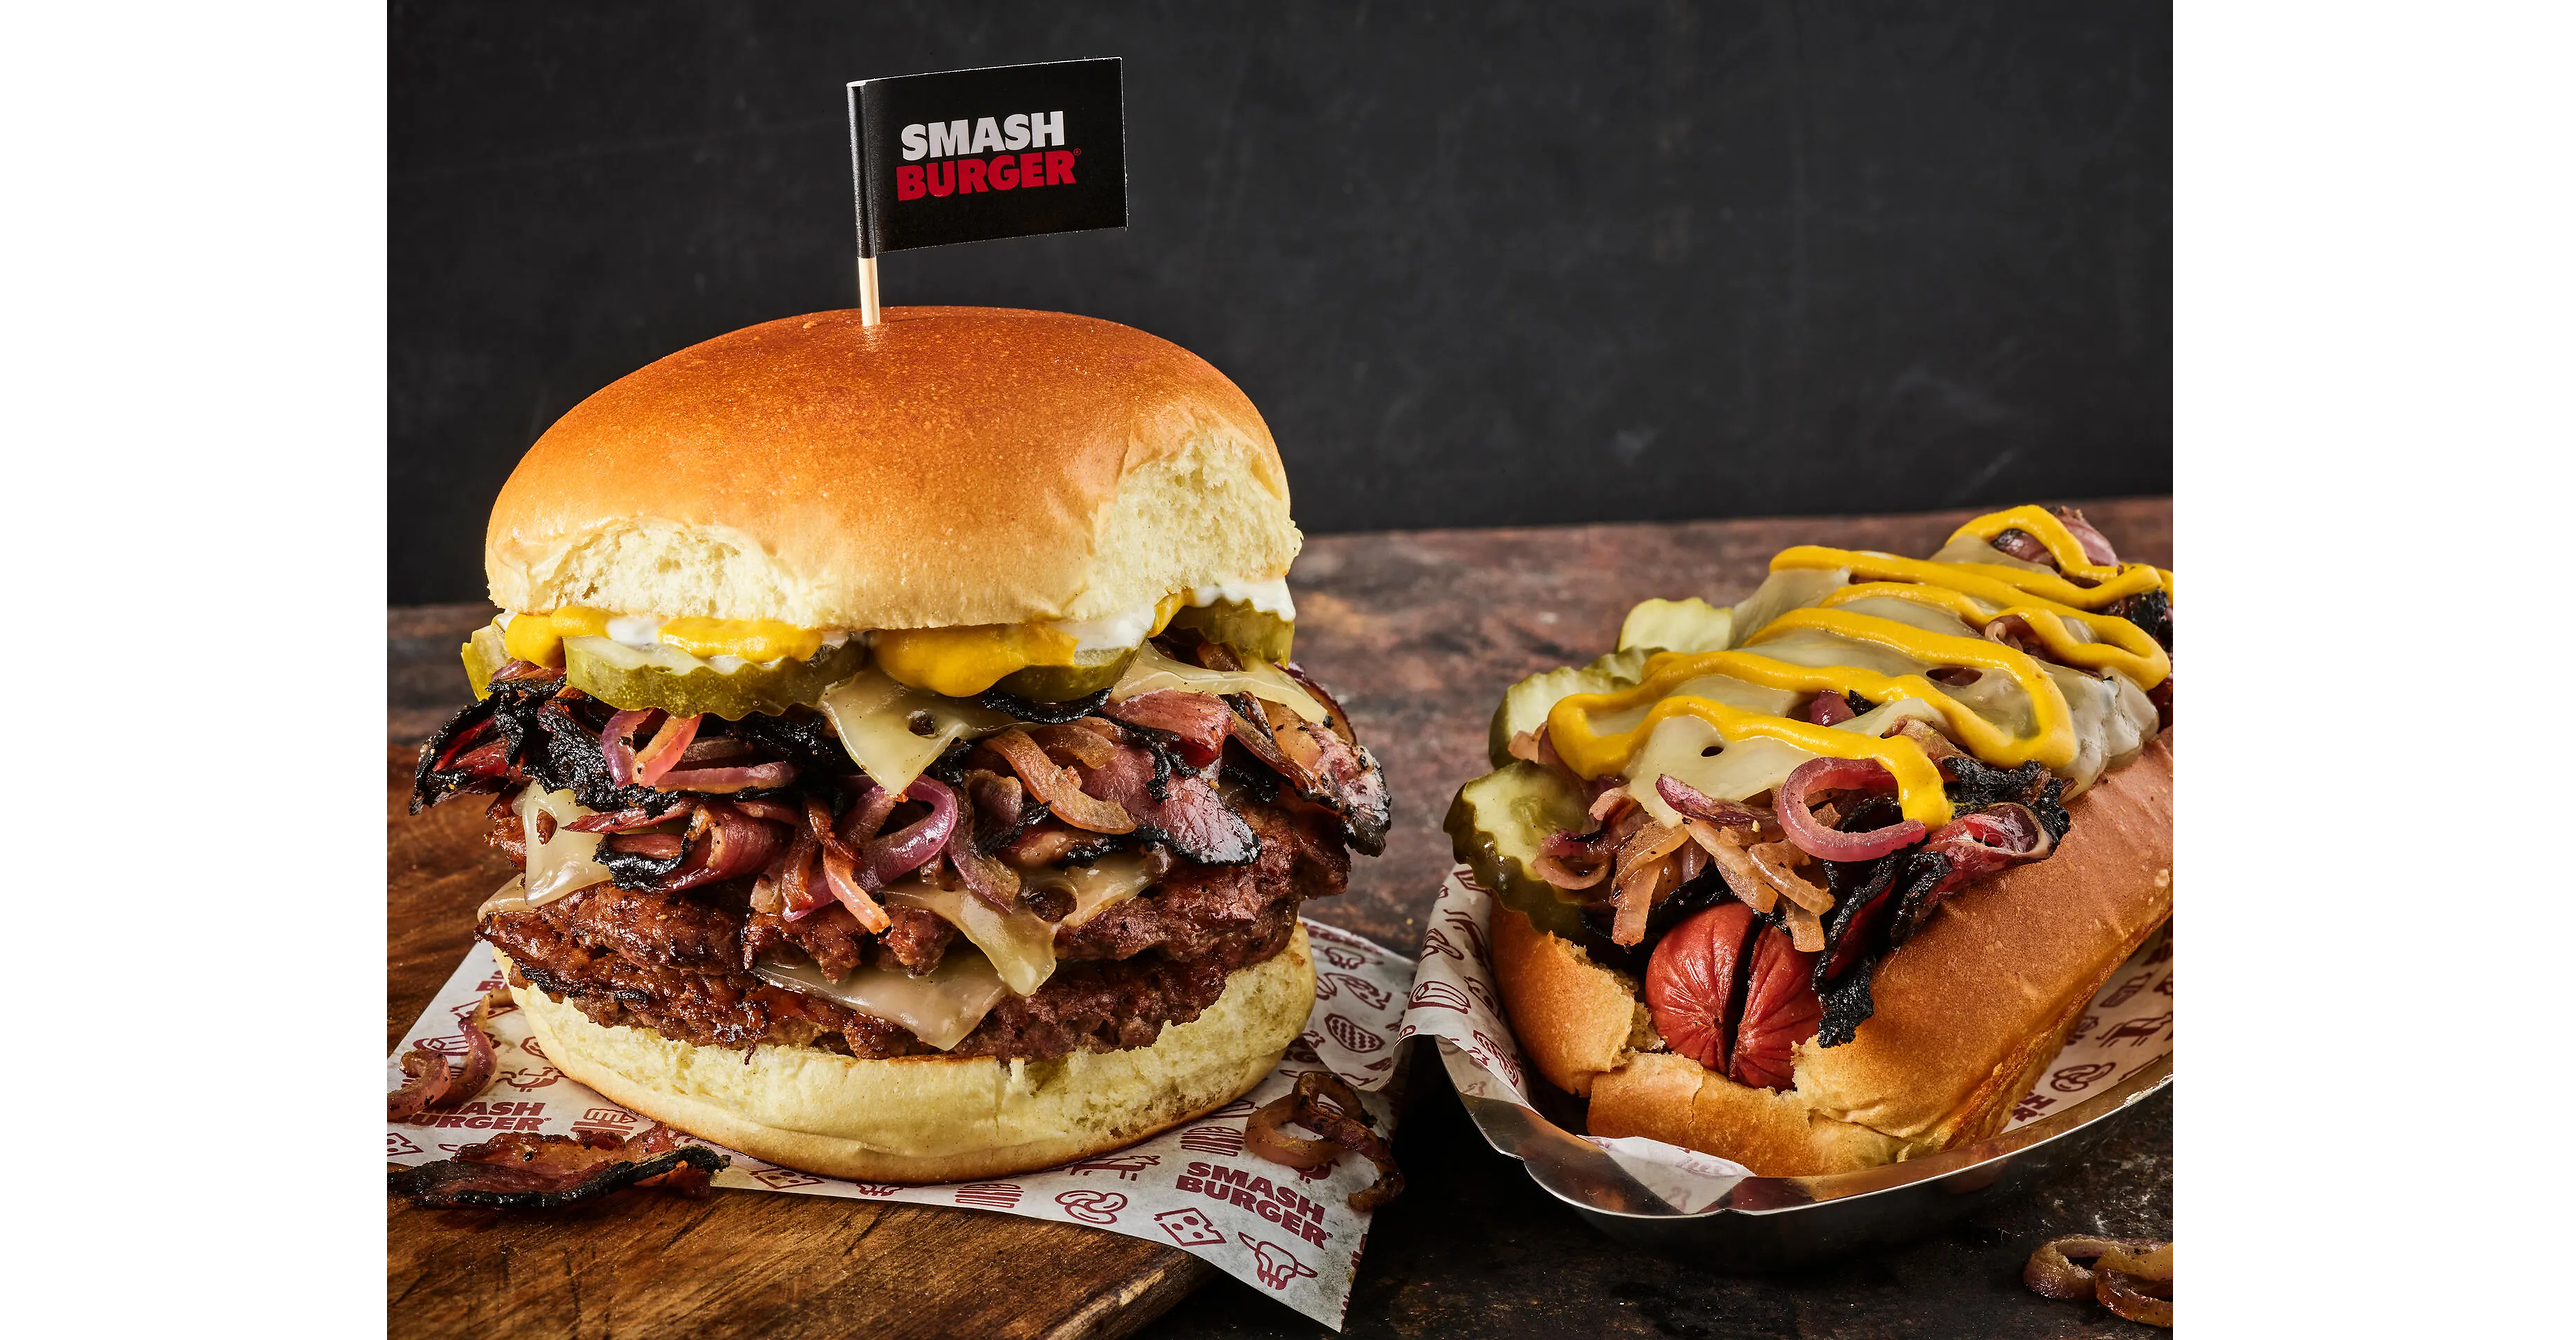
Smashburger will launch a New York deli-inspired limited-time menu nationwide at participating locations on October 6, including pastrami burgers, pastrami hot dogs and seasonal Häagen-Dazs shakes. The company also refreshed its grilled-chicken lineup with a new Avocado Club and upgraded Deluxe Grilled Chicken Sandwich, aiming to drive guest traffic while maintaining streamlined restaurant execution. The 178-location chain, wholly owned by Jollibee Foods Corporation, framed the rollout as disciplined menu innovation focused on premium ingredients and value.
Analysis
This is not investable as a standalone catalyst for Jollibee Foods Corp. (JFC): Smashburger is too small within the parent portfolio and the release provides no pricing, traffic, food-cost, or unit-economics data. The near-term read-through is instead to restaurant traffic elasticity: premium add-ons can lift check averages, but they also introduce higher-cost proteins, dairy, avocado, and bacon exposure. Absent evidence of attachment rates or margin-accretive pricing, the claimed operational discipline should be treated as unverified.
Over the next 1-3 months, the relevant signal is whether menu innovation improves transactions rather than merely shifts mix from existing burgers. A successful launch would support the broader fast-casual view that differentiated indulgence can retain traffic despite consumer pressure; weak promotional uptake would reinforce the advantage of scaled value platforms such as McDonald's (MCD), Restaurant Brands (QSR), and Yum! Brands (YUM), which have greater purchasing leverage and advertising reach. Supply-chain impact is immaterial for public beef, dairy, or avocado proxies at this unit count.
The contrarian point is that expanded chicken and value-oriented protein choice may be defensive rather than growth-oriented, signaling an effort to reduce dependence on premium beef occasions. Six-to-eighteen months, the issue is whether the concept can improve restaurant-level margins and franchise appeal sufficiently to justify expansion; without same-store sales acceleration and improved corporate-store profitability, additional menu complexity is more likely to dilute labor throughput than create a durable valuation catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No standalone position in JFC based on this release; monitor its next quarterly disclosure for Smashburger same-store sales, restaurant-level margin, unit closures/openings, and franchise mix before assigning any earnings impact.
- Use October-November restaurant traffic data as a sector read: if fast-casual traffic weakens while value QSR holds, favor long MCD or QSR versus short a higher-multiple fast-casual basket; reassess if fast-casual comparable sales outperform value QSR by more than 200 bps.
- Set an alert for JFC guidance revisions or disclosure of sustained Smashburger comparable-sales growth above mid-single digits with stable food and labor margins; that combination would be a more credible trigger to revisit the parent-company thesis.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Why is Nidec stock plunging today?
- Nidec Corp shares slump after auditor declines to sign off on earnings
- We're raising our Micron price target after an incredible quarter and robust guidance
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data