
Micron: A Top AI Chip Stock With Potential To Double On HBM Demand
Source: seekingalpha.com
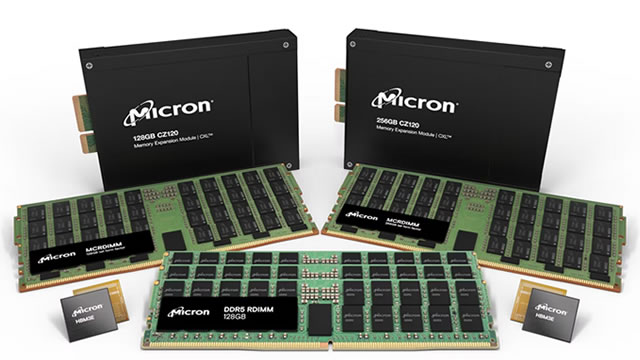
Micron delivered record Q4 results, exceeding revenue and EPS expectations as AI data-center demand boosted high-bandwidth memory sales. Structural HBM and DRAM supply shortages and higher average selling prices are expanding gross margins, while favorable AI capital-expenditure trends support an upside-skewed outlook. The analyst maintains a Strong Buy rating on expectations for explosive revenue and gross-profit growth.
Analysis
The market should treat MU less as a generic memory-cycle recovery and more as a constrained AI-infrastructure supplier, but the key debate is duration of HBM scarcity versus the speed of Samsung and SK hynix qualification. Near-term earnings leverage is unusually high: incremental HBM mix raises both bit-value and gross-margin capture, while conventional DRAM/NAND pricing provides a cyclical floor. The second-order beneficiary is ASML and selected wafer-fab equipment suppliers with memory exposure (LRCX, KLAC), although MU's capex discipline would limit the upside for broad equipment baskets.
Over the next 1-3 months, the catalyst path is hyperscaler AI-capex commentary, Nvidia platform shipment visibility, and evidence that HBM allocation remains tight into 2027. The principal risk is not a demand collapse but accelerated supply response: a faster-than-expected HBM3E/HBM4 qualification ramp from Samsung would reduce pricing power before reported volumes weaken. A weaker conventional-memory pricing environment, especially NAND, could also obscure HBM-driven margin expansion and cause MU's multiple to compress despite continued earnings growth.
Consensus is likely underestimating the volatility embedded in a stock that is now priced on forward AI-memory margins rather than trough-cycle normalization. The bull case requires sustained premium mix; if HBM revenue grows but gross margin stalls, the market will interpret that as competitive erosion. For a 6-18 month horizon, HBM4 content growth and increasing memory per accelerator support a structurally higher earnings base, but this should be sized as a high-beta semiconductor exposure rather than a defensive AI holding.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.78
Ticker Sentiment
Key Decisions for Investors
- Maintain/add MU on pullbacks rather than chase post-results strength; target a 6-12 month holding period, with the thesis anchored to sequential gross-margin expansion and continued HBM allocation tightness. Reassess if management indicates HBM pricing normalization or inventory rebuilding before 2027.
- Express the relative-value view via long MU / short SOXX or SMH in equal beta-adjusted dollars over 1-3 months: MU should outperform if AI-memory mix continues to lift earnings revisions, while the hedge reduces broad AI-capex and valuation risk. Exit if Samsung qualification materially narrows HBM supply constraints.
- For upside participation with defined risk, consider 6-9 month MU call spreads only after implied volatility normalizes following earnings. The trade requires confirmation from the next hyperscaler and Nvidia demand updates; absent that evidence, do not pay elevated post-event vol.
- Monitor Samsung Electronics and SK hynix HBM qualification, DRAM contract-price data, and MU's quarterly gross-margin guide as falsification signals. A meaningful sequential margin miss or conventional DRAM price reversal would warrant reducing exposure even if AI unit demand remains strong.
More News
- Stocks remain under the thrall of higher yields and higher oil. Here's what's ahead
- Nasdaq Index: Record High as Weak Payrolls Cut Rate-Hike Bets and Yields Fall
- Nvidia is a 'best in breed' stock on sale. Here's why I'm buying
- Micron sees the memory shortage tightening into 2028 after a record quarter
- CLSA raises Micron stock price target on strong memory pricing outlook
- Wall Street sets Micron (MU) stock price for 12 months
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?