
Sunshine Silver Mining & Refining Completes 50,000-Meter Infill Drill Program with High-Grade Results Exceeding 1,000 Grams per Tonne Silver Across Multiple Veins
Source: PR Newswire
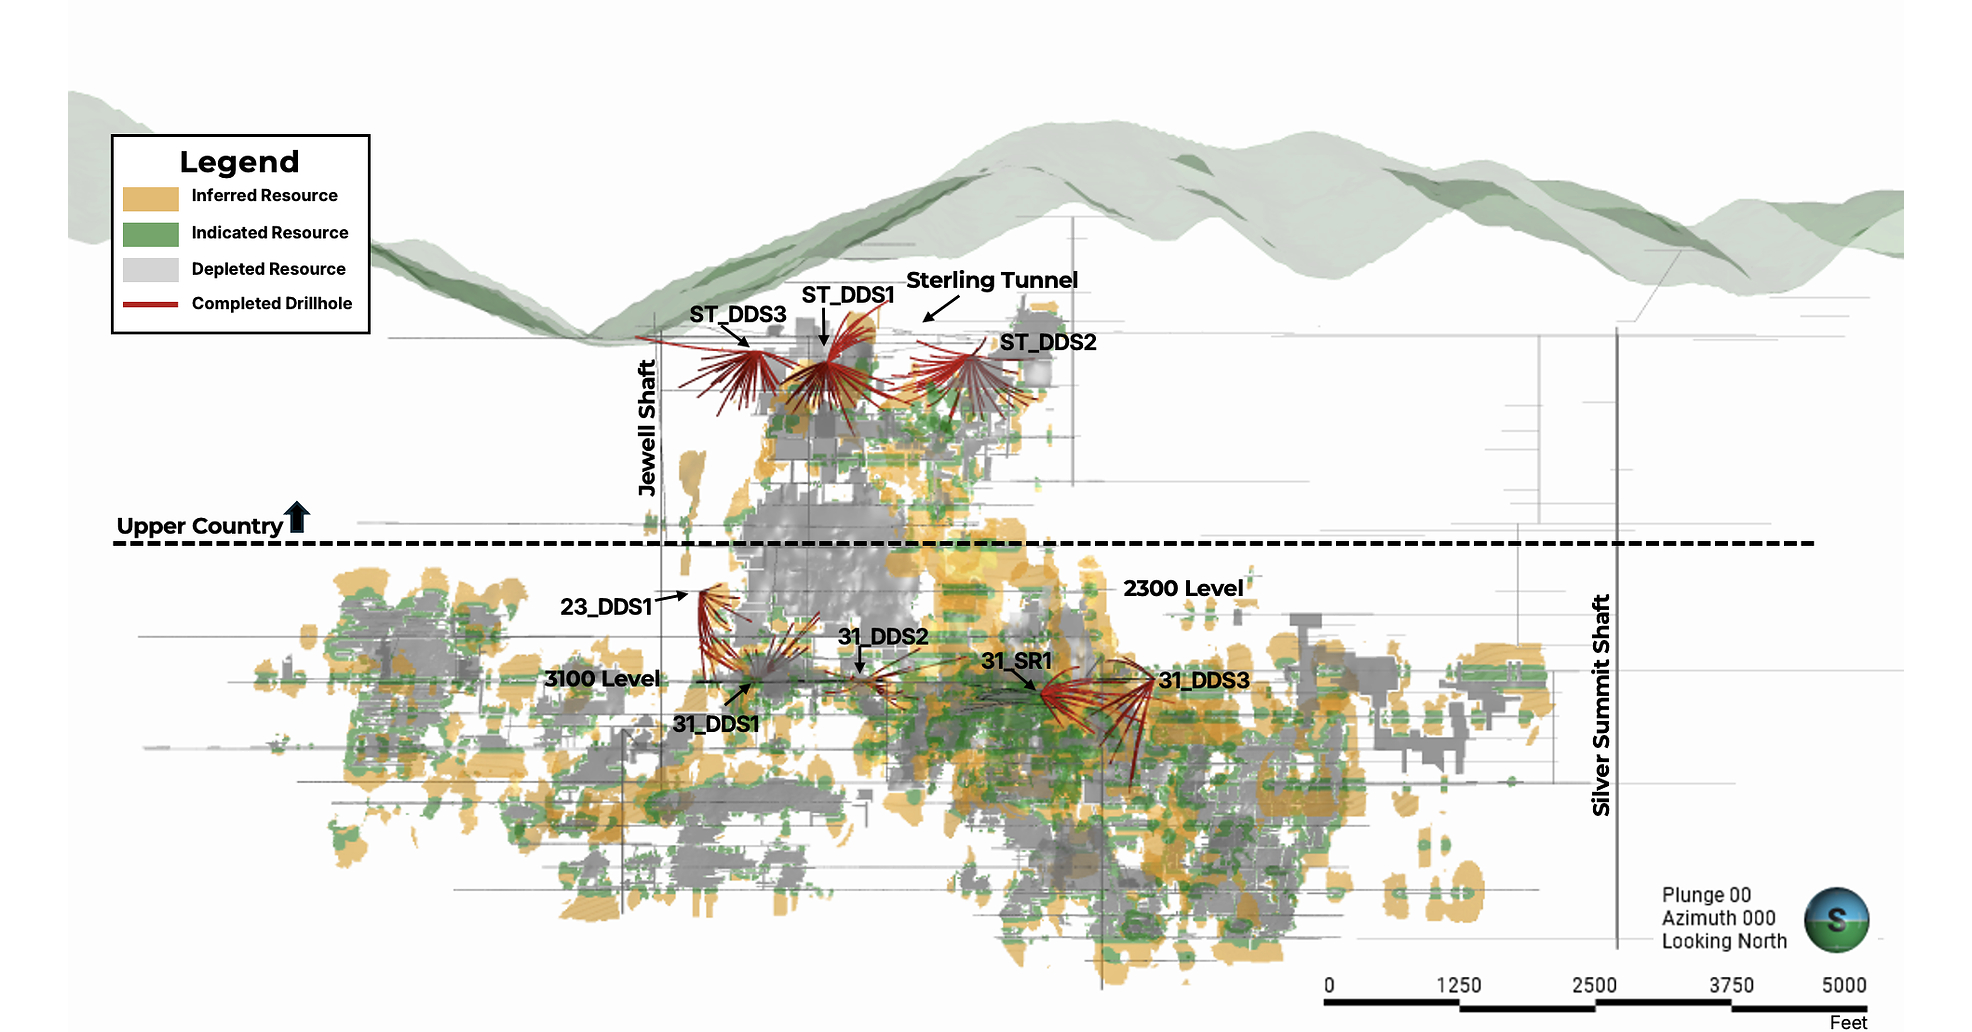
Sunshine Silver completed its 50,000-meter infill drill program at Idaho’s Sunshine Mine, reporting multiple high-grade silver intercepts, including 7,069 gpt over 1.00 meter and 18,103 gpt over 0.26 meter. Results will inform an updated Mineral Resource Estimate targeted for Q1 2027 and a feasibility study targeted for Q2 2027; the company plans a late-2028 return to production. Its Initial Assessment estimates average production of approximately 6.7 million ounces of silver annually in the first five years at about 1,000 tons per day, but the timeline and production estimates remain subject to technical and other risks.
Analysis
The signal is a reduction in geological uncertainty, not proof of a financeable mine. Infill data may improve resource confidence and the 2027 study’s mine-plan basis, but headline intercepts do not resolve whether narrow veins can be mined at planned dilution, recovery and throughput—or at acceptable capital intensity. The stated production case remains preliminary, includes Inferred Resources, and has no declared Mineral Reserves. This distinction matters: investors may capitalize the resource upgrade before the feasibility study establishes conversion and economics.
Near term, SSMR could see event-driven interest as the MRE approaches; absent valuation, liquidity and financing data, we cannot judge whether that optionality is already reflected. Over 1–3 months, the key verification is whether the MRE upgrades material tonnage in the initial mine-plan area, not simply whether spectacular grades recur. The Q2 2027 feasibility study is the more consequential catalyst for capex, mine schedule and financing risk. A late-2028 start leaves substantial execution and potential dilution risk over the 6–18 month horizon. Antimony adds strategic optionality, but no standalone production or earnings contribution is quantified here.
Contrarian point: exceptionally high grades can distract from narrow-width mining complexity. If dilution, development costs or funding needs disappoint, a resource-driven rerating could reverse even with strong assays. Conversely, a credible reserve conversion and financeable study could narrow the gap between geological promise and producer valuation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- Treat SSMR as a milestone-driven developer exposure, not as near-term silver production. Avoid extrapolating reported grades directly into output or cash flow.
- Watch the Q1 2027 MRE for conversion and mine-plan-area tonnage, and the Q2 feasibility study for reserves, dilution assumptions, capex, recovery, schedule and funding requirements. These are the data needed before sizing a directional position.
- If seeking tactical exposure, consider only a small, event-risk-sized SSMR position ahead of the MRE; do not chase assay headlines without checking the share-price reaction, liquidity and financing disclosures. A resource upgrade that fails to improve mine-plan economics would falsify the positive setup.
- Reassess or exit the thesis if the MRE misses timing or fails to upgrade relevant material, or if feasibility economics require materially higher capital or defer the targeted schedule. A credible, financeable study with reserve conversion would strengthen the longer-term case.
More News
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- AI stocks plunge after election, driving down US markets
- Iran says tankers struck in Hormuz amid fears of new US attack
- The Iran war has cost U.S. households nearly $2,000 each. New strikes could keep the bill climbing
- Qualcomm slides 9% after earnings, leading post-election chip stock sell-off