
Mitsubishi Motors Reports Third Quarter 2026 Sales
Source: PR Newswire
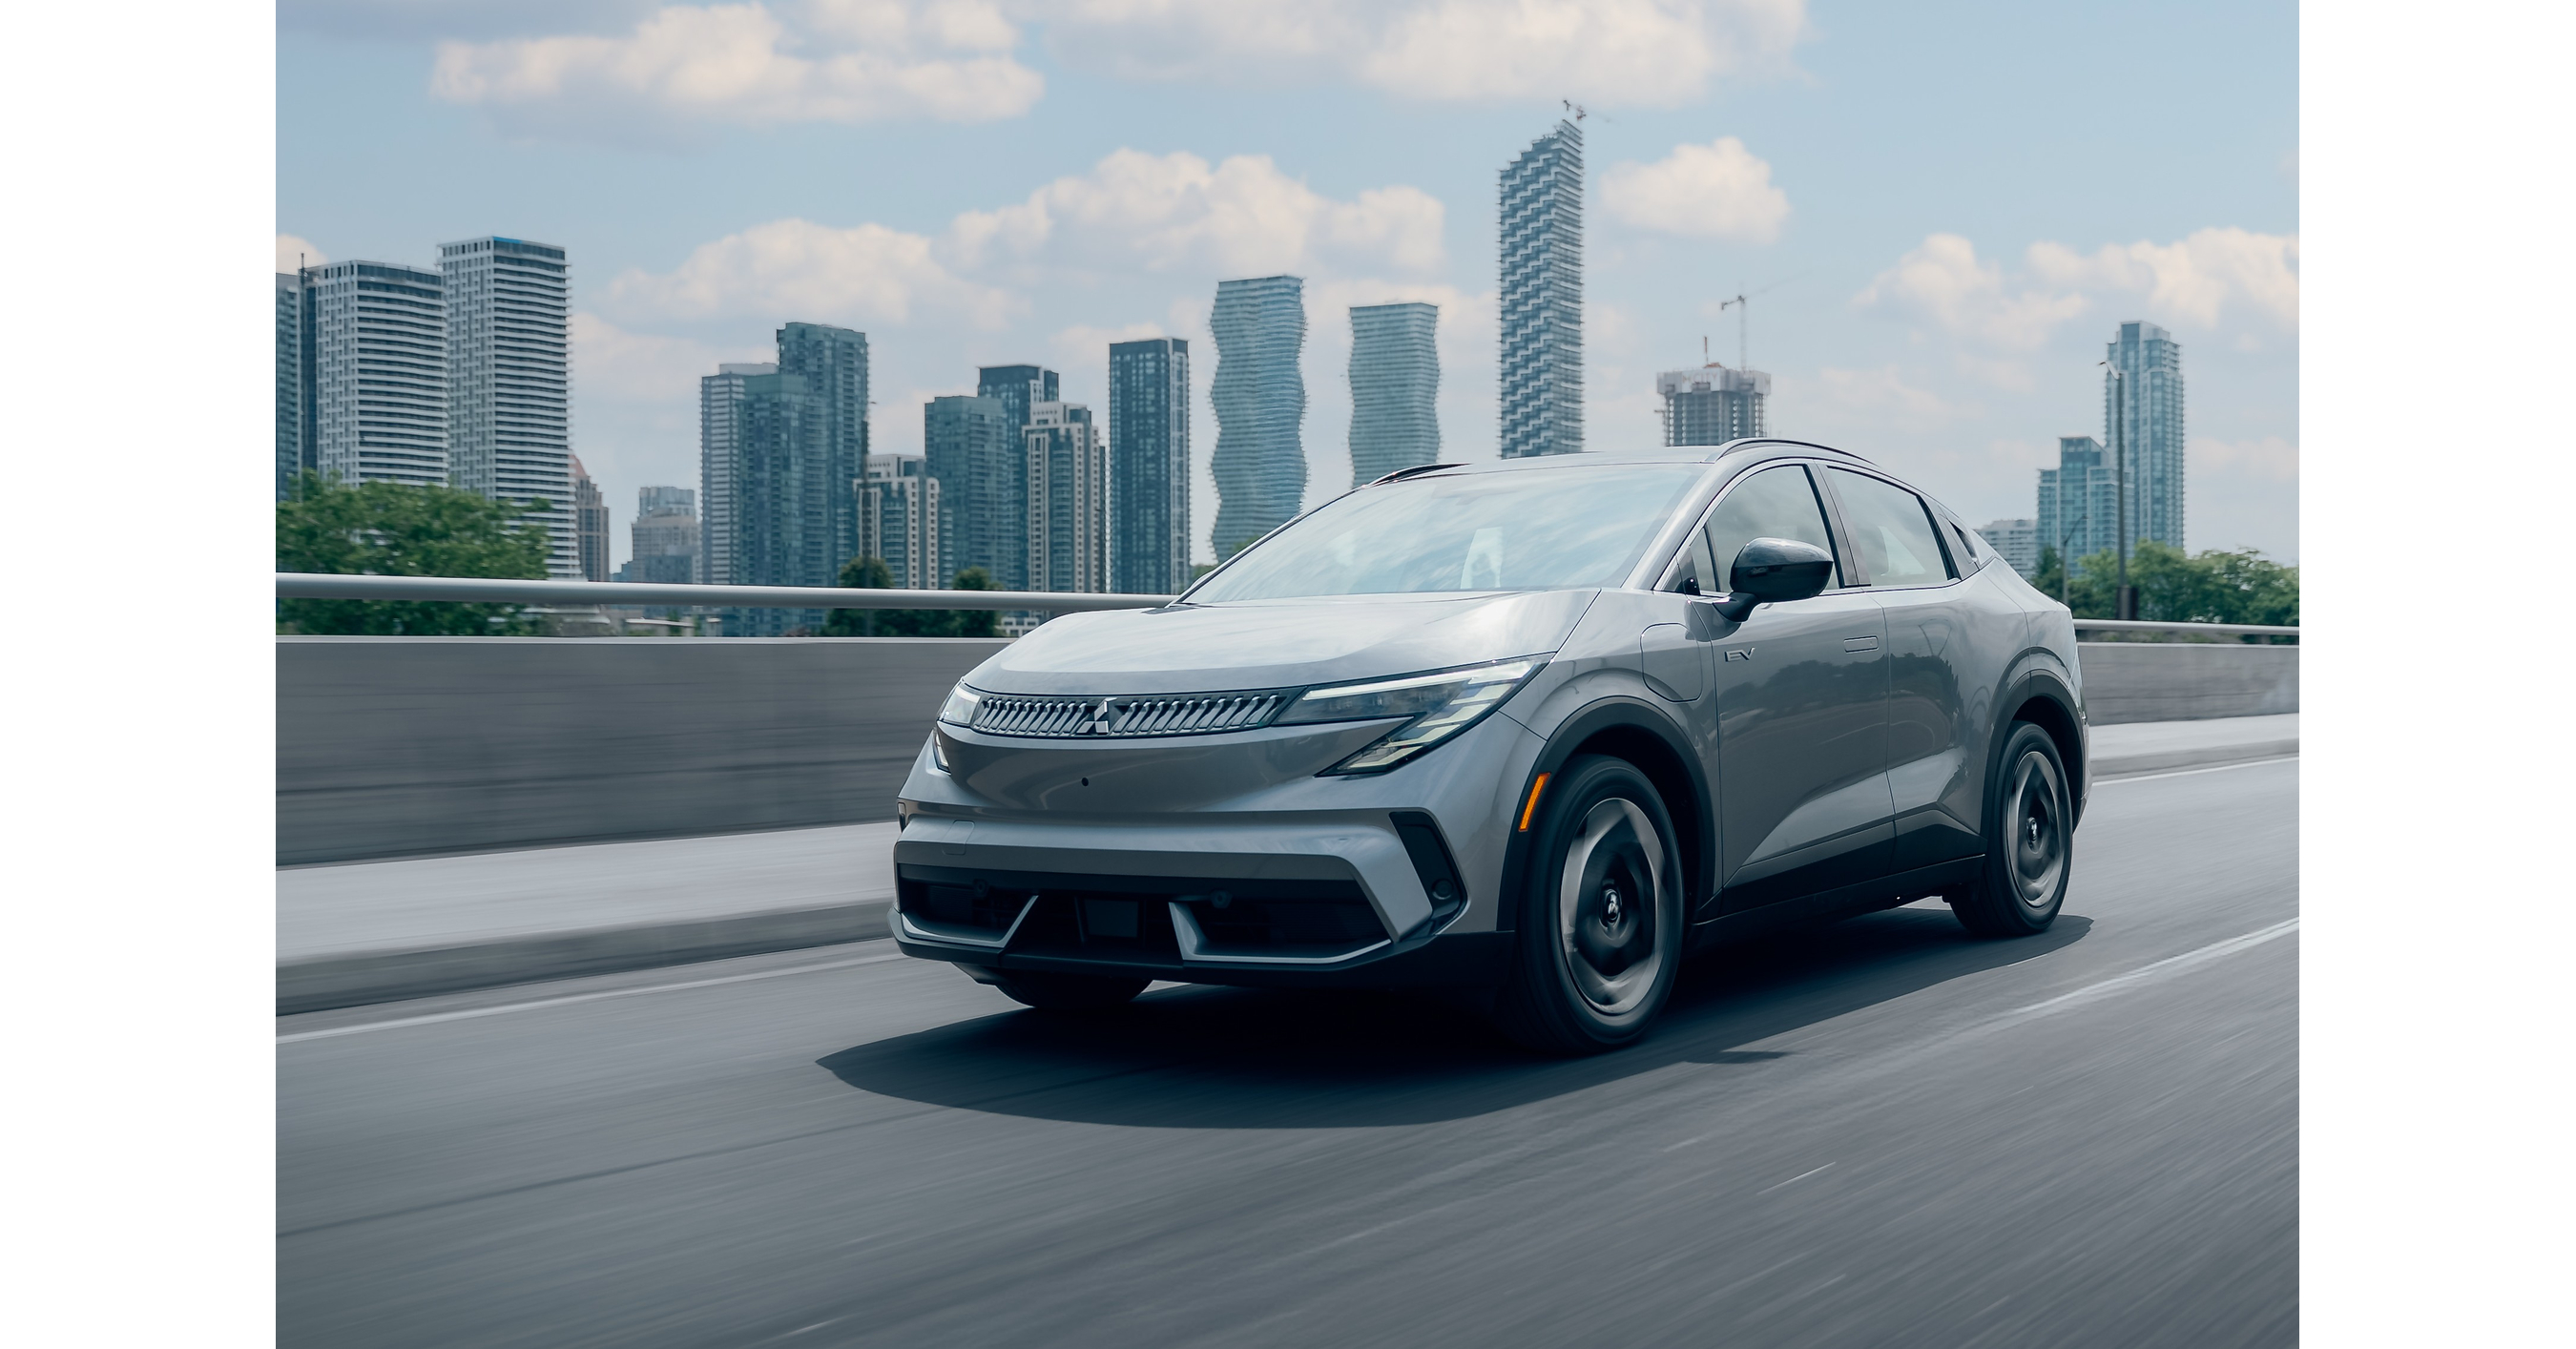
Mitsubishi Motors North America reported Q3 2026 U.S. sales of 18,543 vehicles, down 5.6% year over year as the planned Mirage/Mirage G4 discontinuation removed more than 14% of prior-year quarterly volume. SUV sales rose nearly 10%, led by Outlander at 9,311 units (+27.1%) and Outlander Sport at 5,902 (+91.6%), replacing more than 60% of lost Mirage volume. The company is advancing its Momentum 2030 renewal plan with a refreshed Outlander PHEV, the Eclipse Sportback EV, a rugged Outlander variant in Q1 2027, and a planned midsize pickup collaboration with Nissan.
Analysis
The relevant signal is mix quality, not unit growth: Mitsubishi is replacing a discontinued low-price nameplate with SUVs, which should lift revenue per vehicle and dealer gross profit if incentives remain controlled. But the sharp divergence between strong entry-SUV volumes and weak plug-in hybrid demand implies the brand is winning primarily through affordability and availability rather than technology-led pricing power; this limits the read-through to EV valuation multiples and leaves margins vulnerable if sub-$30k competitors intensify incentives.
For 1-3 months, the highest-value datapoint is dealer inventory days and incentive spending on Outlander Sport and Outlander, neither disclosed in the release. If volume gains are inventory-fed, residual values and dealer profitability could deteriorate before reported retail sales do. The planned BEV and pickup additions create a 6-18 month strategic upside for Mitsubishi Motors (7211 JP), but also raise launch, battery-sourcing, and U.S. dealer-capex requirements at a time when affordable-EV demand remains uncertain.
Nissan (7201 JP) is the more actionable second-order beneficiary: a shared midsize pickup can improve plant utilization, procurement scale, and R&D absorption, while Mitsubishi contributes a dealer channel with limited overlap in value-oriented SUV buyers. Conversely, Toyota (TM), Honda (HMC), Hyundai/Kia and Subaru face only localized pressure in entry SUVs; Mitsubishi's U.S. scale is still insufficient to move industry pricing absent sustained dealer-network expansion. The contrarian view is that a broader lineup may increase fixed costs faster than throughput, making execution and incentive discipline—not product cadence—the binding constraint.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Key Decisions for Investors
- No standalone U.S. auto trade from this release; wait for October/November incentive data, dealer inventory days, and 7211 JP guidance before treating sales momentum as an earnings catalyst.
- Place a 1-3 month watch on long 7201 JP versus short HMC: initiate only if Nissan confirms pickup-program cost sharing or raises North American utilization guidance. Target 8-12% relative upside; exit if Nissan's North American incentive-to-GAAP-revenue ratio worsens or production guidance falls.
- For 7211 JP, treat the upcoming BEV launch as an event-risk setup rather than a pre-launch long. Consider a small long only after disclosed order conversion, transaction pricing, and battery sourcing demonstrate positive gross-margin potential; falsification is incentive-led sales growth with dealer inventories above 75 days.
- Monitor used-vehicle residual values and incentive activity for Outlander/Outlander Sport over the next two quarters. A widening incentive gap versus TM, HMC, or Subaru would be an early signal to avoid Japanese value-auto exposure rather than evidence of sustainable share gains.
More News
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- One of our most recent defensive buys cleared a hurdle and its stock jumped
- Iran says it receives US response to latest proposal as Washington pulls out of Iraq
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search