
GOFO Highlights Shifts in U.S. Parcel Delivery at PARCEL Forum 2026, Releases New Industry White Paper
Source: PR Newswire
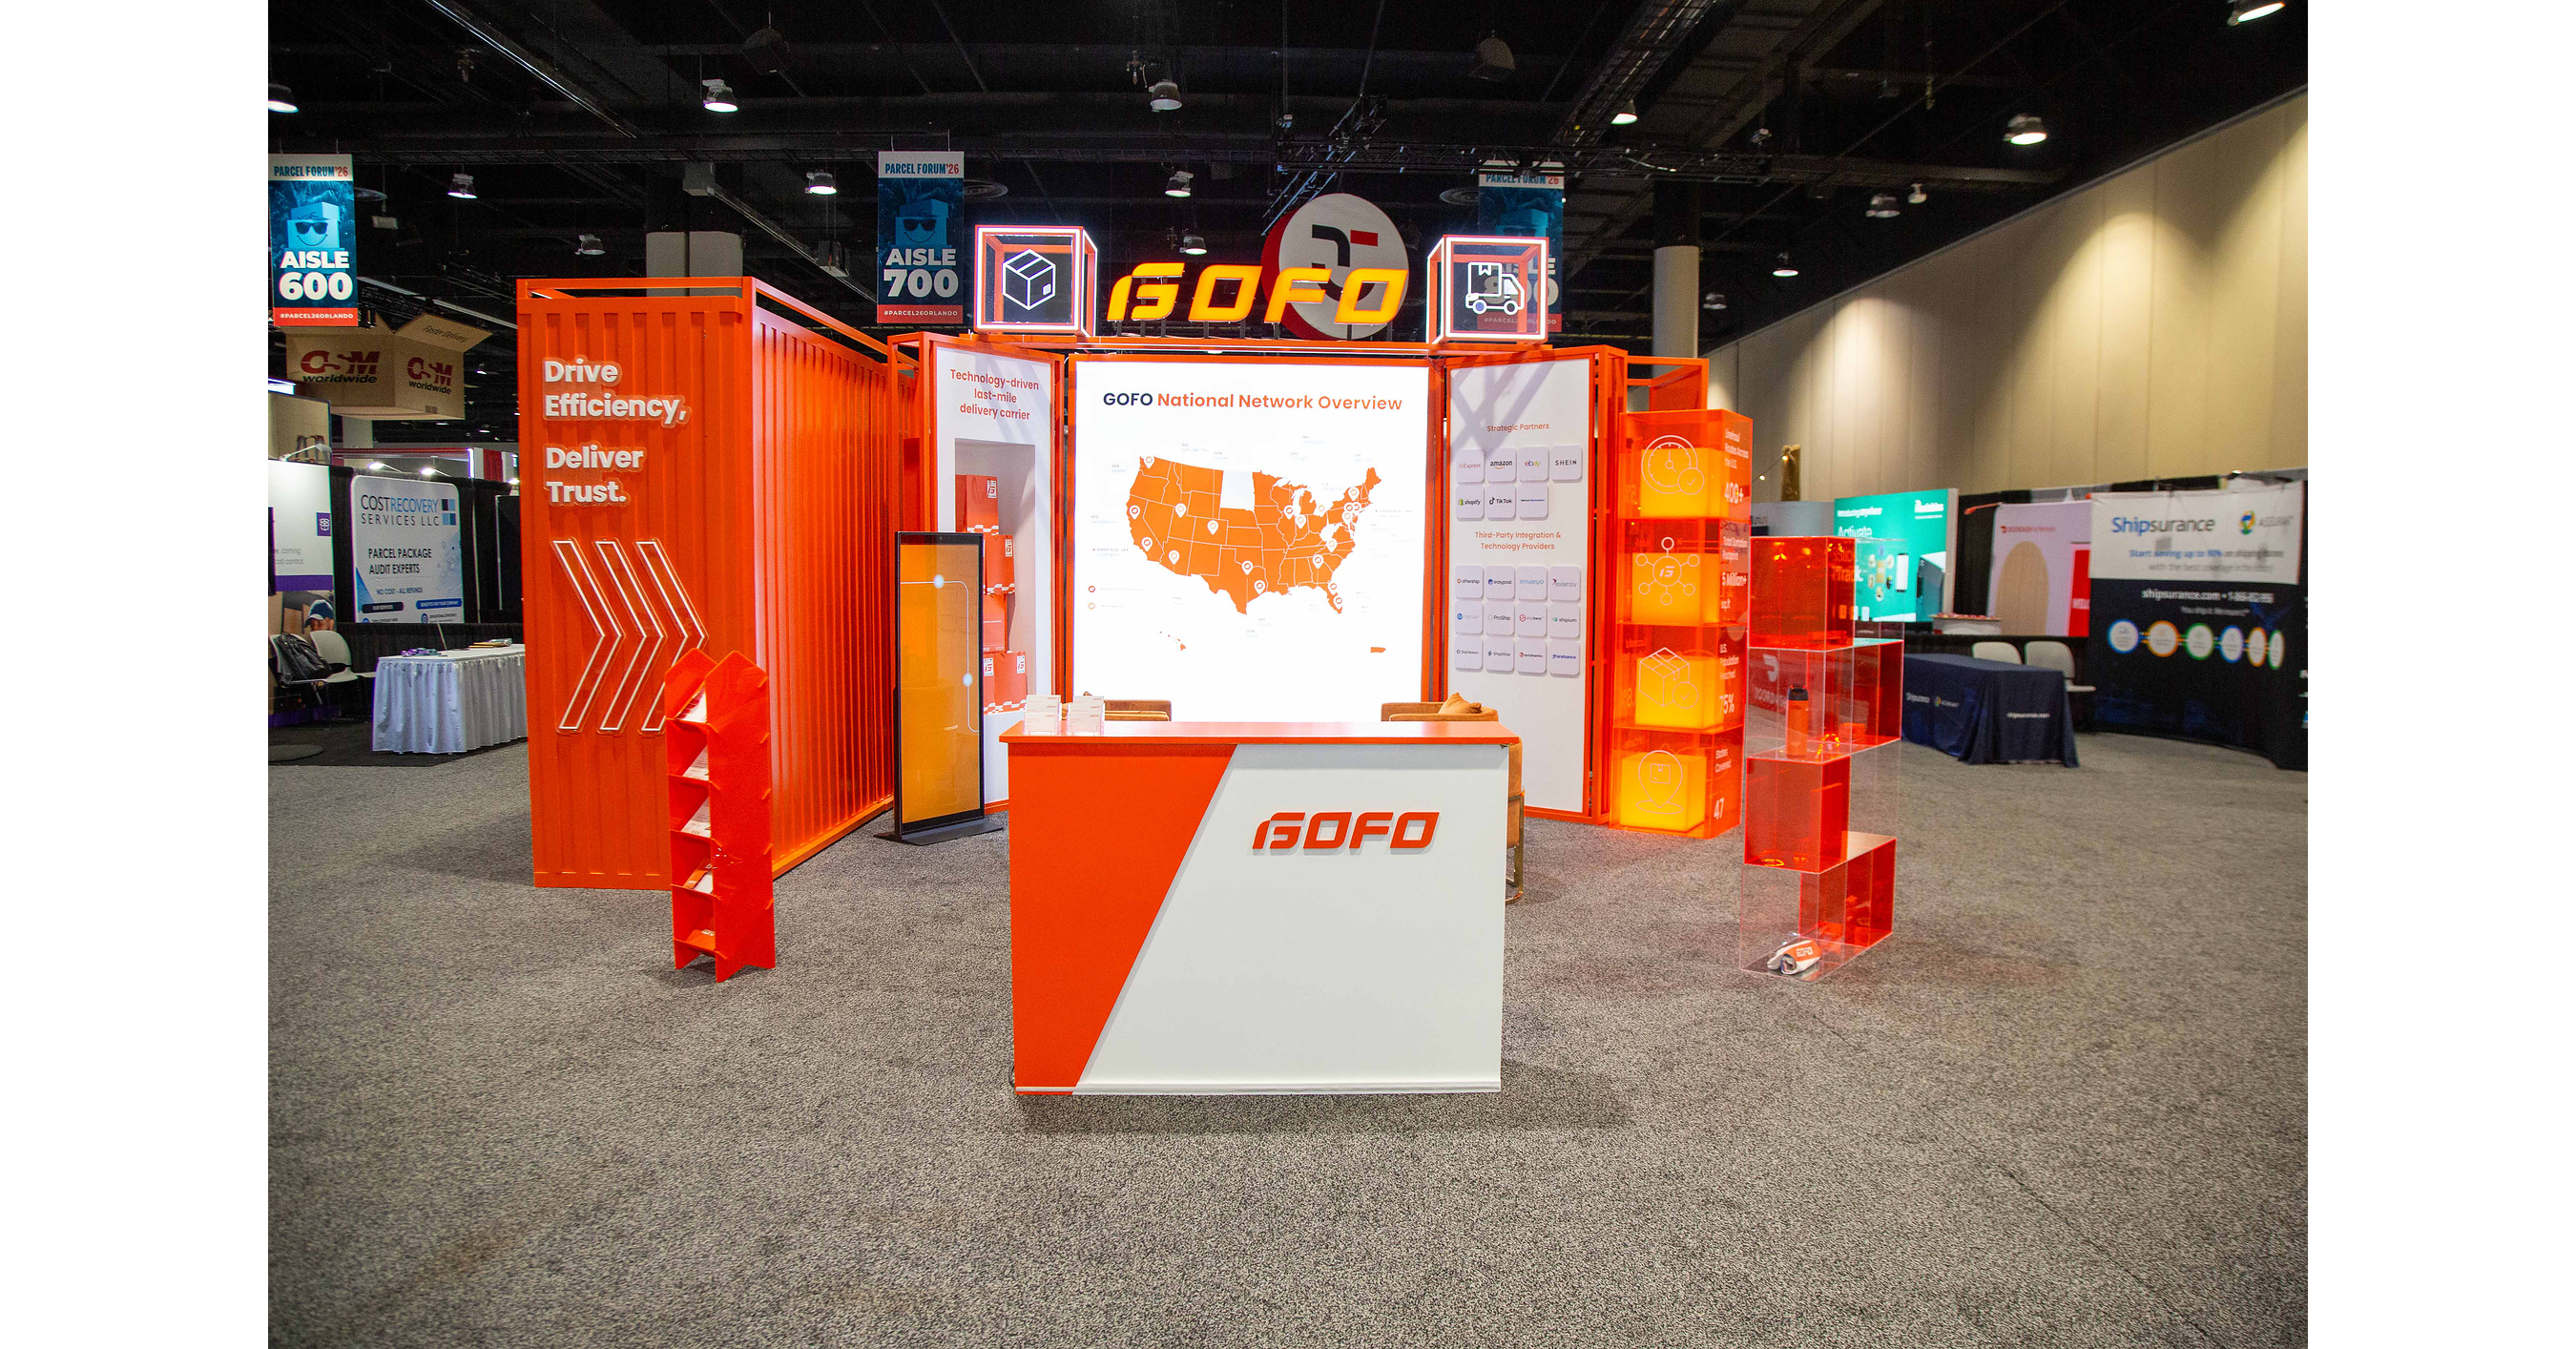
GOFO's 2026 white paper highlights a diversifying U.S. parcel market, with domestic volume reaching 23.9 billion packages in 2025 and alternative carriers handling roughly 2.5 billion packages, up about 13% year over year. UPS, FedEx and USPS accounted for approximately 61% of volume, indicating growing room for regional and next-generation delivery providers. GOFO positioned its automated routing, sortation and localized operations as tools for shippers navigating more fragmented e-commerce fulfillment needs.
Analysis
The investable implication is modest share and pricing pressure at the margin for UPS and FDX, not an immediate volume shock. Alternative carriers are most disruptive in dense, repeatable lanes where they can underprice national networks while avoiding their rural-service burden; that selectively weakens the carriers' ability to use peak surcharges and minimums to offset fixed-cost inflation. The relevant 1-3 month datapoints are domestic package yield, volume by service tier, and management commentary on customer mix rather than industry parcel-volume headlines.
WMT is better positioned than the public carriers because parcel-network fragmentation increases the value of its store proximity, fulfillment density and marketplace control. If merchants can use multiple delivery providers through WMT Fulfillment Services, WMT can improve seller acquisition and monetize logistics capabilities without bearing a fully national standalone-carrier cost structure. Over 6-18 months, the greater strategic risk is to UPS/FDX's small- and medium-business economics, where service reliability and integrated network breadth have historically supported pricing premiums.
The contrarian view is that regional-carrier growth does not necessarily translate into durable public-carrier share loss. Fragmented networks create integration, claims-management and exception-handling costs; UPS and FDX retain a structural advantage for nationwide, low-density, high-value and complex shipments. A broad parcel-demand rebound or evidence that alternative-carrier growth is concentrated in low-yield marketplace imports would be positive for UPS/FDX margins, because the displaced mix may be economically unattractive business they are willing to cede.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Maintain a 1-3 month relative underweight in UPS versus the Dow/transportation basket; add only if UPS reports domestic package revenue-per-piece deterioration or weaker-than-seasonal peak pricing. Cover the underweight if management reaffirms yield growth and operating-margin recovery despite competitive diversion.
- Prefer long WMT / short FDX as a 6-12 month pair, sized modestly: WMT has optionality from marketplace and fulfillment-density gains, while FDX has greater exposure to competitive domestic parcel pricing. Thesis fails if FDX demonstrates sustained Ground yield expansion and cost savings sufficient to offset mix pressure, or WMT logistics investment materially worsens retail margins.
- Do not initiate a directional trade solely on this release. Set alerts around UPS and FDX quarterly disclosures for SMB volume, deferred/ground yield, peak surcharge realization, and customer churn; those are the missing verifiable inputs needed to convert the fragmentation narrative into an earnings estimate change.
- Watch WMT Fulfillment Services seller-growth and fulfillment-margin disclosures over the next two earnings cycles. Evidence of accelerating marketplace adoption without incremental fulfillment-cost deleverage would support increasing the WMT leg; slowing seller growth or delivery-cost inflation would remove the relative catalyst.
More News
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Meta nears first new high in a year as Muse success showcases winning AI strategy
- Meta's Muse agent has the potential to dominate the AI space, says JPMorgan
- The return of nostalgia is bringing back Toys “R” Us as it opens 120 stores, nine years after bankruptcy
- Amazon Blocks Meta's Muse. It Could Be a Gift for Walmart and Shopify
- BofA Securities reiterates Buy on Meta stock, $810 price target