
Moldova eGovernance Agency Launches Banking Use of EVO Digital Identity Credentials Built to European Standards
Source: PR Newswire
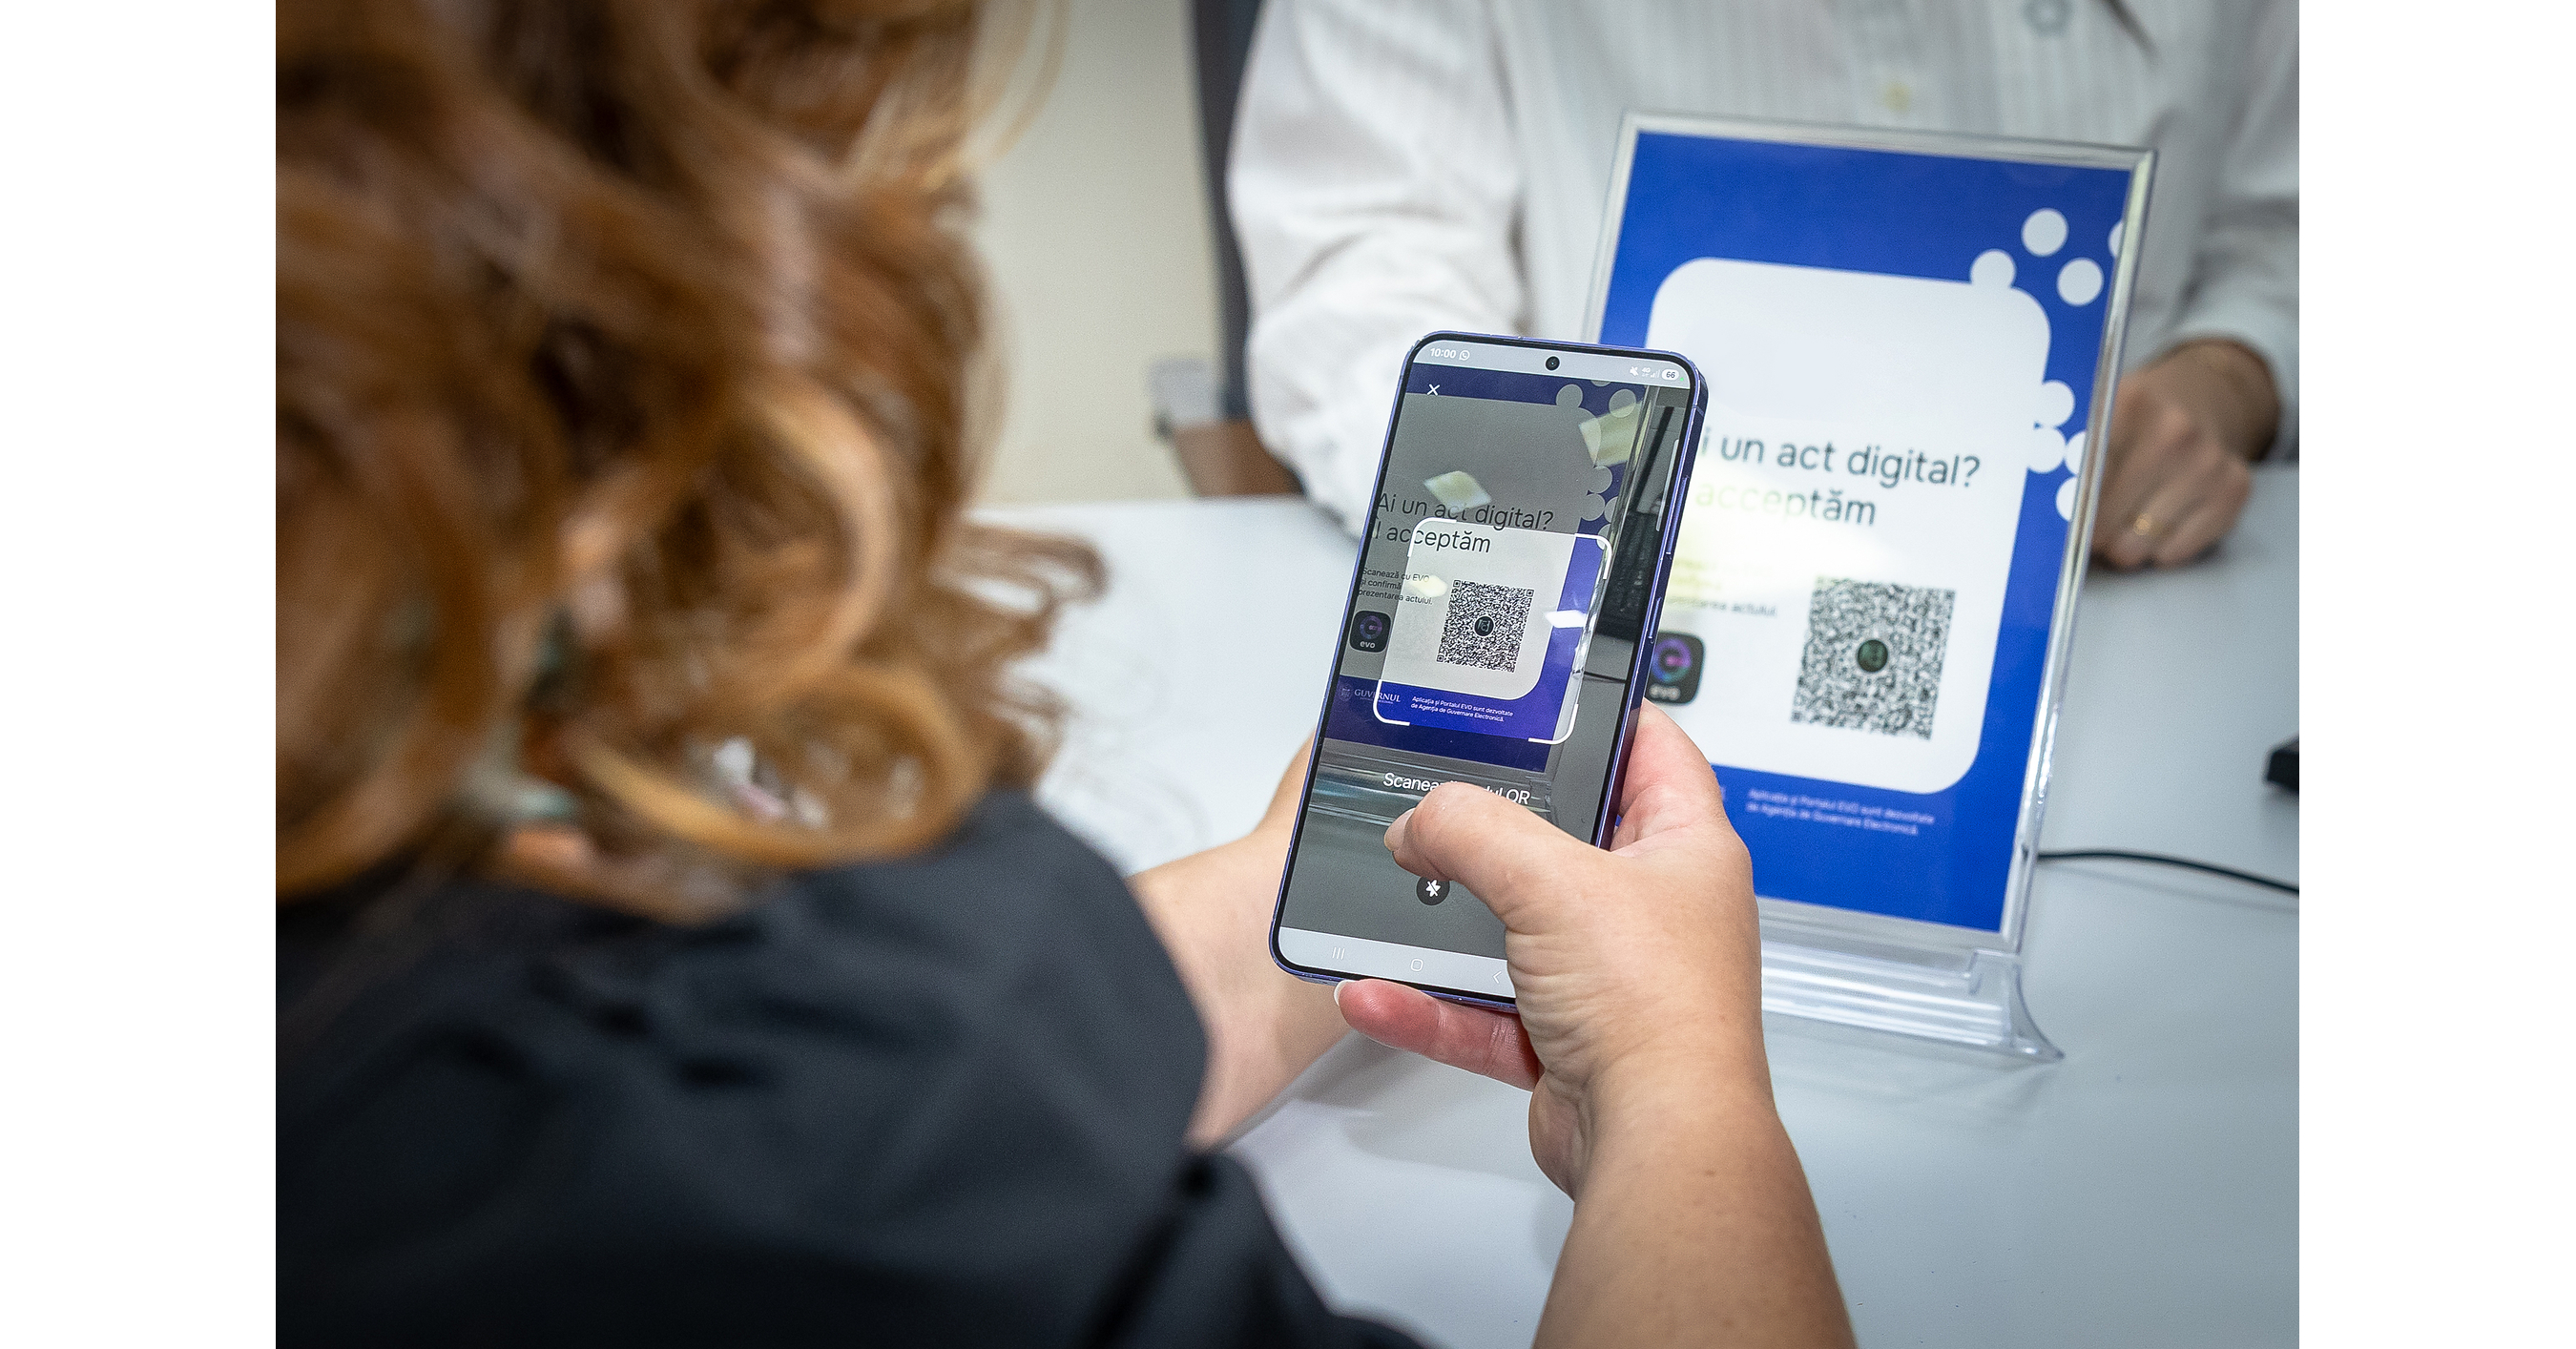
Moldova's EVO digital identity credentials are now accepted by four banks—Moldindconbank, FinComBank, EuroCreditBank and Victoriabank—enabling QR-based, consent-driven digital customer identification. Since private- and public-sector integrations opened on April 1, 2026, 30 relying parties have entered the pipeline, with at least 20 expected to be operational by year-end. EVO is being developed to European Digital Identity Wallet standards, supporting eventual cross-border interoperability as Moldova advances its EU-alignment agenda.
Analysis
This is not a direct earnings catalyst for NBHC: its operating footprint and customer base lack meaningful Moldova exposure, and the structured ticker association appears non-economic. The near-term read-through is therefore neutral for listed U.S. banks; domestic digital-ID adoption in a small market will not alter sector loan growth, deposit pricing, or payment volumes.
The more relevant second-order implication is validation of the European Digital Identity Wallet architecture as a bank onboarding rail. Over 6-18 months, wider interoperability could lower KYC refresh and account-opening friction for European banks while pressuring incumbent identity-verification vendors whose pricing depends on document review and fragmented national workflows. That outcome remains contingent on relying-party adoption, liability allocation for credential errors, AML acceptance, and cross-border regulatory recognition—not on pilot integrations alone.
Consensus should avoid extrapolating a government-led rollout into immediate fintech monetization. Digital-identity projects often show rapid credential issuance but slow transaction density, because banks retain duplicate compliance controls until audit histories and supervisory guidance establish a defensible liability framework. The investable signal would emerge only if large EU banks disclose measurable reductions in onboarding cost, fraud losses, or account-opening time during 2027 planning cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No position in NBHC on this development; treat the ticker linkage as non-actionable absent evidence of a European payments, identity, or correspondent-banking revenue exposure.
- Monitor EU-listed bank disclosures through the next 6-12 months for digital-wallet-driven KYC cost reductions or onboarding conversion gains; a verified, scaled cost-save would be more relevant to banks with cross-border retail franchises than to U.S. regional-bank exposures.
- Keep identity-verification vendors on a watchlist rather than shorting: a credible risk signal would be EU wallet mandates paired with bank migration away from paid document-verification workflows. Falsification is persistent parallel KYC processes and no disclosed reduction in vendor spend through 2027.
- For fintech exposure, require evidence that credential transactions—not merely integrations—are scaling: milestones should include active relying parties, repeat monthly credential use, and regulator-approved AML reliance. Without those data, the risk/reward is insufficient for a thematic position.
More News
- What is BRICS Pay, and can it rival the West’s SWIFT payments system?
- Fed hikes again - an AI-Picked insurer is still cashing in
- Congress passes sweeping US sanctions bill targeting Russia
- US official says upcoming spectrum auctions could generate more than $100 billion
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- Analysis: How Trump could reignite the Fed independence fight after Warsh's rate hike