
FF EAI Robotics Ecosystem Signs Definitive Agreements to Combine FFAI's Full Robotics Business at About $200 Million and $2.246 Per Share, an Approximate 50 Percent Premium; Becoming the First U.S.-Listed Humanoid and Bionic EAI Robotics Pure Play
Source: PR Newswire
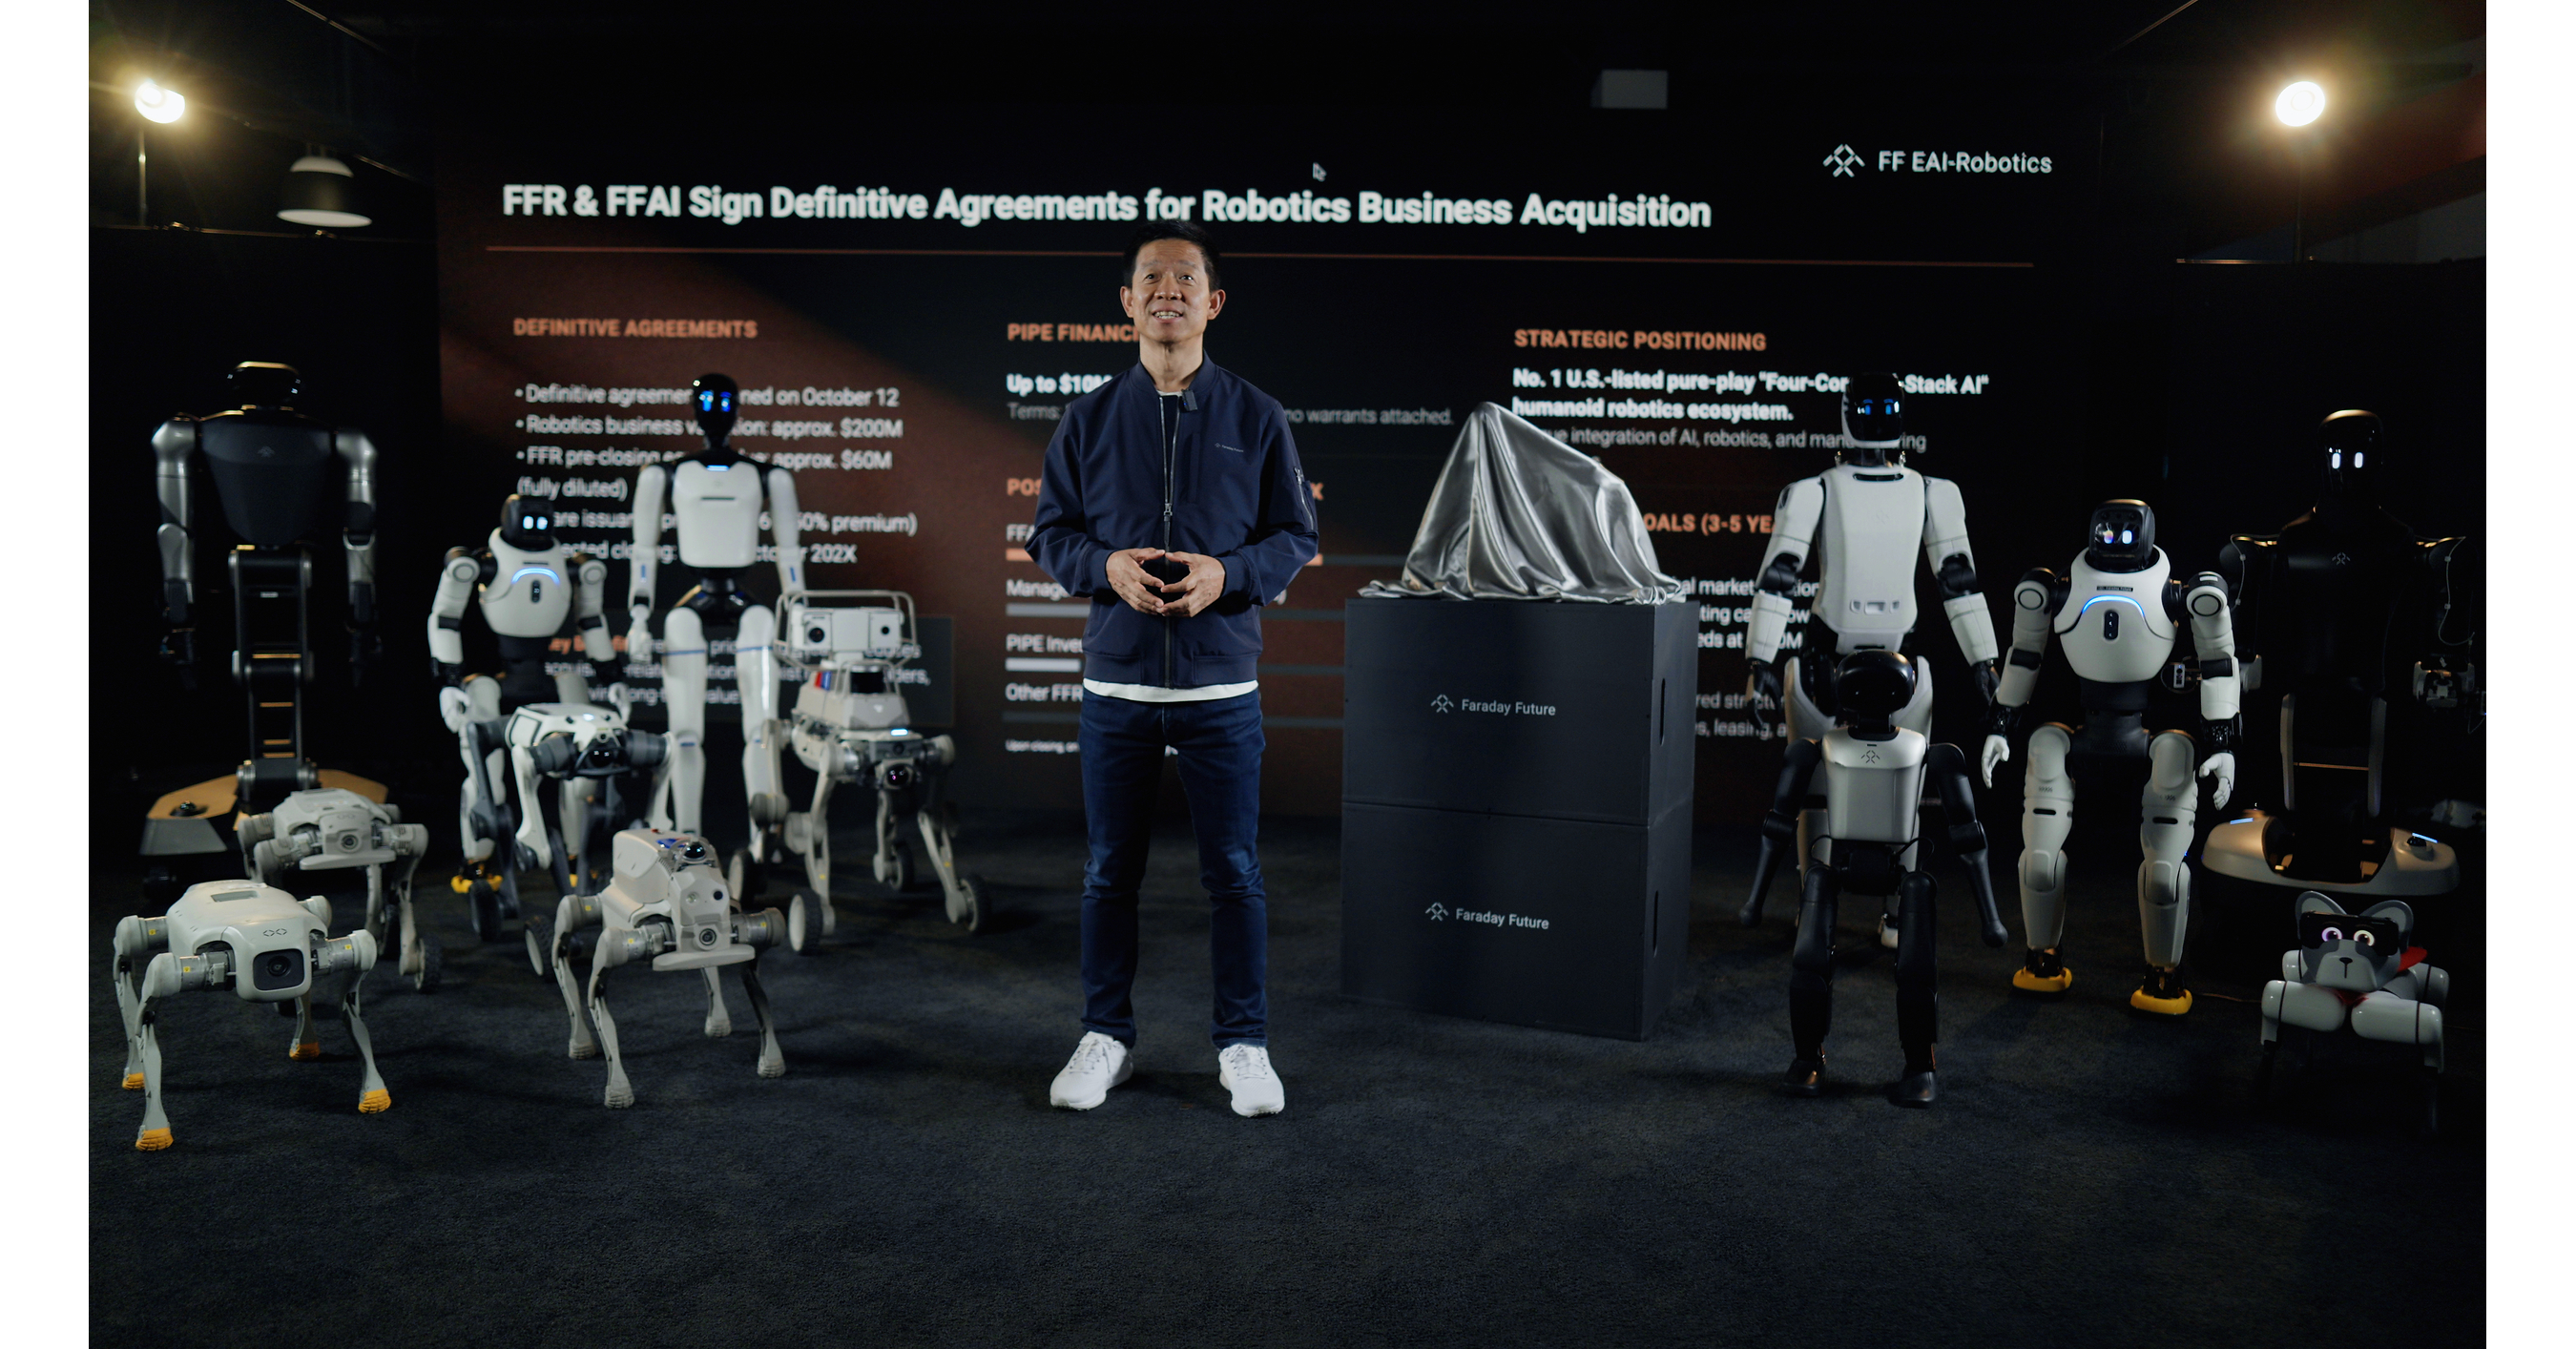
FFR signed definitive agreements to acquire FFAI’s robotics business at an approximately $200 million valuation in an all-stock deal, with shares issued at $2.246 each—about a 50% premium to FFR’s October 12 closing price of $1.50. FFR has secured up to $10 million in PIPE financing; after closing, FFAI is projected to own 65.7% of FFR, while the freely tradable public float is estimated at 10.7%. FFAI management’s standalone projections—not adopted as FFR guidance—include $7 million of 2026 revenue, $45 million in 2027, and positive operating cash flow by Q3 2028; closing is expected by the end of October, subject to conditions and risks.
Analysis
Analysis The key market mechanism is ownership and liquidity, not the headline premium. The $2.246 issuance price is consideration agreed between related parties—not a cash redemption value or a price floor for FFR’s publicly traded shares. With a small stated public float and most shares locked or held by insiders/FFAI, FFR can gap sharply in either direction; shorting may be especially vulnerable to a squeeze, while apparent scarcity can exaggerate upside absent fundamental buying.
For FFAI, the transaction may make the robotics asset easier to value, but it does not remove execution or parent-company risk: FFAI remains the controlling holder of FFR and retains exposure to the business through that stake. Standalone projections are management-prepared, unaudited and not FFR guidance. The gap between early commercialization and the five-year revenue ambitions makes repeat orders, utilization, realized gross margins and cash consumption more informative than product-count or ecosystem claims. The stated financing plan also needs reconciliation with the actual closing capitalization and cash runway.
Timing / reversal: The immediate catalyst is closing and the final SEC/Nasdaq documentation; over 1–3 months, watch share conversion, resale registration, PIPE completion and customer revenue evidence. Over 6–18 months, unit economics and repeat deployments determine whether the software/data ecosystem can raise margins—or whether hardware scaling consumes capital. Delayed approvals, employee agreements, Nasdaq listing requirements, or weaker liquidity could reverse the narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Do not treat FFR’s agreed issuance price as downside support or chase a float-driven rally. Keep any exposure tactical and small; avoid initiating a short without confirmed borrow and liquidity, given squeeze and gap risk.
- Make closing a documentation-driven catalyst, not an assumption: verify final fully diluted share count, preferred-stock conversion and required approvals, PIPE funding, lockups/resale registration, key employee agreements, and pro forma cash/debt in SEC filings.
- Keep FFAI neutral pending a parent-level liquidity bridge. Its retained control gives it substantial indirect robotics exposure, but the transaction alone does not establish cash proceeds or resolve the parent’s funding and going-concern risks; verify asset transfers and post-close obligations.
- Upgrade only on independently verifiable repeat orders, revenue conversion and cash-burn evidence; downgrade if closing slips, financing is incomplete, listing conditions are threatened, or reported robotics economics fail to support the margin and cash-flow trajectory.
More News
- Exclusive: FFR signs definitive deal for Faraday Future’s robotics unit at $200m
- AI infrastructure stocks tumble. Here's a few reasons for the sell-off
- Traders pile into 'bubble puts' on CoreWeave as neocloud stocks plunge
- Here's the inflation breakdown for September 2026 — in one chart
- Bending Spoons Stock Soars on Berkshire’s Increased Stake
- Travis Kelce joined an activist group pushing Six Flags to consider a sale. The ‘Final Destination’-style death of a patron poured gas on the fire