
Nexomensa Expands Commercial Office Furniture Line to 100+ Products, Adds 14 U.S.-Stock Options
Source: PR Newswire
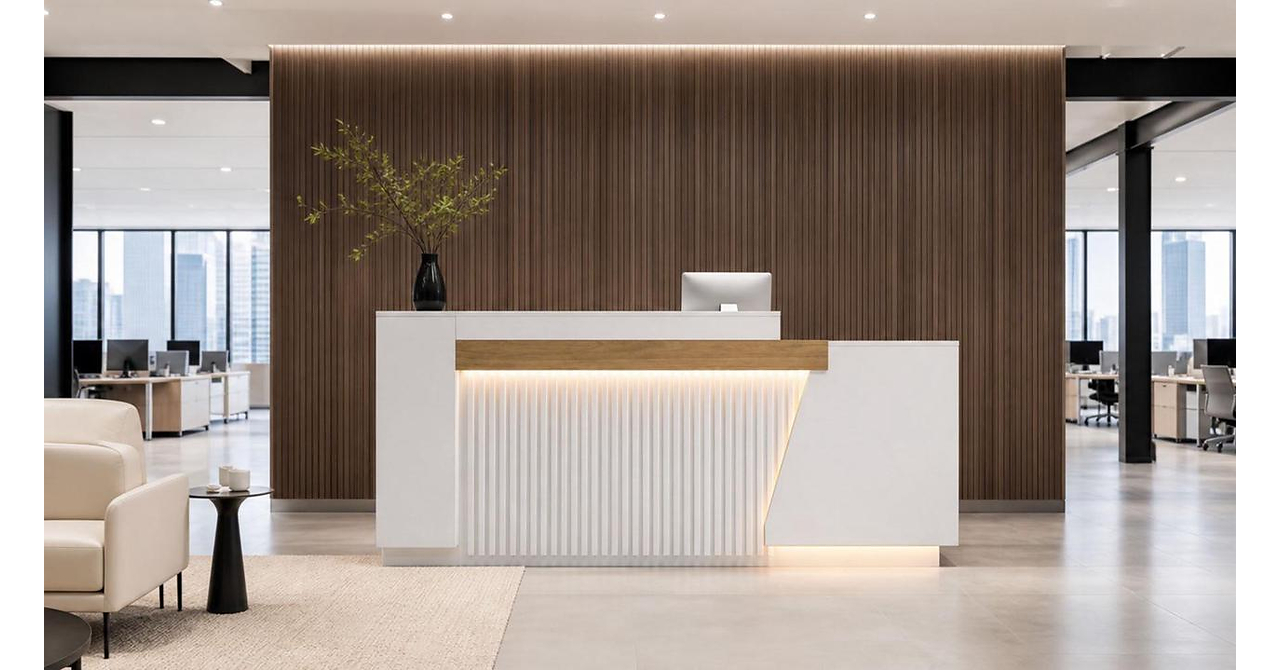
Nexomensa expanded its U.S. commercial office-furniture catalog to more than 100 products and added 14 U.S.-stock options intended to shorten fulfillment times. The lineup includes 26 executive desks, 22 reception desks, 14 office desks, 10 conference tables and 18 office chairs, alongside customization and bulk-order quotation services. The announcement is a routine product-range expansion with limited broader market implications.
Analysis
This is not independently investable information and is unlikely to alter estimates for listed office-furniture incumbents. The relevant read-through is modestly negative at the margin for fragmented contract-furniture channels: a broader imported, stocked assortment can reduce procurement friction for small and mid-sized projects, where lead time and one-stop purchasing matter more than brand specification. That pressure is most relevant to lower-end transaction volumes rather than the architect-and-designer-led enterprise contracts that support pricing for Steelcase (SCS), MillerKnoll (MLKN), and HNI (HNI).
The key unverified variable is whether U.S. inventory is meaningful enough to support reliable delivery and whether customization can be delivered without eroding gross margin. If credible, direct-to-buyer entrants could raise online price transparency and force incumbents to spend more on dealer incentives, freight absorption, and digital lead generation; this would be a margin issue before it becomes a revenue issue. Over 6-18 months, renewed office-fit-out demand would likely overwhelm this isolated competitive development, while a weaker commercial real-estate and tenant-improvement environment would make small-project share competition more acute.
Consensus should avoid extrapolating a product-count announcement into a category threat. Incumbents' defensibility lies in dealer networks, installation, warranty/service, compliance, and large-project specification—not SKU breadth. Monitor SCS, MLKN, and HNI commentary on small-business order trends, average selling prices, dealer inventory, and gross-margin guidance over the next two earnings cycles; evidence of discounting or freight pressure would validate a broader direct-import disruption thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate trade: the disclosed expansion lacks revenue, inventory, pricing, and customer-conversion data required to quantify an earnings impact on SCS, MLKN, or HNI.
- Create a 1-3 month watchlist for SCS and MLKN: investigate dealer-channel checks for lead-time compression, online/direct pricing, and small-project win rates. Consider a tactical short only if either company guides to gross-margin pressure while reporting weak order growth; absent that combination, competitive impact is likely immaterial.
- Prefer HNI over SCS/MLKN if commercial-furnishing demand improves: HNI's broader workplace and hearth exposure diversifies pure contract-office risk. Falsification: a material deterioration in workplace-segment orders or dealer inventory normalization failing to translate into margin recovery.
- For a 6-18 month office-reopening/tenant-improvement recovery thesis, use a basket approach rather than reacting to this announcement: long HNI and SCS versus a commercial-real-estate proxy only after sequential order growth turns positive. The principal risk is persistent hybrid-work-driven capex restraint, which would leave category pricing vulnerable to low-cost entrants.
More News
- Federal Reserve decision, retail sales, and oil inventories due Wednesday
- Why Dave & Buster's Stock Tumbled Today
- SpaceX will try to put Starship in orbit for the first time on September 22
- EU to Levy Fines of Up To 6% of Tech Companies’ Sales in Kids Act
- Dutch Bros CEO Christine Barone on Expansion & Inflation
- Trump’s tariffs slashed jobs and wage growth. Now companies are funneling their chunk of the $100 billion in refunds to supplement workers’ retirement