
Professional Paper Tube Manufacturer Sprintpackage Expands to 20,000 SQM Facility
Source: PR Newswire
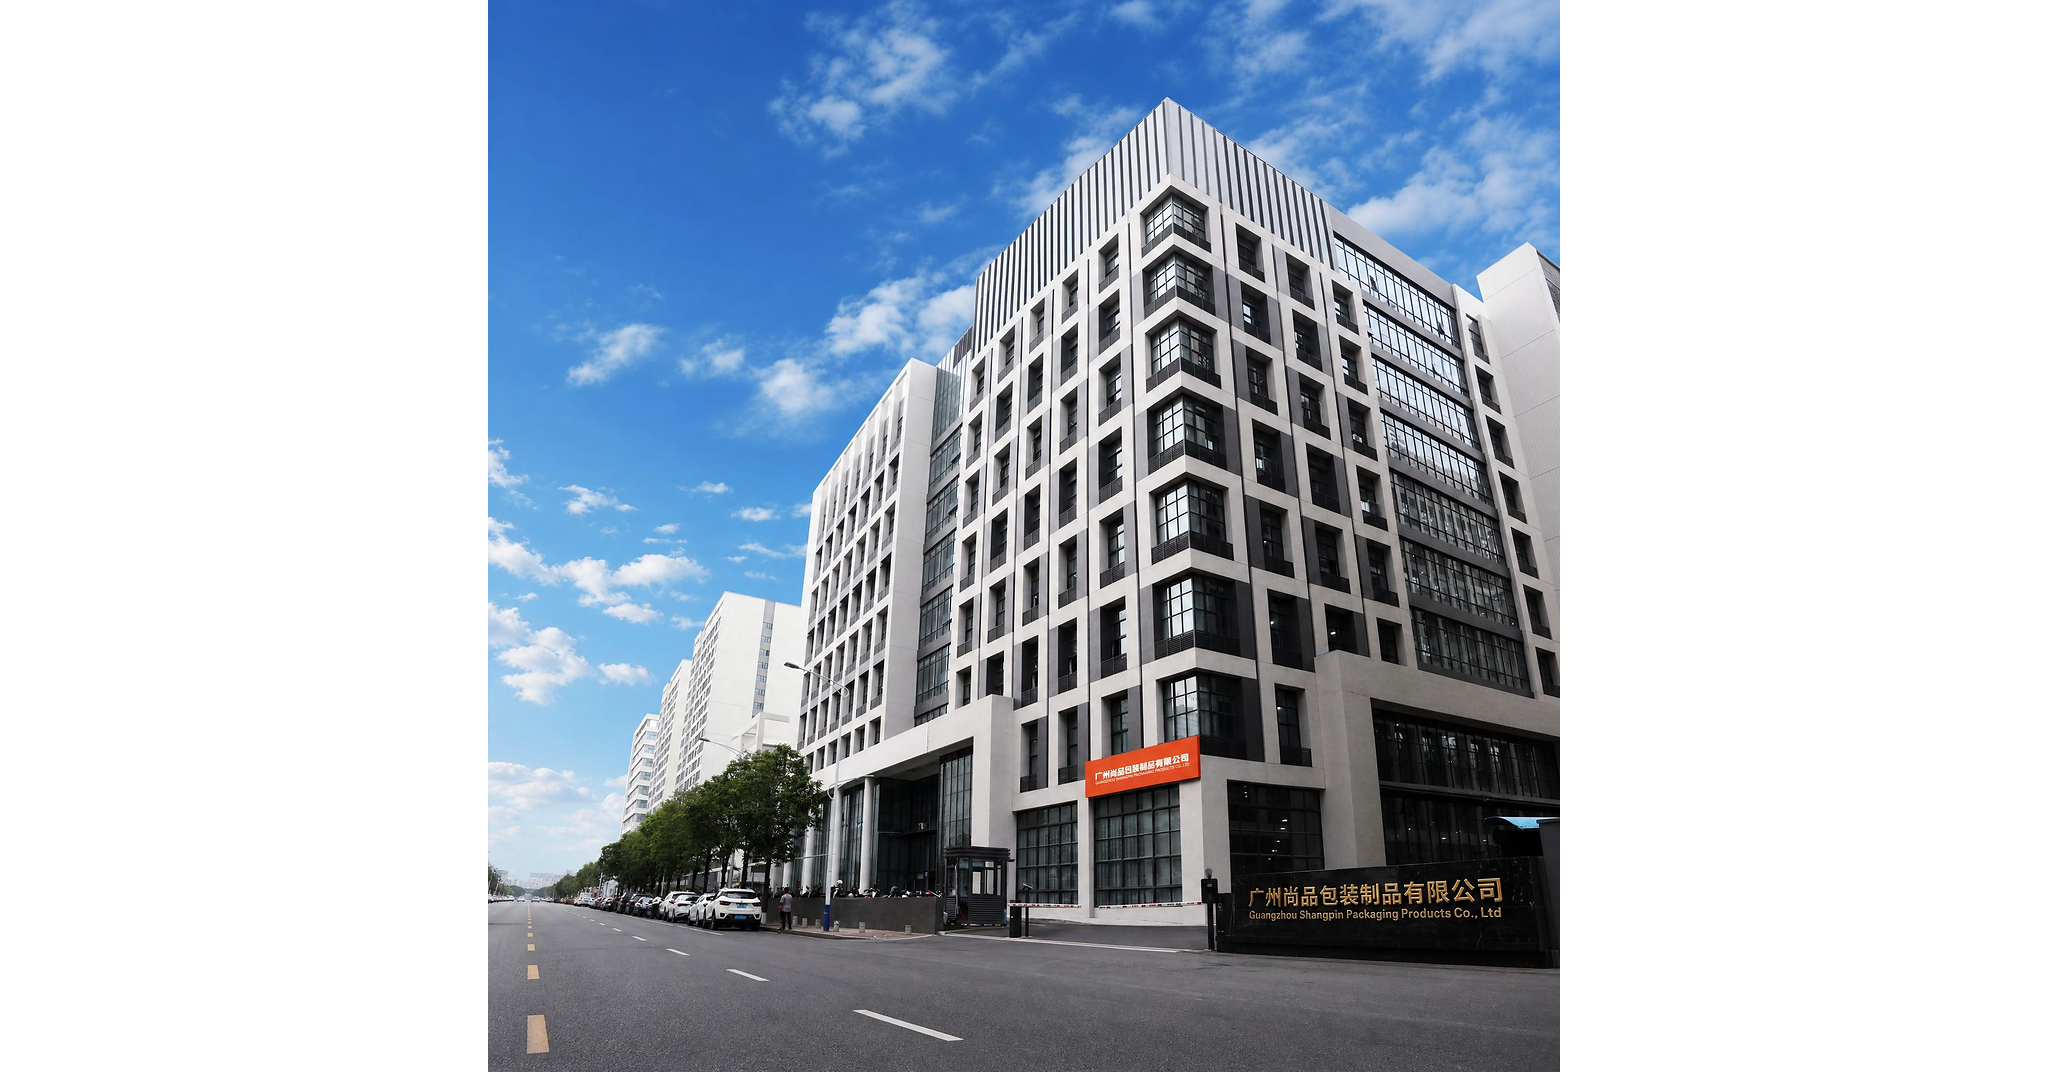
Sprintpackage (Guangzhou Shangpin Packaging Products) relocated manufacturing to a new 20,000 sqm automated facility in Guangzhou, scaling annual output by ~2–3x. The plant runs six fully automated lines (automation >80%), producing ~200,000–300,000 units per day, targeting stable supply of BRC-certified cardboard tube packaging to Europe and the Middle East. The company also projects 10–15 million sushi tubes annually, supported by EU EC1935/2004 food-contact certification and BRC packaging standards, with additional compliance for packaging waste under EU PPWR.
Analysis
This is more a supply-side signal than a demand signal. A low-cost, highly automated Chinese converter adding capacity into food/cosmetics/supplement packaging usually means incremental pricing pressure for smaller regional suppliers, while large brand owners gain a modest procurement lever and faster lead times. The real moat here is less the plant itself than the certification stack; once BRC/FSC/FDA/food-contact compliance becomes table stakes, scale and automation become the only durable path to defend gross margin.
For listed equities, the direct read-through to GLP and UNP is minimal. If anything, UNP could see a tiny tailwind from export packaging throughput, but the revenue sensitivity is too diffuse to matter absent evidence of a broader China-to-Europe freight pickup. The more relevant second-order effect is on specialty packaging peers and on CPG buyers that can renegotiate supplier terms over the next 1-3 quarters; that tends to compress supplier multiples before it shows up in reported volumes.
Contrarian take: the market may overestimate the strategic significance of a press-release capacity expansion. In this segment, added capacity often precedes price competition, not industry-wide growth, and the biggest winners are the end customers, not the manufacturer. What would falsify the bearish-to-neutral packaging read is a sustained step-up in order books from branded food/cosmetics clients or evidence that PPWR/food-safety enforcement is reducing the number of qualified suppliers enough to support pricing over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade in GLP or UNP on this headline; expected fundamental impact is de minimis unless there is corroborating freight/order data over the next 1-3 months.
- If looking for a cleaner expression, short a small basket of listed packaging names on strength (e.g., PKG/SEE/AVY) only if they guide to softer pricing or margin pressure next earnings season; risk is a false signal if this is isolated capacity, not industry-wide oversupply.
- Watch EU PPWR and food-contact compliance developments over 6-12 months; if certification becomes more restrictive, revisit long certified incumbents versus non-certified converters.
- Set an alert for any commentary from CPG buyers on packaging cost savings; if procurement teams start citing lower input costs, that would support a long consumer-staples / short packaging-suppliers relative-value trade.
More News
- Here are the stocks reporting next week that have a history of earnings beats and big share gains
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Faraday Copper completes acquisition of BHP’s San Manuel project
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom