
Zerova to bring its MCS dispenser to Europe at IAA Transportation 2026
Source: PR Newswire
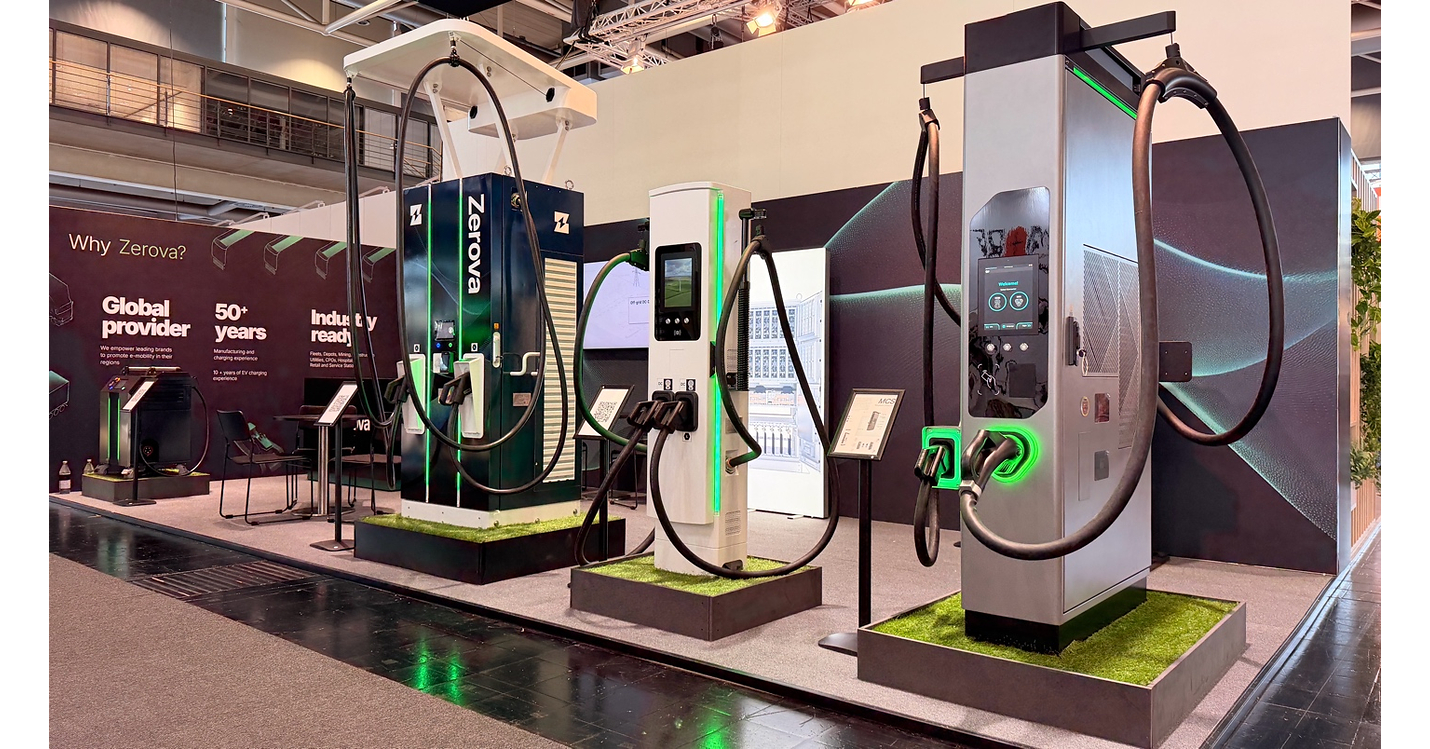
Zerova launched its MCS dispenser for Europe at IAA Transportation 2026, targeting fleet and corridor charging for electric heavy-duty trucks and buses. The unit delivers up to 1,440kW and 1,500A of liquid-cooled output, supporting the emerging CharIN Megawatt Charging System standard and deployment across EU/EEA markets. The product expands Zerova's European fleet-charging offering into megawatt-class truck and long-haul coach infrastructure.
Analysis
This is not yet a revenue catalyst for public markets; it is evidence that megawatt charging is moving from prototype risk toward procurement readiness. The binding constraint for European truck electrification shifts from vehicle availability to depot grid interconnection, transformer lead times, and demand-charge economics. That favors integrated infrastructure owners and electrical-equipment vendors over standalone charger hardware vendors, whose pricing power should deteriorate as MCS connector interoperability reduces product differentiation.
Near term (days to 1 month), IAA announcements are unlikely to move listed charging equities absent disclosed purchase orders, site counts, or utility agreements. Over the next 1-3 months, watch whether Daimler Truck, Volvo, Traton, Milence, and European logistics operators announce fleet deployments tied to committed megawatt-capable power capacity; those announcements would validate utilization, not merely charger availability. The critical missing data are installed-cost per stall, power-sharing performance, uptime guarantees, and signed European backlog.
Over 6-18 months, higher-power depot deployments should expand demand for ABB, Schneider Electric, Siemens Energy and Eaton equipment—medium-voltage switchgear, transformers, rectifiers and energy-management software can represent a larger and less commoditized profit pool than dispensers. A contrarian risk is that fleets defer corridor charging: predictable return-to-base routes can electrify using lower-power overnight charging, while public MCS utilization remains poor until truck volumes scale. This would push hardware orders out despite aggressive OEM demonstration schedules.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No standalone trade on this release; set an alert for disclosed MCS orders, deployment sites, and contracted power capacity from European fleet operators over the next 90 days.
- Build a 6-18 month watchlist long basket of ABB (ABBN.SW), Schneider Electric (SU.PA), Eaton (ETN), and Siemens Energy (ENR.DE), with preference for companies reporting accelerating data-center and grid-equipment backlog alongside transport-electrification demand. Thesis is falsified if medium-voltage order growth decelerates or transformer/switchgear lead times normalize materially.
- Prefer electrical-infrastructure exposure over pure-play charging equities such as EVgo (EVGO) and ChargePoint (CHPT): MCS standardization increases hardware comparability while utilization and service liabilities remain uncertain. Reassess if pure plays disclose multi-year, take-or-pay fleet contracts with positive site-level EBITDA.
- Monitor Daimler Truck (DTG.DE), Volvo AB (VOLV-B.ST), and Traton (8TRA.DE) for electric-truck order conversion rather than product targets. A sustained increase in battery-electric heavy-truck backlog, paired with charging-network commitments, would support a long OEMs versus short European diesel-component exposure over 12 months.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Microsoft's Big Bets on AI Start to Pay Off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Microsoft’s strong quarter backs up its stock rebound. Here's our new price target
- Can Southeast Asia pitch itself as an ‘all-in-one’ chip hub?