
ASSAÍ REPORTS 55% PROFIT SURGE AND DELEVERAGES IN Q3
Source: PR Newswire
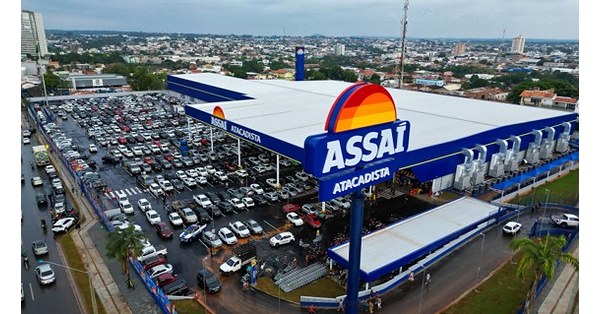
Assaí reported 3Q26 adjusted recurring net income of R$248 million, up 55.2% year over year, and gross revenue of R$21.3 billion, up 2.7%; accounting net income rose 119% to R$427 million, including R$179 million in extemporaneous PIS/COFINS tax credits. Adjusted EBITDA was R$1.1 billion at a stable 5.7% margin, while leverage fell to 2.15x from 3.03x a year earlier. Customer traffic increased 2.1% despite household indebtedness, and the company continued expanding pharmacies, private-label products and digital sales.
Analysis
The quality of the quarter is better judged by recurring earnings and cash conversion than by headline net income: the tax-credit contribution is non-recurring and should not be capitalized into the earnings base. The more investable signal is whether operating cash flow continues to reduce leverage without sacrificing price competitiveness. Lower financing expense can amplify equity earnings as debt falls, but the reported improvement in receivables-discounting costs may not persist if funding conditions or the receivables mix reverse.
Near term, investors may reward the combination of margin resilience and deleveraging, but the result alone does not establish durable real sales growth or market-share gains; verify same-store sales, volumes, and pricing against inflation and competitors such as Atacadão and GPA. Over 1–3 months, the key catalyst is confirmation in subsequent trading updates and guidance that margin gains reflect repeatable execution rather than mix or temporary cost relief. Over 6–18 months, pharmacies, private label, digital fulfillment, and fuel/convenience offer potential customer retention and basket expansion, but also add execution and capital-allocation risk. The fuel initiative is too far from operations to underwrite near-term earnings.
Contrarian view: the market may overvalue reported profit growth while underweighting the quality of the recurring result and the possibility that competitive pricing absorbs margin gains. Conversely, dismissing the quarter because of the tax credit would miss the balance-sheet improvement. Without valuation, capex, and peer data, this is a monitor-for-confirmation setup, not a high-conviction chase.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- Do not extrapolate the reported net-income growth; use recurring earnings as the base and treat the tax-credit benefit as non-recurring.
- Watch Assaí’s next results for same-store sales and volume trends, gross-margin durability, operating cash flow, leverage, and financing costs. A reversal in deleveraging or margin contraction would falsify the improving-quality thesis.
- Keep Assaí on a conditional long watchlist rather than adding on the release alone; consider entry after a valuation review if cash generation and leverage reduction continue without weaker sales or pricing competitiveness.
- Treat the pharmacy, private-label, digital, and fuel initiatives as options rather than booked value until unit economics, required investment, and returns are disclosed; reassess if expansion materially pressures cash flow.
More News
- Further turmoil could be in store for tech stocks. What to watch in the week ahead
- Tech stock rout, driven by US AI fears, continues in Asian trading
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- AI stocks hammered by midterm shock as data center buildout becomes a 'war of attrition'
- Fox completes its $22B acquisition of Roku
- Elanco Shares Jump After Q3 Beat and Outlook Raise