
Used Truck and Trailer Inventory Down in October as Semi-Trailer Auction Values Jump Nearly 20%
Source: PR Newswire
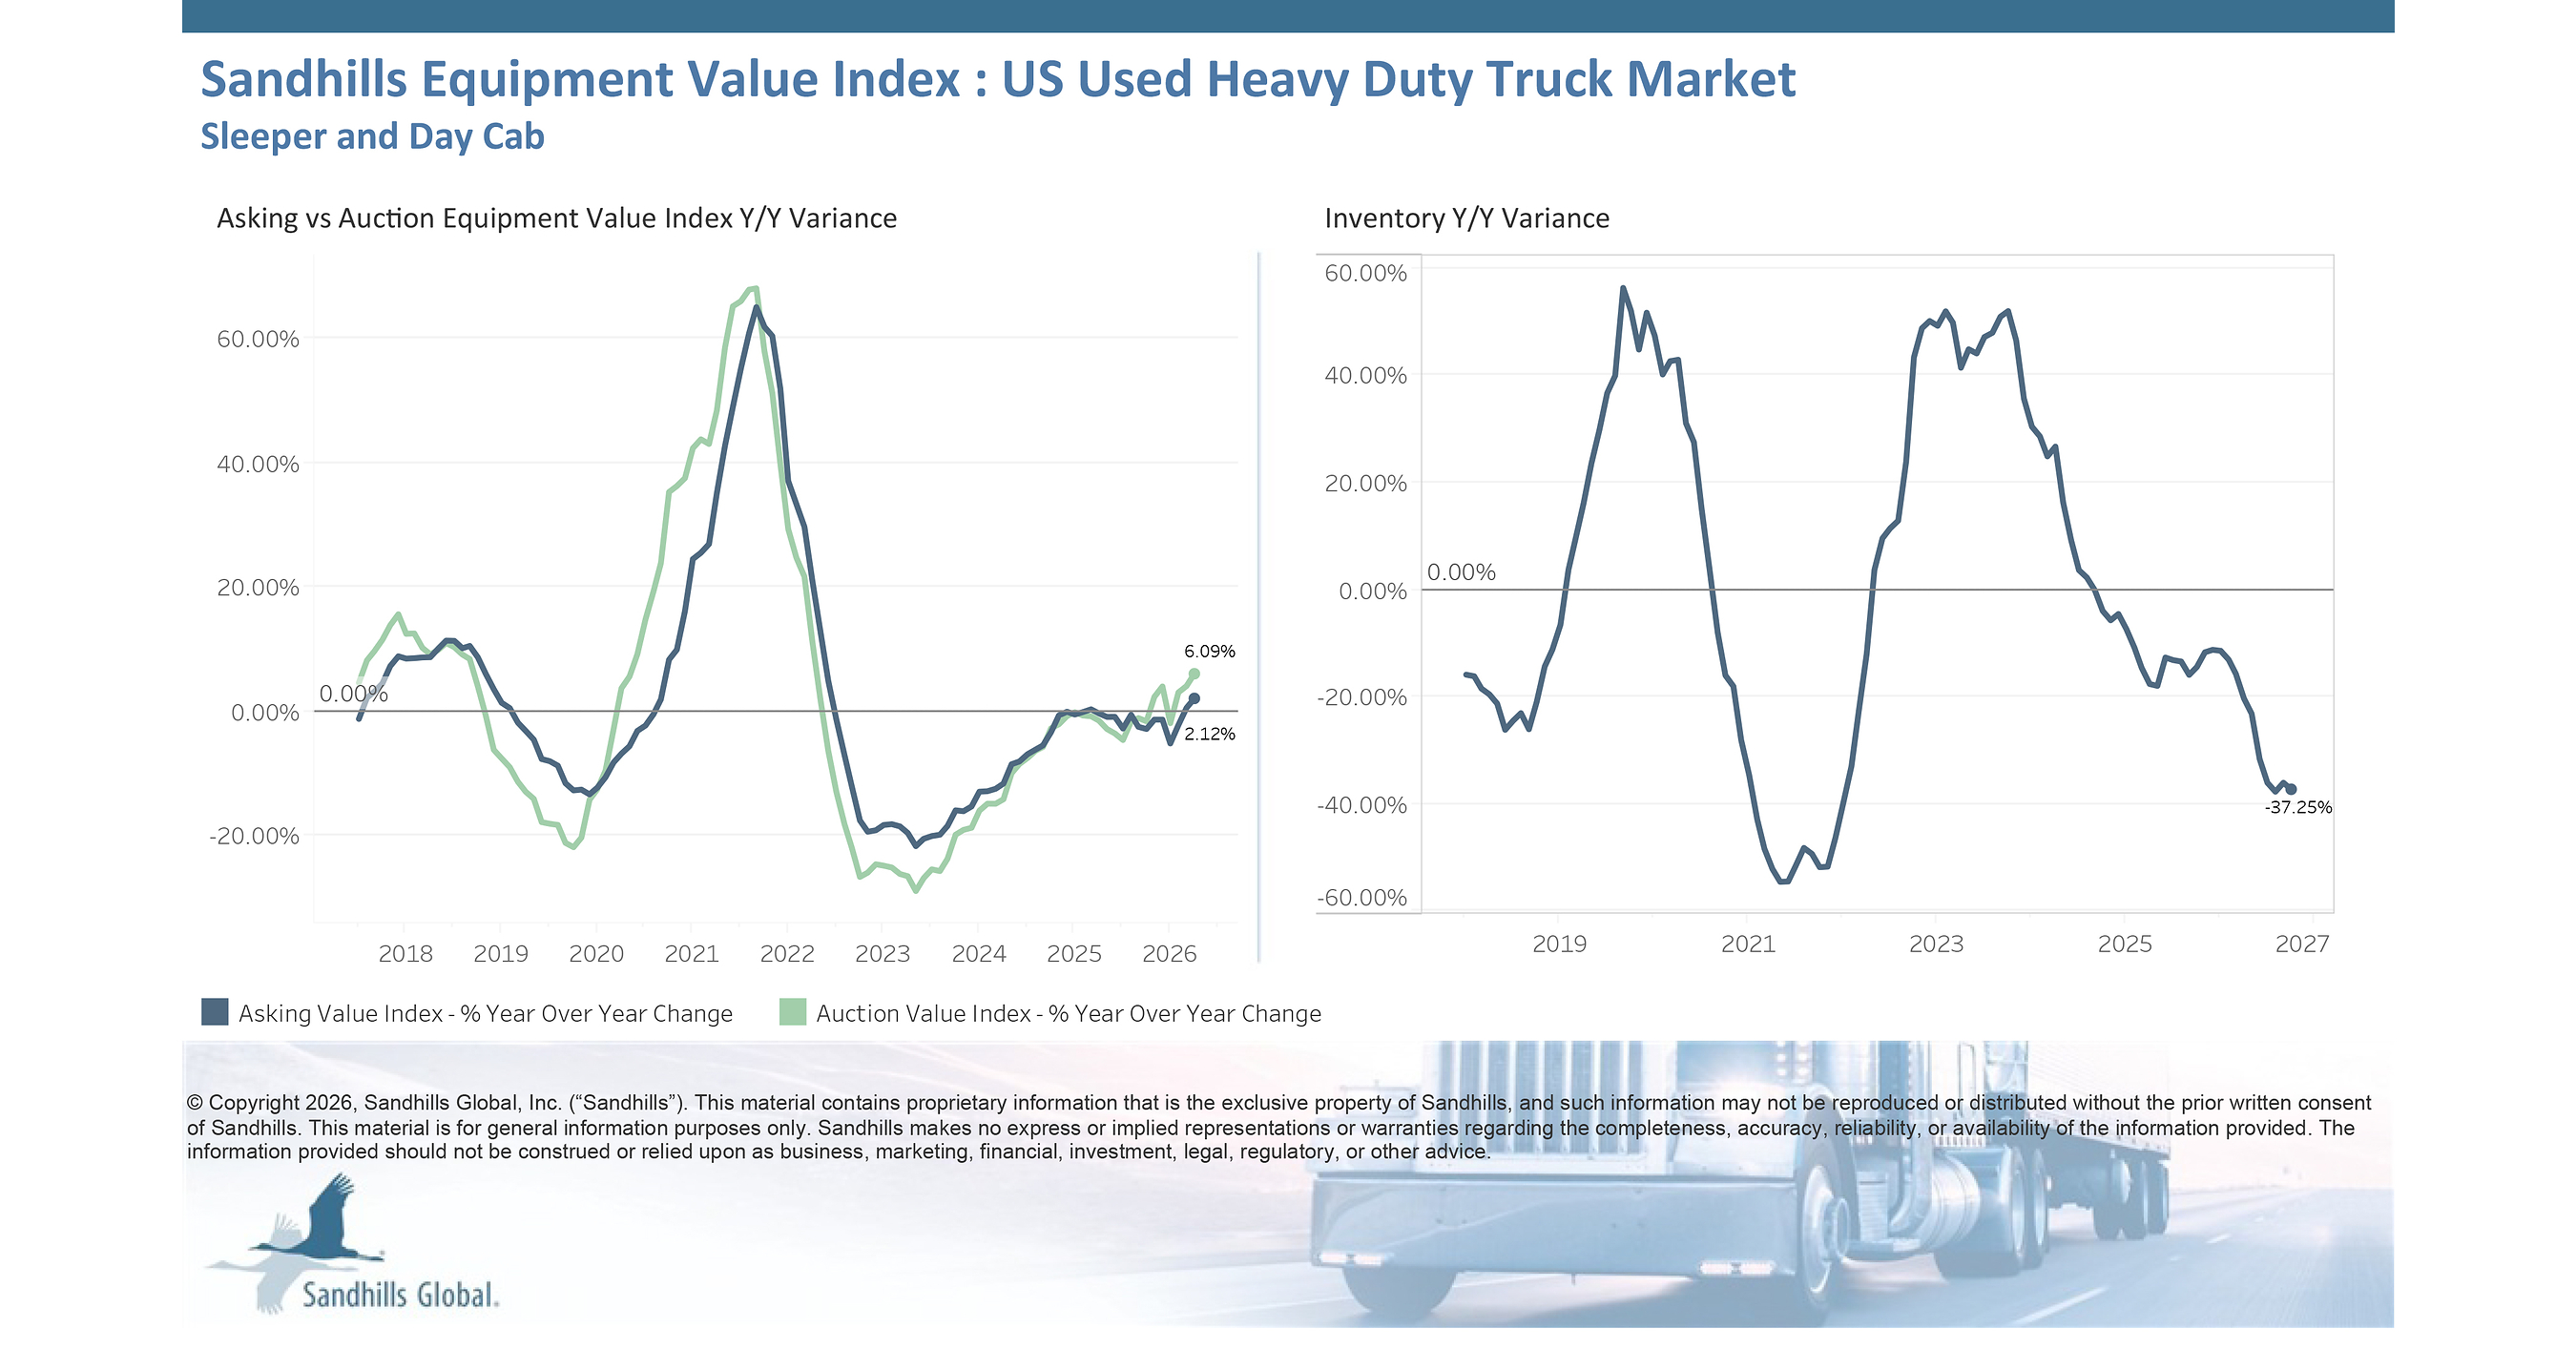
Sandhills Global’s October data showed used-equipment inventories below year-ago levels across most segments, led by declines of 37.25% for heavy-duty trucks and 33.92% for semi-trailers. Semi-trailer auction values rose 3.18% month over month and 19.64% year over year, while heavy-duty construction equipment auction values fell 2.04% and 4.95%, respectively. Aerial lifts and forklifts were exceptions to the broad inventory declines, with year-over-year stock up 4.12% and 11.41%; their auction values were down 3.6% and 5.95% year over year.
Analysis
The useful signal is the split between tight truck/trailer supply and weakening construction-equipment price discovery—not a broad “equipment cycle” call. For OEMs and lessors, stronger used values can support collateral recovery and residuals where they bear that risk; for carriers and contractors, they raise replacement costs and can encourage fleets to defer purchases. That makes used values supportive of asset quality but not automatically supportive of new-unit demand.
Construction is the more concerning margin signal: prices are falling even as reported inventories remain below year-ago levels, consistent with softer buyer urgency rather than simple oversupply. If sustained, this can pressure auction proceeds and rental-fleet disposal economics; verify actual sale volumes, rental utilization, and OEM dealer inventories before translating it into earnings risk. Agriculture is less decisive: wide asking-versus-auction gaps suggest seller expectations may be slow to adjust, so asking prices are a weak read-through to realized values.
Near term, Sandhills data are a sentiment/collateral indicator, not evidence of OEM orders or fleet capex. Over 1–3 months, dealer inventory, auction volumes, and company guidance should determine whether the construction weakness broadens. Over 6–18 months, persistent truck/trailer scarcity could support residuals while delaying replacement demand; a freight downturn would reverse that balance quickly. The contrarian risk is treating low inventory as proof of pricing power when falling auction values may instead signal demand fading faster than supply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.05
Key Decisions for Investors
- No broad equipment-sector trade on this report alone. Treat it as a watch signal; Sandhills platform data do not establish transaction volumes, OEM shipments, or company-level earnings impact.
- Conditional relative-value watch: underweight construction-equipment exposure such as Caterpillar versus Deere, CNH Industrial, and AGCO only if subsequent auction data and OEM/dealer commentary confirm construction price weakness while agricultural realized values hold. Keep exposure small given the mixed farm indicators; exit the thesis if construction auction values stabilize and dealer inventories do not build.
- For truck and trailer exposure, avoid extrapolating stronger used collateral values into a new-equipment demand forecast. Reassess after freight-rate and carrier-capex updates; a material freight downturn or renewed deterioration in auction values would undermine the residual-value support.
More News
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- Fox completes its $22B acquisition of Roku
- Elanco Shares Jump After Q3 Beat and Outlook Raise
- Russia to UAE, Iran steps up diplomacy amid Trump threats: What we know
- Paraguay’s Santiago Pena under arrest, new president Pedro Alliana sworn in
- FIGS Beats Earnings as Demand Outstrips Supply, CEO Trina Spear Says