
GATOR METAL ROOFING DEMAND SOARS: NORTH CAROLINA MANUFACTURING FACILITY DOUBLES ROOFING PRODUCTION CAPACITY WITH SECOND ROLL-FORMING MACHINE
Source: PRWeb
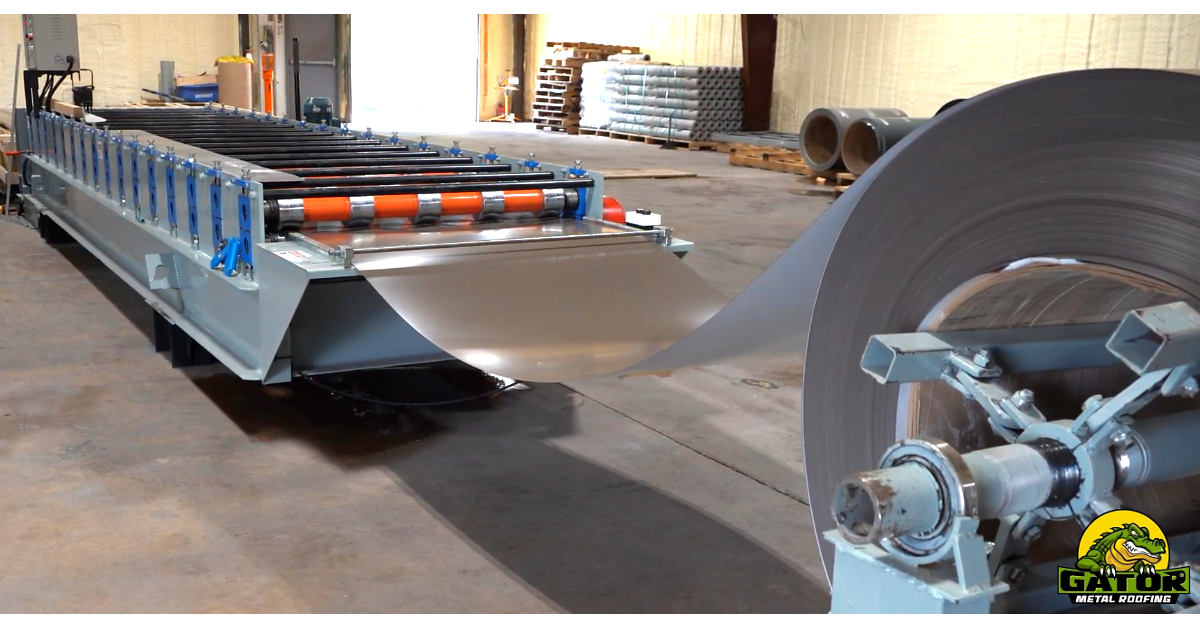
Gator Metal Roofing added a second roll former at its Asheboro, North Carolina, facility, enabling production seven days a week as the company responds to rising demand for metal roofing across North and South Carolina. The expansion supports manufacturing capacity and installation growth; the release gives no revenue, output, or investment figures.
Analysis
This is a low-signal, company-sponsored indicator—not evidence of a broad roofing-cycle inflection. A second roll former and seven-day schedule suggest the constraint may be shifting from fabrication to installer availability, scheduling, and working capital; if installation capacity cannot scale, added equipment may raise fixed costs without lifting completed-roof revenue. The claim of unusually low pricing also cuts both ways: it may aid share capture, but could indicate that growth is being bought with price rather than differentiated economics. Metal coil suppliers receive a small potential demand increment, while asphalt-shingle producers face a substitution headwind only if adoption broadens beyond this regional operator. No public ticker is supplied for Gator, and the article gives no output, utilization, capex, unit economics, or independently verified demand data; the impact on diversified public roofing names is therefore not quantifiable from this announcement.
Near term, little reason to expect a material read-through to listed equities. Over 1–3 months, verify whether the company adds installation crews and reports sustained completed-project growth rather than just machine hours. Over 6–18 months, the structural question is whether metal roofing wins share despite higher upfront cost, and whether savings and durability claims translate into homeowner conversion. Reversal risks include a housing/remodeling slowdown, financing pressure on discretionary projects, labor shortages, or steel-price increases that undermine the pricing proposition. The contrarian point: expanded capacity can signal genuine demand, but a single private operator’s press release may overstate what it says about the regional market.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No direct trade on this release: Gator is private and the evidence is company-reported, local, and operational rather than financial.
- Treat publicly traded roofing and building-products names, including Owens Corning, as watchlist read-throughs only; do not infer material earnings exposure without evidence of wider metal-roofing share gains.
- Monitor follow-up evidence over the next 1–3 months: installation-team growth, completed projects, machine utilization, pricing, and any indication that fabrication—not labor or customer financing—is the binding constraint.
- Falsify the demand-growth interpretation if the new line runs below expected utilization, installation backlogs fail to convert to completed roofs, or the company relies on discounting that weakens unit economics.
More News
- Asia stocks fall as AI rout batters S.Korea; Japan spooked by strong CPI
- SK Hynix shares slide after chipmaker scraps Solidigm IPO plans
- Why is SK Hynix stock sliding today?
- Apple’s iPhone Duo Hits Stores in Face of Short Supply and High Demand
- Gold Holds Near Three-Month Low as AI Jitters Fuel Volatility
- OpenAI nears up to $30 billion funding round at $1.25 trillion valuation led by UAE investors
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research