
Rip Van Names Former Hershey U.S. President Todd Tillemans Chief Executive Officer
Source: PR Newswire
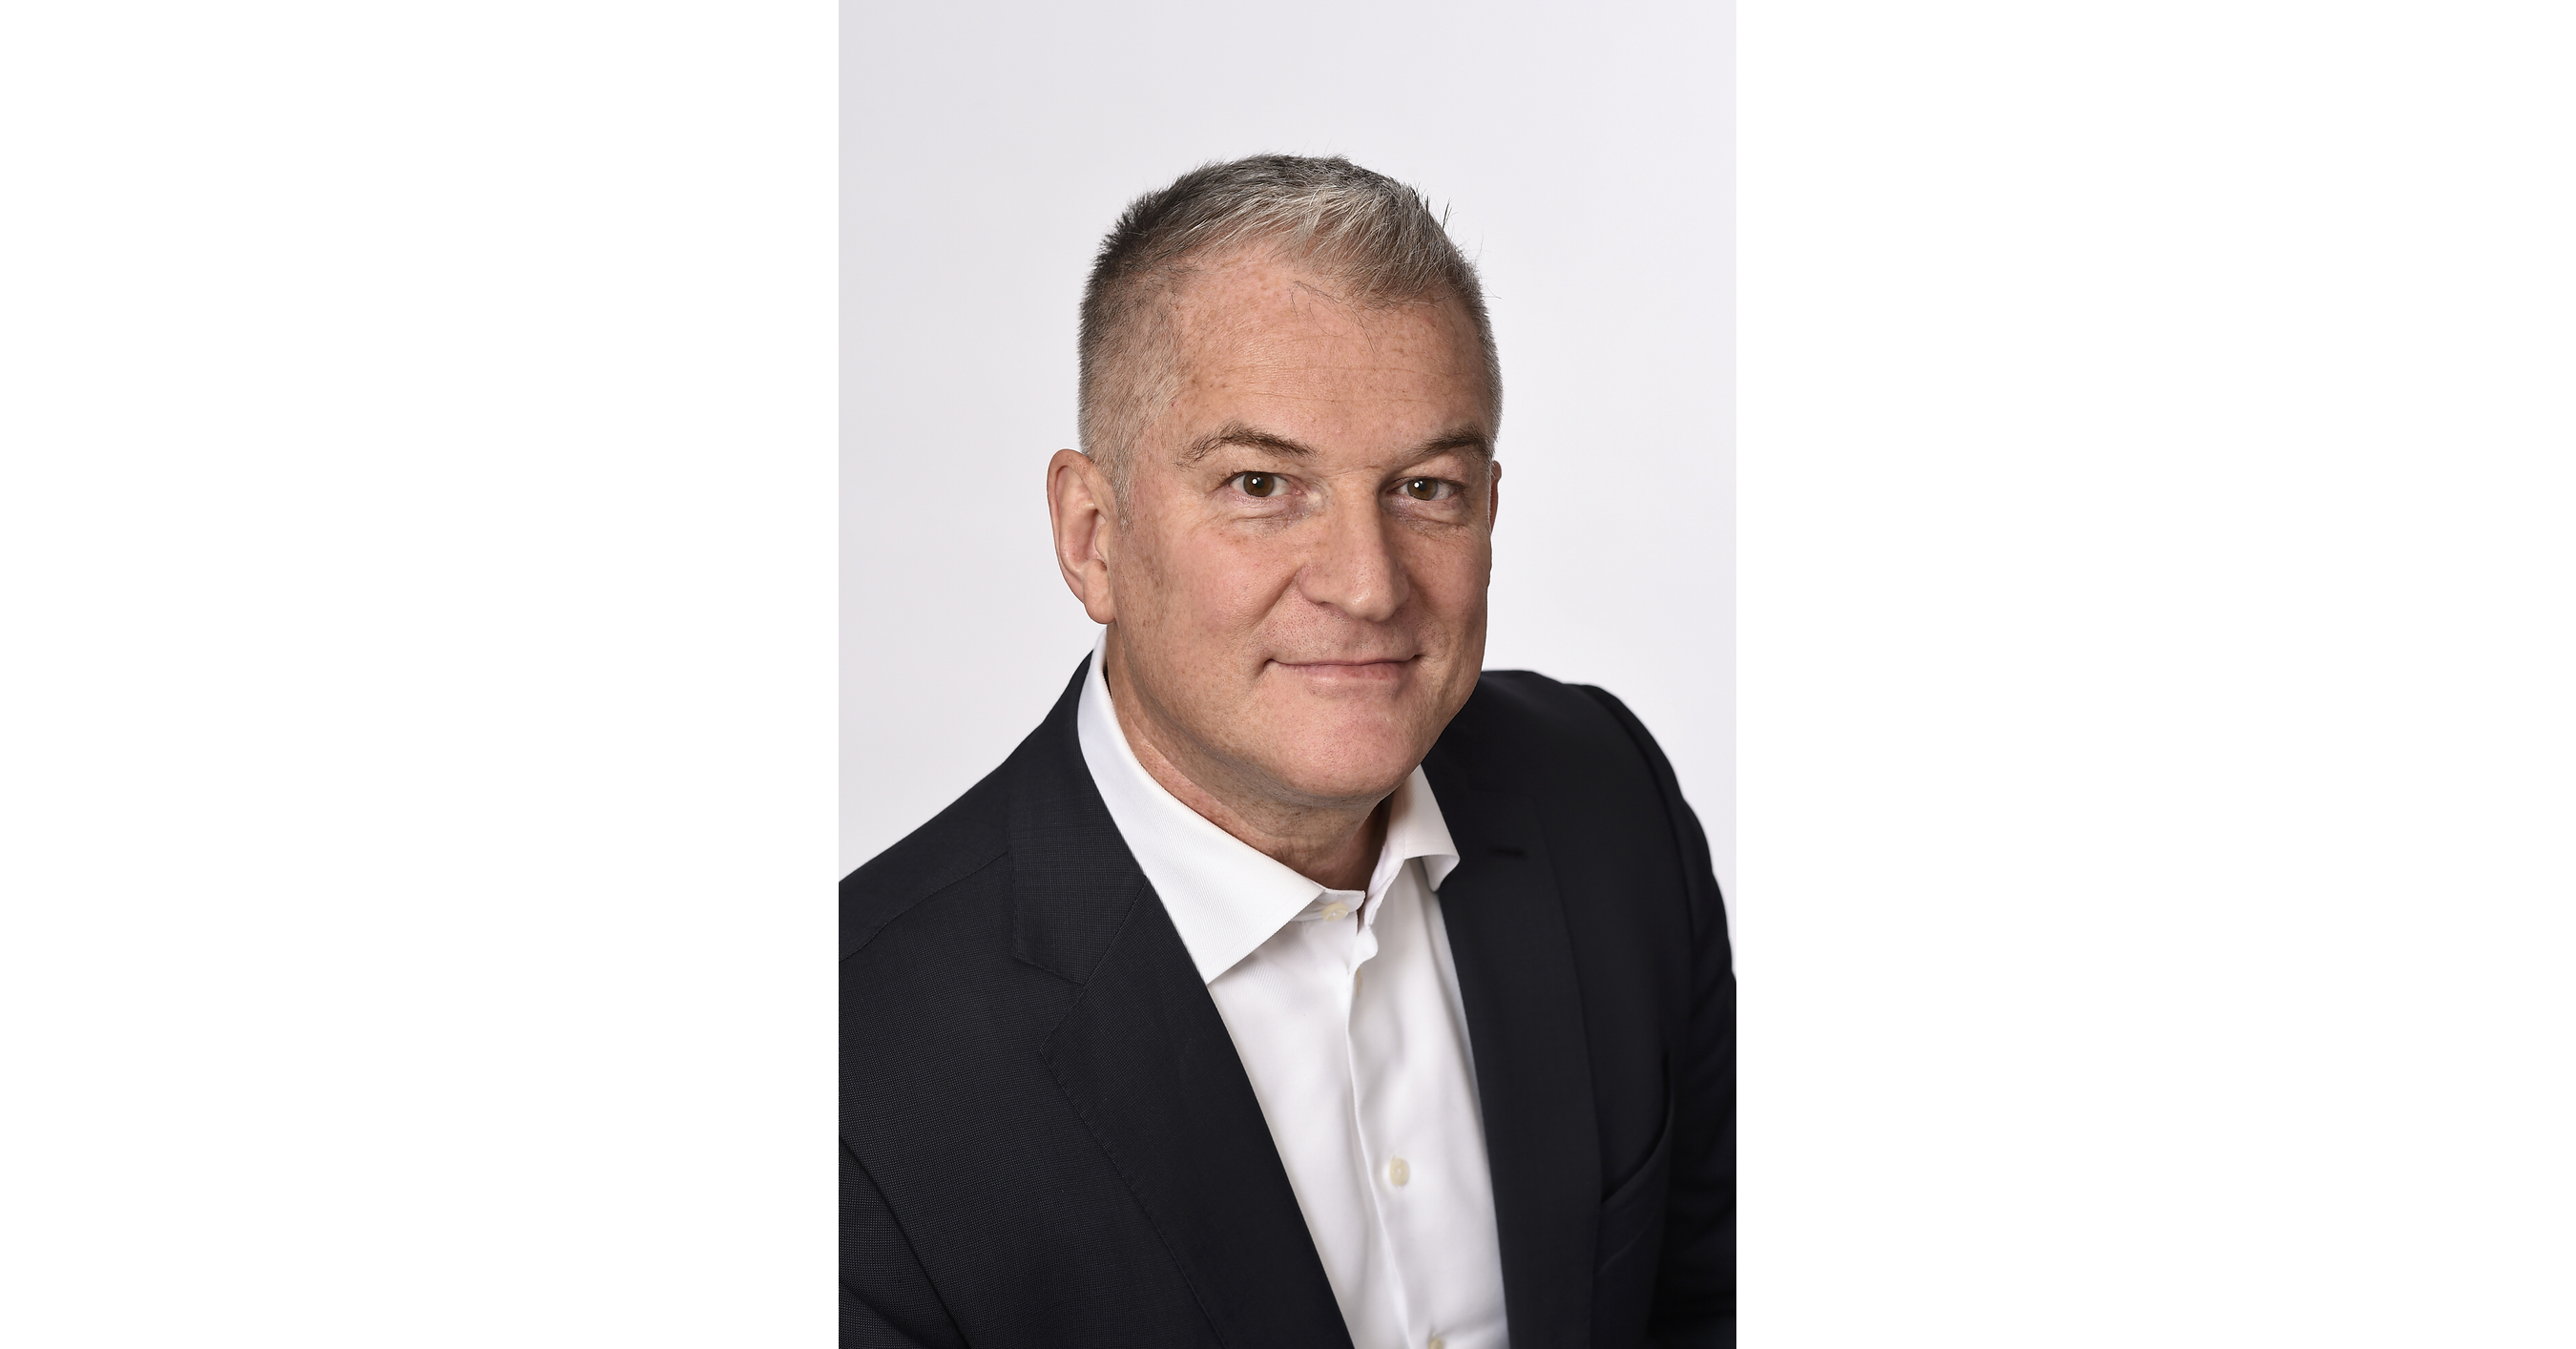
Rip Van appointed former Hershey U.S. President Todd Tillemans as CEO as the snack brand surpassed $100 million in retail sales. The company added nearly 1,800 retail doors in its largest expansion to date, including Albertsons, Walmart, BJ's and Wawa, and is now available in more than 26,000 doors nationwide. Co-founder Rip Pruisken will remain involved in the business and on the Board; co-founder Marco De Leon remains CFO and a Board member.
Analysis
The investable signal is execution, not the CEO appointment itself: more doors create an opportunity, but only repeat purchases and productive shelf space turn distribution into durable revenue. The retailer count and retail-sales milestone are company-reported; neither establishes store-level velocity, reorder rates, gross-margin quality, or profitable growth. A seasoned operator may improve customer negotiations and launch discipline, but his prior roles do not establish that those capabilities will transfer to a smaller brand with a distinct formulation and operating model.
Over the next 1–3 months, watch for evidence of sustained velocity and retailer reorders rather than additional placement announcements. Over 6–18 months, poor turns could mean promotional spending, shelf resets, and tougher retailer terms, while successful repeat buying could pressure incumbent sweet-snack brands at the margin and prompt copycat launches. Any impact on HSY, GIS, UL, or NESN is likely immaterial absent evidence of meaningful share loss; WMT, ACI, and BJ may benefit from consumer interest, but the reported expansion alone is not material to their economics. Rip Van is private, so there is no direct public-equity expression. The contrarian point: broad distribution can look like validation while masking weak sell-through. The thesis improves with disclosed retailer velocity, repeat rates, and profitable growth; it weakens if placements fail to generate reorders or require escalating discounts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.36
Ticker Sentiment
Key Decisions for Investors
- No trade in WMT, ACI, BJ, HSY, GIS, UL, or NESN on this announcement alone; likely company-level exposure is too small to establish a public-equity catalyst.
- Treat Rip Van as a private-company watch item. Seek store-level velocity, reorder rates, gross-margin trajectory, and promotional intensity before interpreting retail expansion as scalable demand.
- Revisit the competitive-risk view over the next 6–18 months if verified repeat buying and expanding distribution indicate sustained share gains; absent those signals, do not assume incumbent snack companies face meaningful earnings pressure.
More News
- Uber delivery workers will pick up bigger restaurant orders as it enters catering
- Walmart moves to grab a bigger chunk of the TV ad business
- Meta joins with group of companies to tame ‘chaos' of doing business with AI bots
- Stock Movers: Alphabet, Marvell Tech, Empire State (Podcast)
- Sierra announces Personal Agent Protocol, an open standard for personal AI agents
- GIC Private Ltd, Medline 10% owner, sells over $721m in shares