
BUUU firma un acuerdo definitivo para adquirir una participación mayoritaria en Brightray Science Inc.
Source: PR Newswire
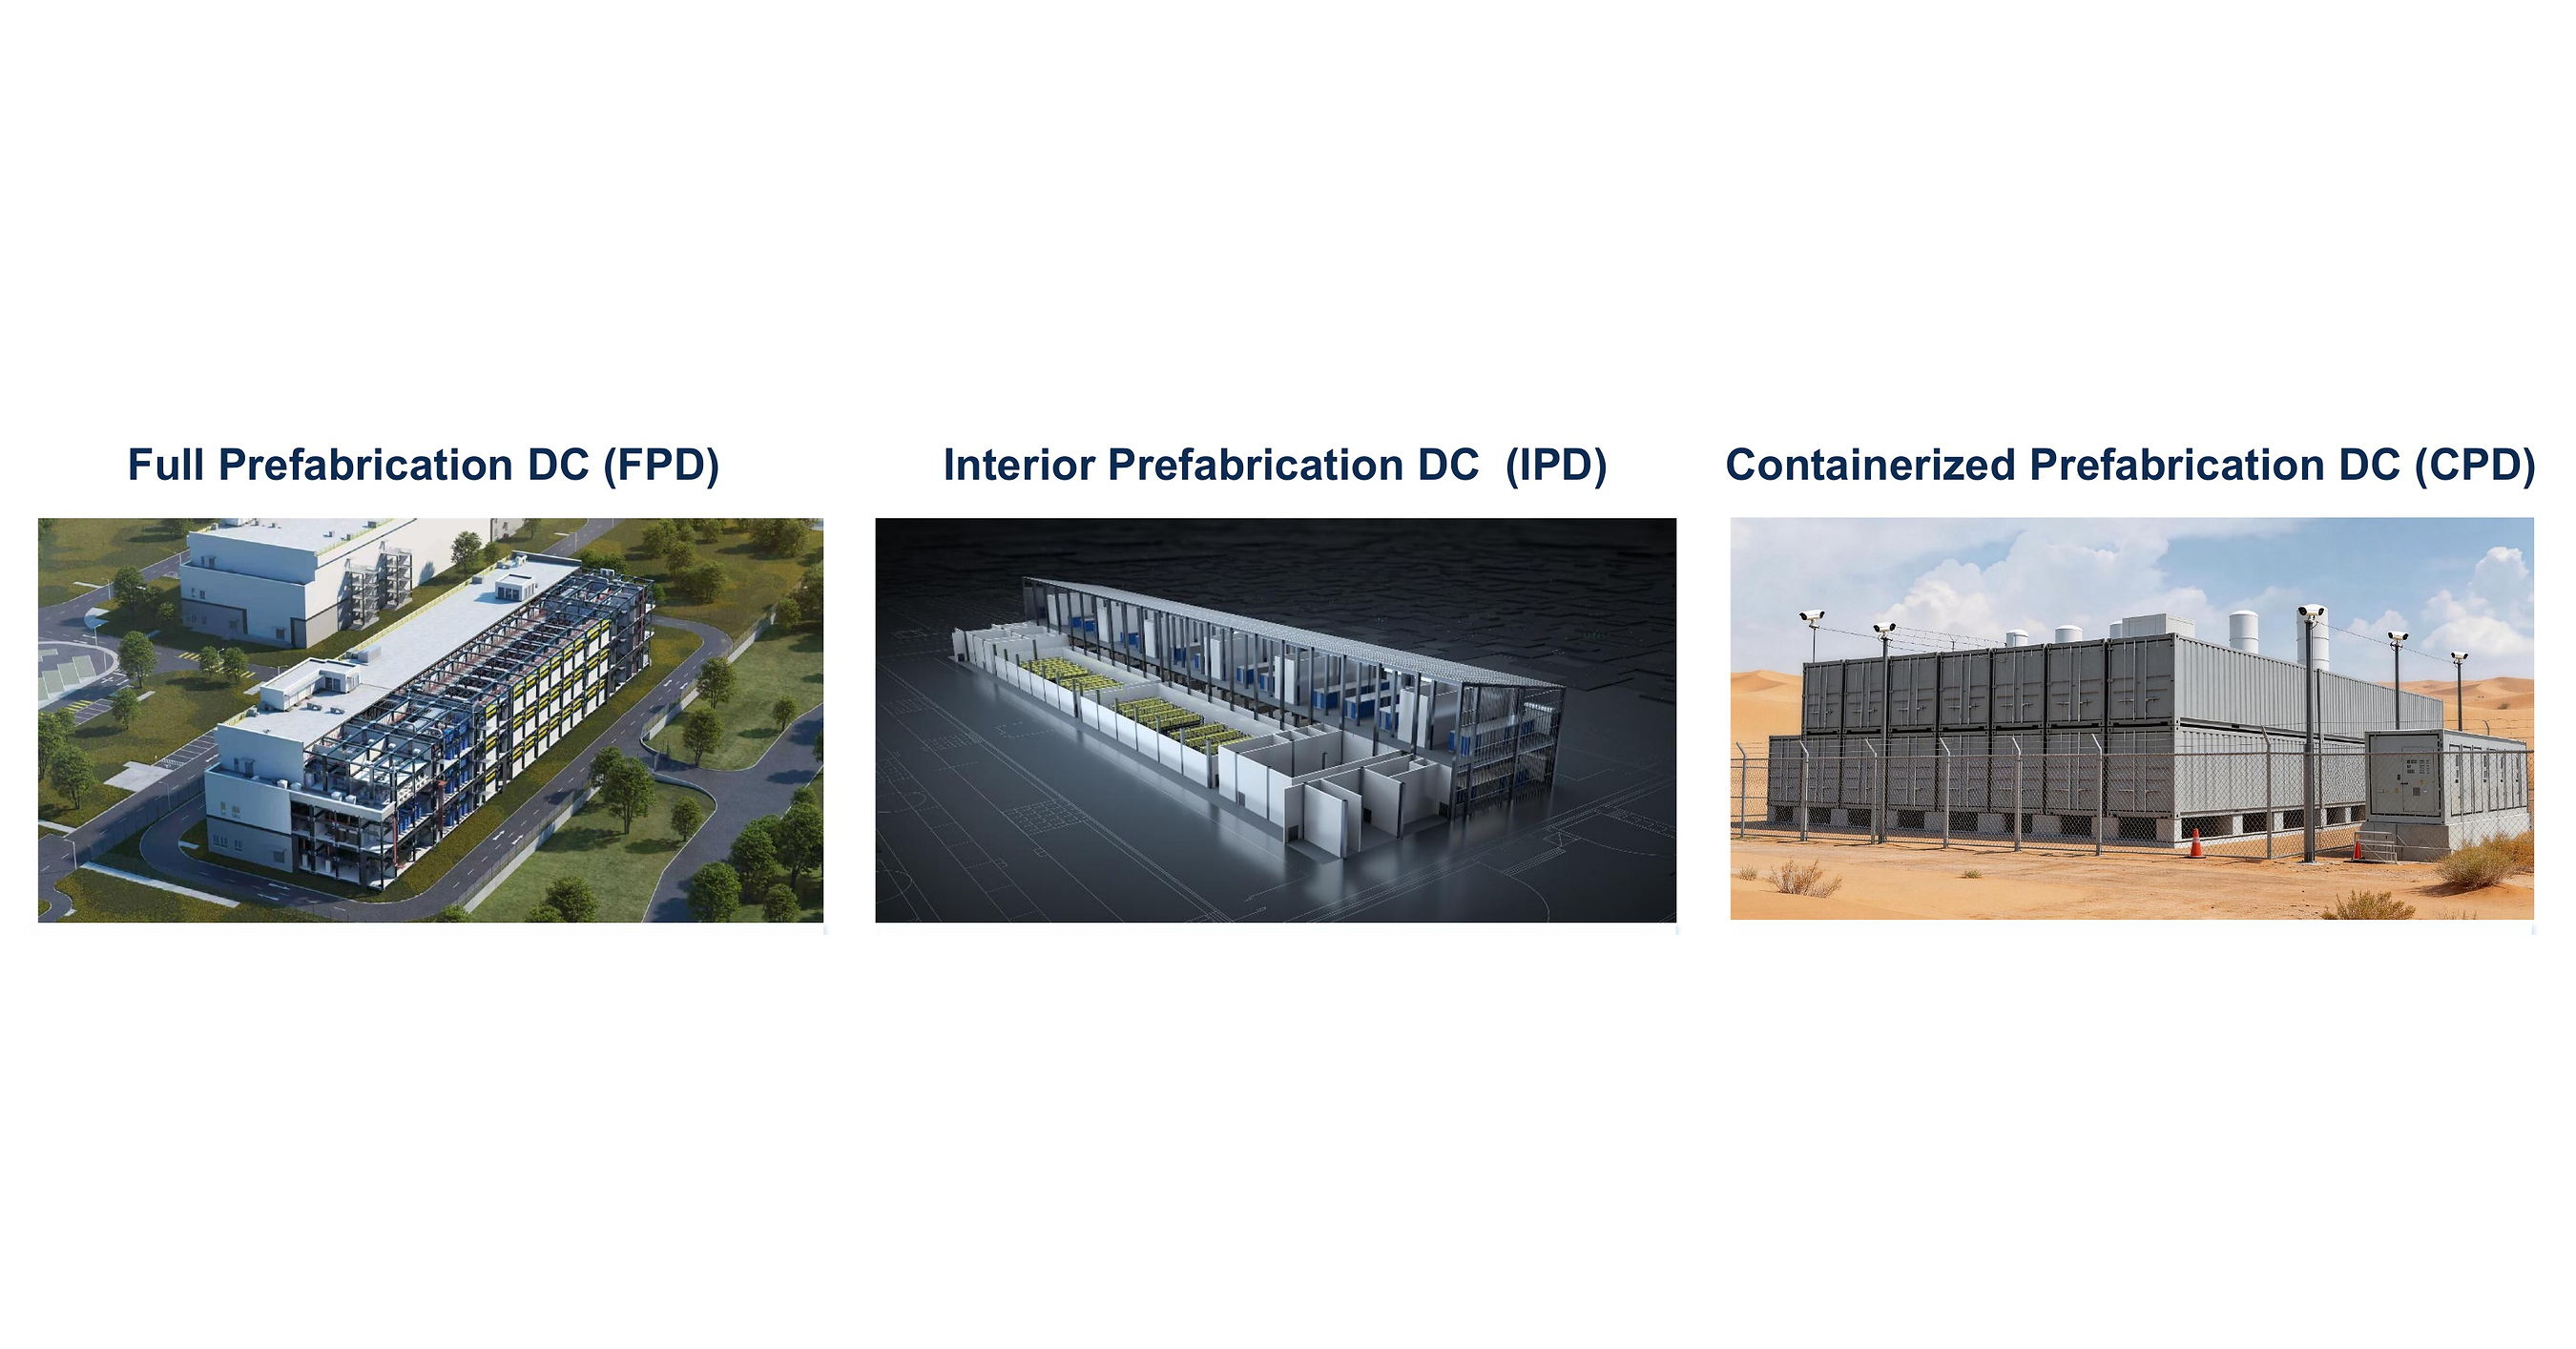
BUUU Group anunció un acuerdo definitivo para adquirir el 60% de Brightray Science y dijo que, junto con colocaciones privadas, espera generar ingresos brutos totales de más de US$60M. La transacción incluye acciones a US$20,00 por acción y un pagaré convertible hasta 10M de acciones, con ajuste por el desempeño (utilidad neta anual auditada) y un tope de propiedad efectiva del 19,99%; además, BUUU planea una opción de compra para adquirir el 40% restante en los 3 años posteriores al cierre. Brightray afirma una cartera objetivo de ~2 GW y que industrializa centros de datos reduciendo plazos de entrega de 18–36 meses a 6–9 meses, con ~70 MW ya operativos en Johor (Malasia).
Analysis
This is more a capital-allocation and execution story than a true fundamental inflection. If modular build-out really shortens revenue activation, the economic surplus flows to whoever controls power, cooling, and interconnect readiness; the prefab assembler captures only a fee on a larger capex stack. That makes the real medium-term winners the infrastructure vendors and data-center enablement names, while BUUU’s equity becomes a financing vehicle with operating leverage to deal conversion rather than a clean compounder.
Near term, the stock can trade like a story-name momentum vehicle, but the setup is diluted by design: acquisition equity, convert-like consideration, and fresh private capital create an overhang before any audited cash earnings exist. The first 1-3 months are about close risk, financing completion, and whether the claimed pipeline converts into signed backlog; the 6-18 month question is whether Brightray can prove repeatable delivery economics outside one reference campus. Until then, the market should assign a steep discount for integration risk and customer concentration.
Contrarian read: consensus is likely underweighting how little modularity matters if the true bottleneck is power availability and permitting. If grid connection, transformers, and switchgear remain scarce, faster factory throughput just moves the queue rather than expanding realizable demand. Falsifiers are simple: failed transaction close, no evidence of backlog conversion within two quarters, or a slowdown in Johor-style deployments despite the announced capacity narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Short BUUU into initial post-announcement strength or use a 1-3 month put spread if borrow is tight; thesis breaks if the private placement closes cleanly and audited Brightray results show real margin and cash conversion.
- Pair trade: long NVDA / short BUUU on a 1-3 month horizon. NVDA monetizes actual AI capex; BUUU monetizes the narrative. Prefer this only if the market keeps extrapolating the pipeline without signed-contract evidence.
- Relative-value long infrastructure enablers like VRT or ETN over BUUU for 6-12 months; modular data centers are likely to commoditize the assembly margin while electrical/cooling bottlenecks stay scarce.
- Do not chase AMD on this print; treat it as a watch item only. Reassess if hyperscalers explicitly shift server-design wins toward AMD-based liquid-cooled architectures in upcoming capex commentary.
More News
- The next AI race will be won at the credit desk
- Tech Bytes: Microsoft pulls out of Aussie-founded Nscale data centre deal as power shortages hit AI boom
- Jim Cramer: Why I am taking the other side of the trade that crushed the market Friday
- TechCrunch Mobility: Rivian’s next act
- The Bond Market Is Sending a Warning to Nvidia Shareholders
- Taiwan Semiconductor Just Proved Why It's a Top AI Investment