
Maverix Medical Expands the Narwhal™ Cryo Portfolio with FDA Clearance of the Narwhal Pro
Source: PR Newswire
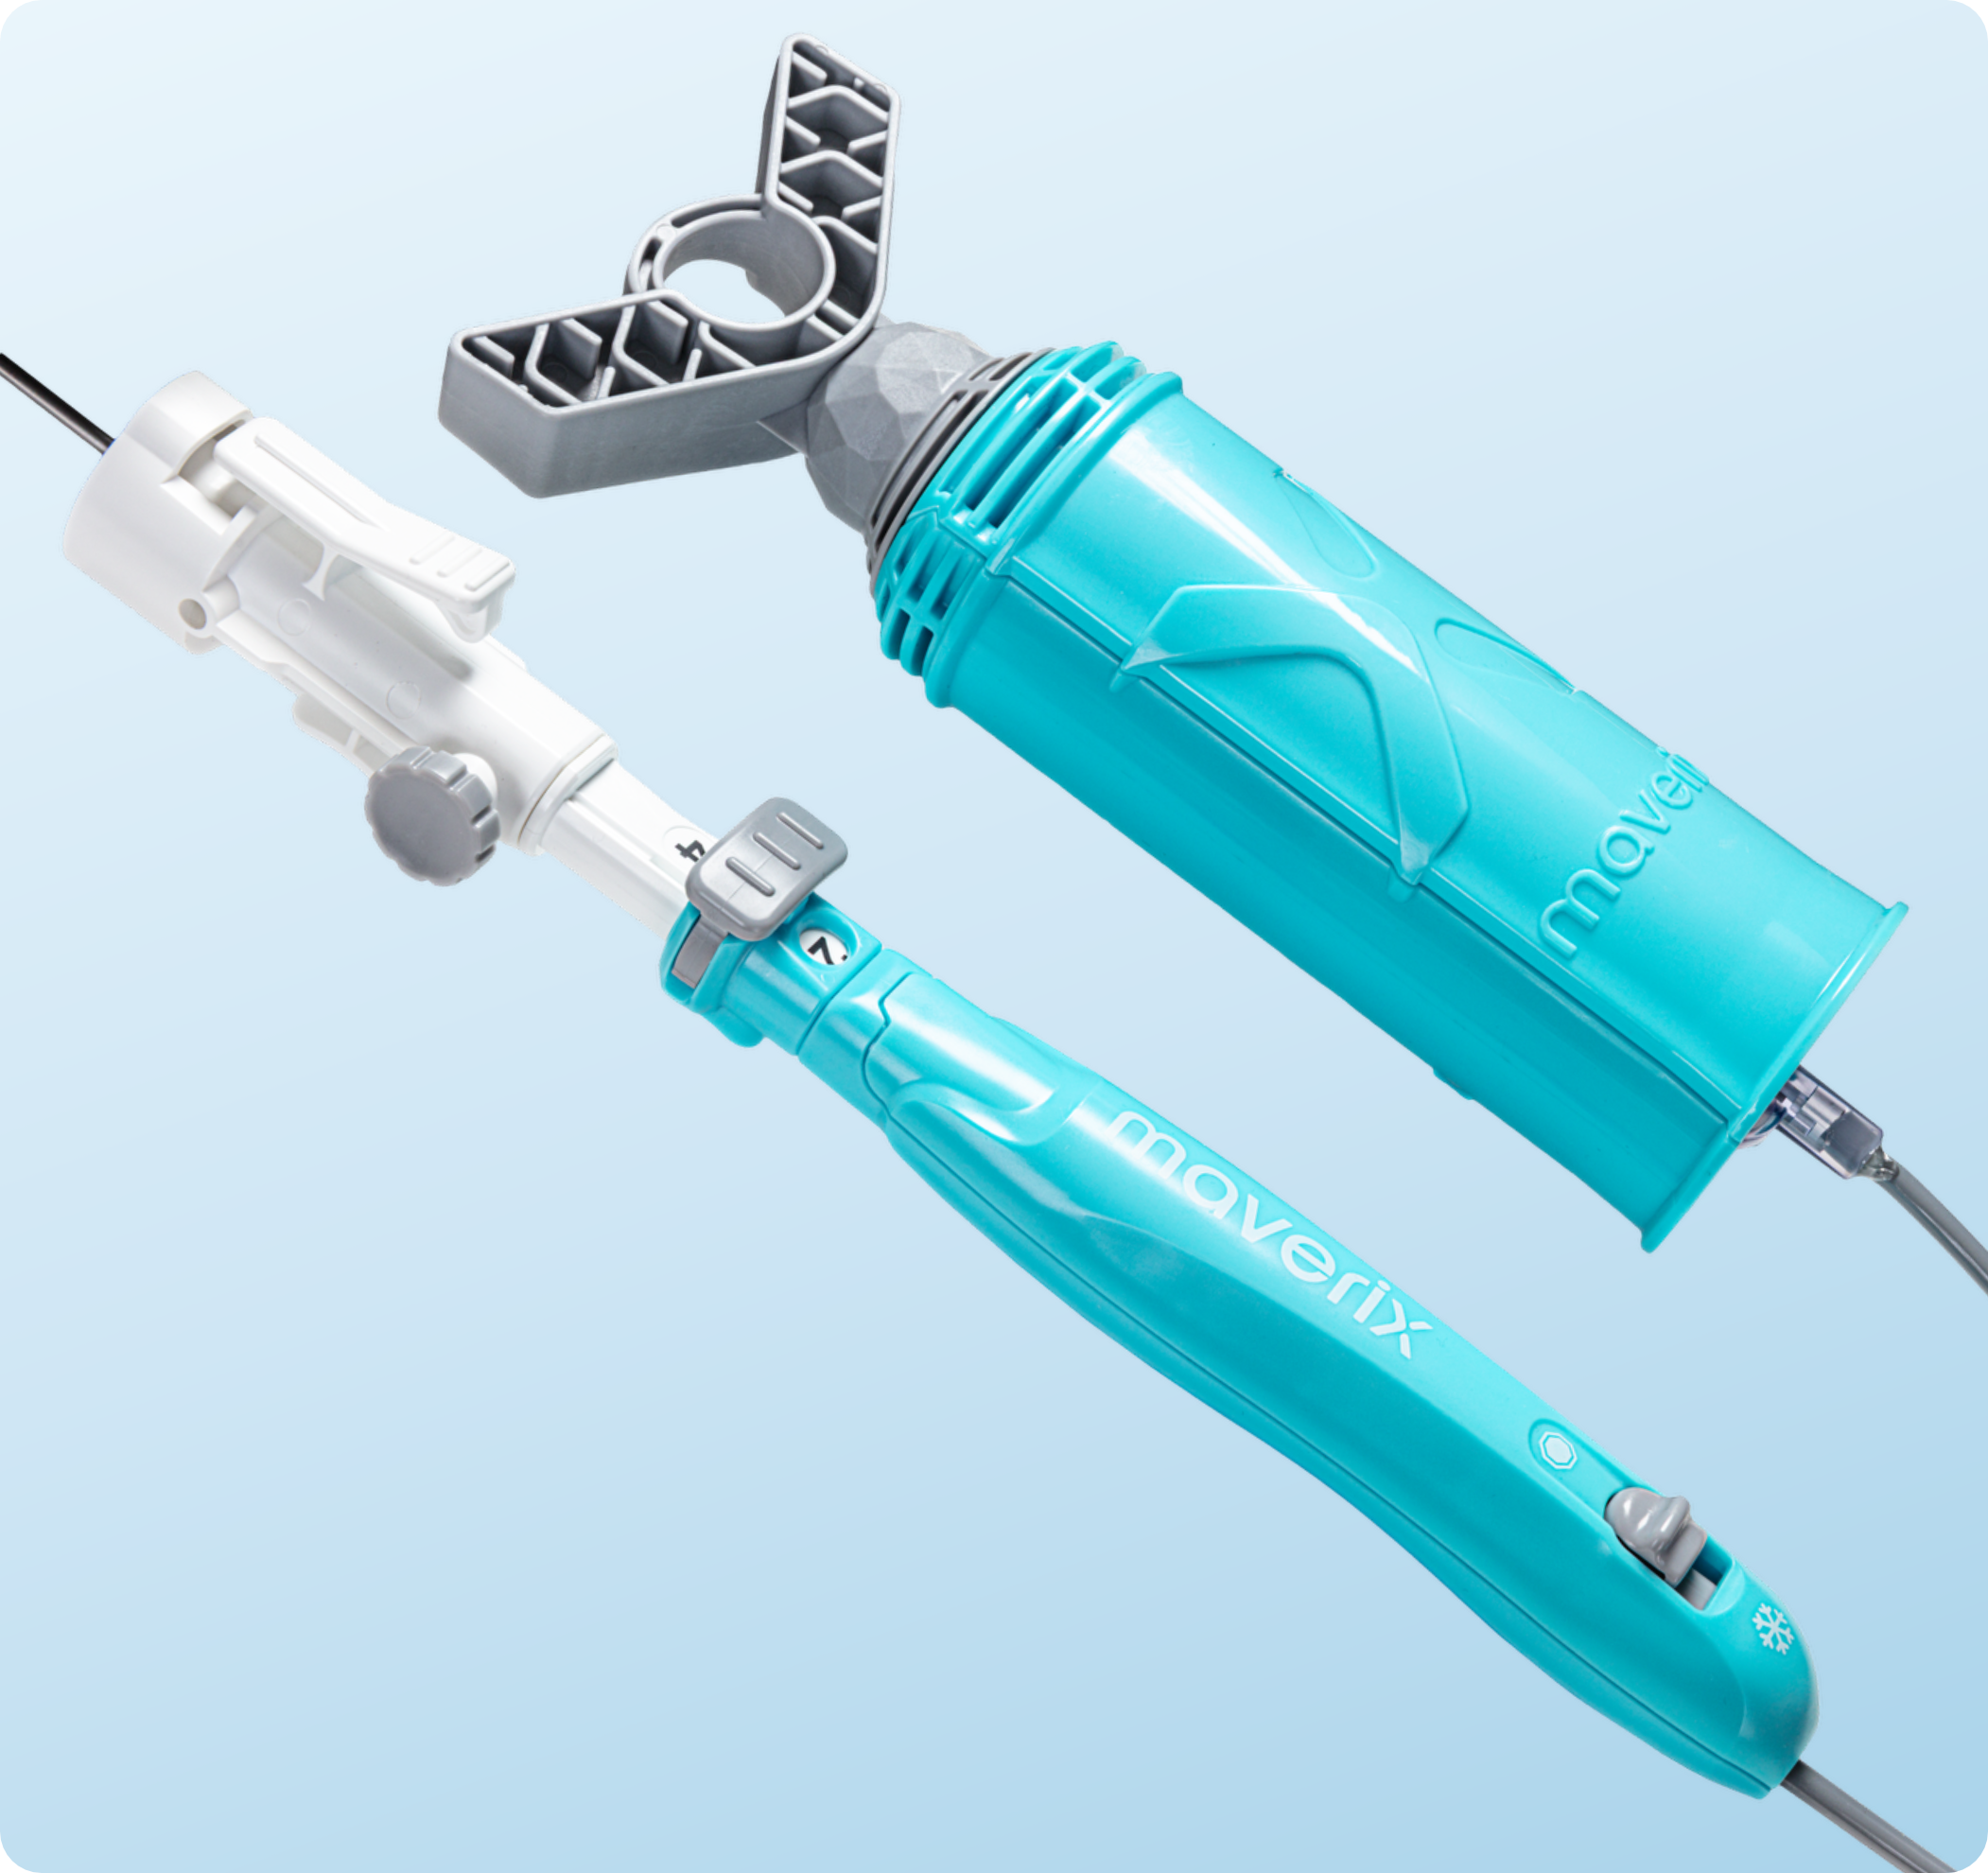
The FDA granted 510(k) clearance on September 2, 2026, to Maverix Medical’s Narwhal Pro Cryo System, its second console-free cryoprobe; the device is designed for bronchoscopes up to 600 mm and connects to Olympus, Fuji, and Pentax scopes using supplied adapters. Both Narwhal systems are expected to be broadly available in the U.S. in 2027, and the article cites a FROSTBITE-2 study showing a 10% increase in diagnostic yield with a 1.1 mm cryoprobe versus forceps transbronchial biopsy.
Analysis
The investable question is adoption, not clearance: the system removes a capital-equipment hurdle, but single-use economics still need to beat forceps and established console-based cryobiopsy on total cost per diagnostic case. If randomized evidence translates into routine practice, cryobiopsy could take share from forceps and increase demand for compatible bronchoscopy procedures; benefits to scope makers are less certain because the product is designed to work across several installed platforms rather than lock clinicians into one. The strongest near-term constraint is timing: commercial distribution is not expected until 2027, leaving a gap between regulatory validation and observable revenue. Thoracent distribution could accelerate reach, but its scale and hospital access are unverified. The trial result is more decision-relevant than the physician testimonial, which is disclosed as paid; key missing evidence includes safety, real-world diagnostic yield by indication, reimbursement, cartridge and probe pricing, and repeat-use adoption. Over 1–3 months, watch for launch, pricing, and hospital evaluations rather than assuming clearance is a sales catalyst. Over 6–18 months, success depends on procedure-level economics and clinician uptake; slow adoption or weak reimbursement would leave the product a niche option. No mapped public ticker offers a clean exposure, so there is no direct trade on the supplied identities. The contrarian risk is that investors overread the yield improvement as immediate commercial traction despite the delayed launch and unproven purchasing economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No direct position: the supplied company mapping contains no public ticker, and the article provides no basis to attribute the product economics to a listed company.
- Set a 2027 launch watch item rather than trading the clearance announcement. Reassess when pricing, U.S. distribution reach, initial placements, and cartridge/probe reorder data are available.
- For any future exposure to bronchoscopy or device names, require evidence that diagnostic-yield gains translate into procedure adoption without adverse safety signals or unfavorable hospital cost/reimbursement. Thesis weakens if launch slips materially, early uptake is limited, or real-world yield fails to replicate the trial result.
More News
- SK Hynix plunges 8% amid Asia tech rout as Fed rate hike fears, AI funding worries mount
- Why is Samsung Electronics stock plunging today?
- Why is Advantest stock plummeting today?
- Japan, U.S. reach first chip deal under $550 bln investment plan
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory