
Kearney Names Martin Denman as Chief Financial Officer
Source: PR Newswire
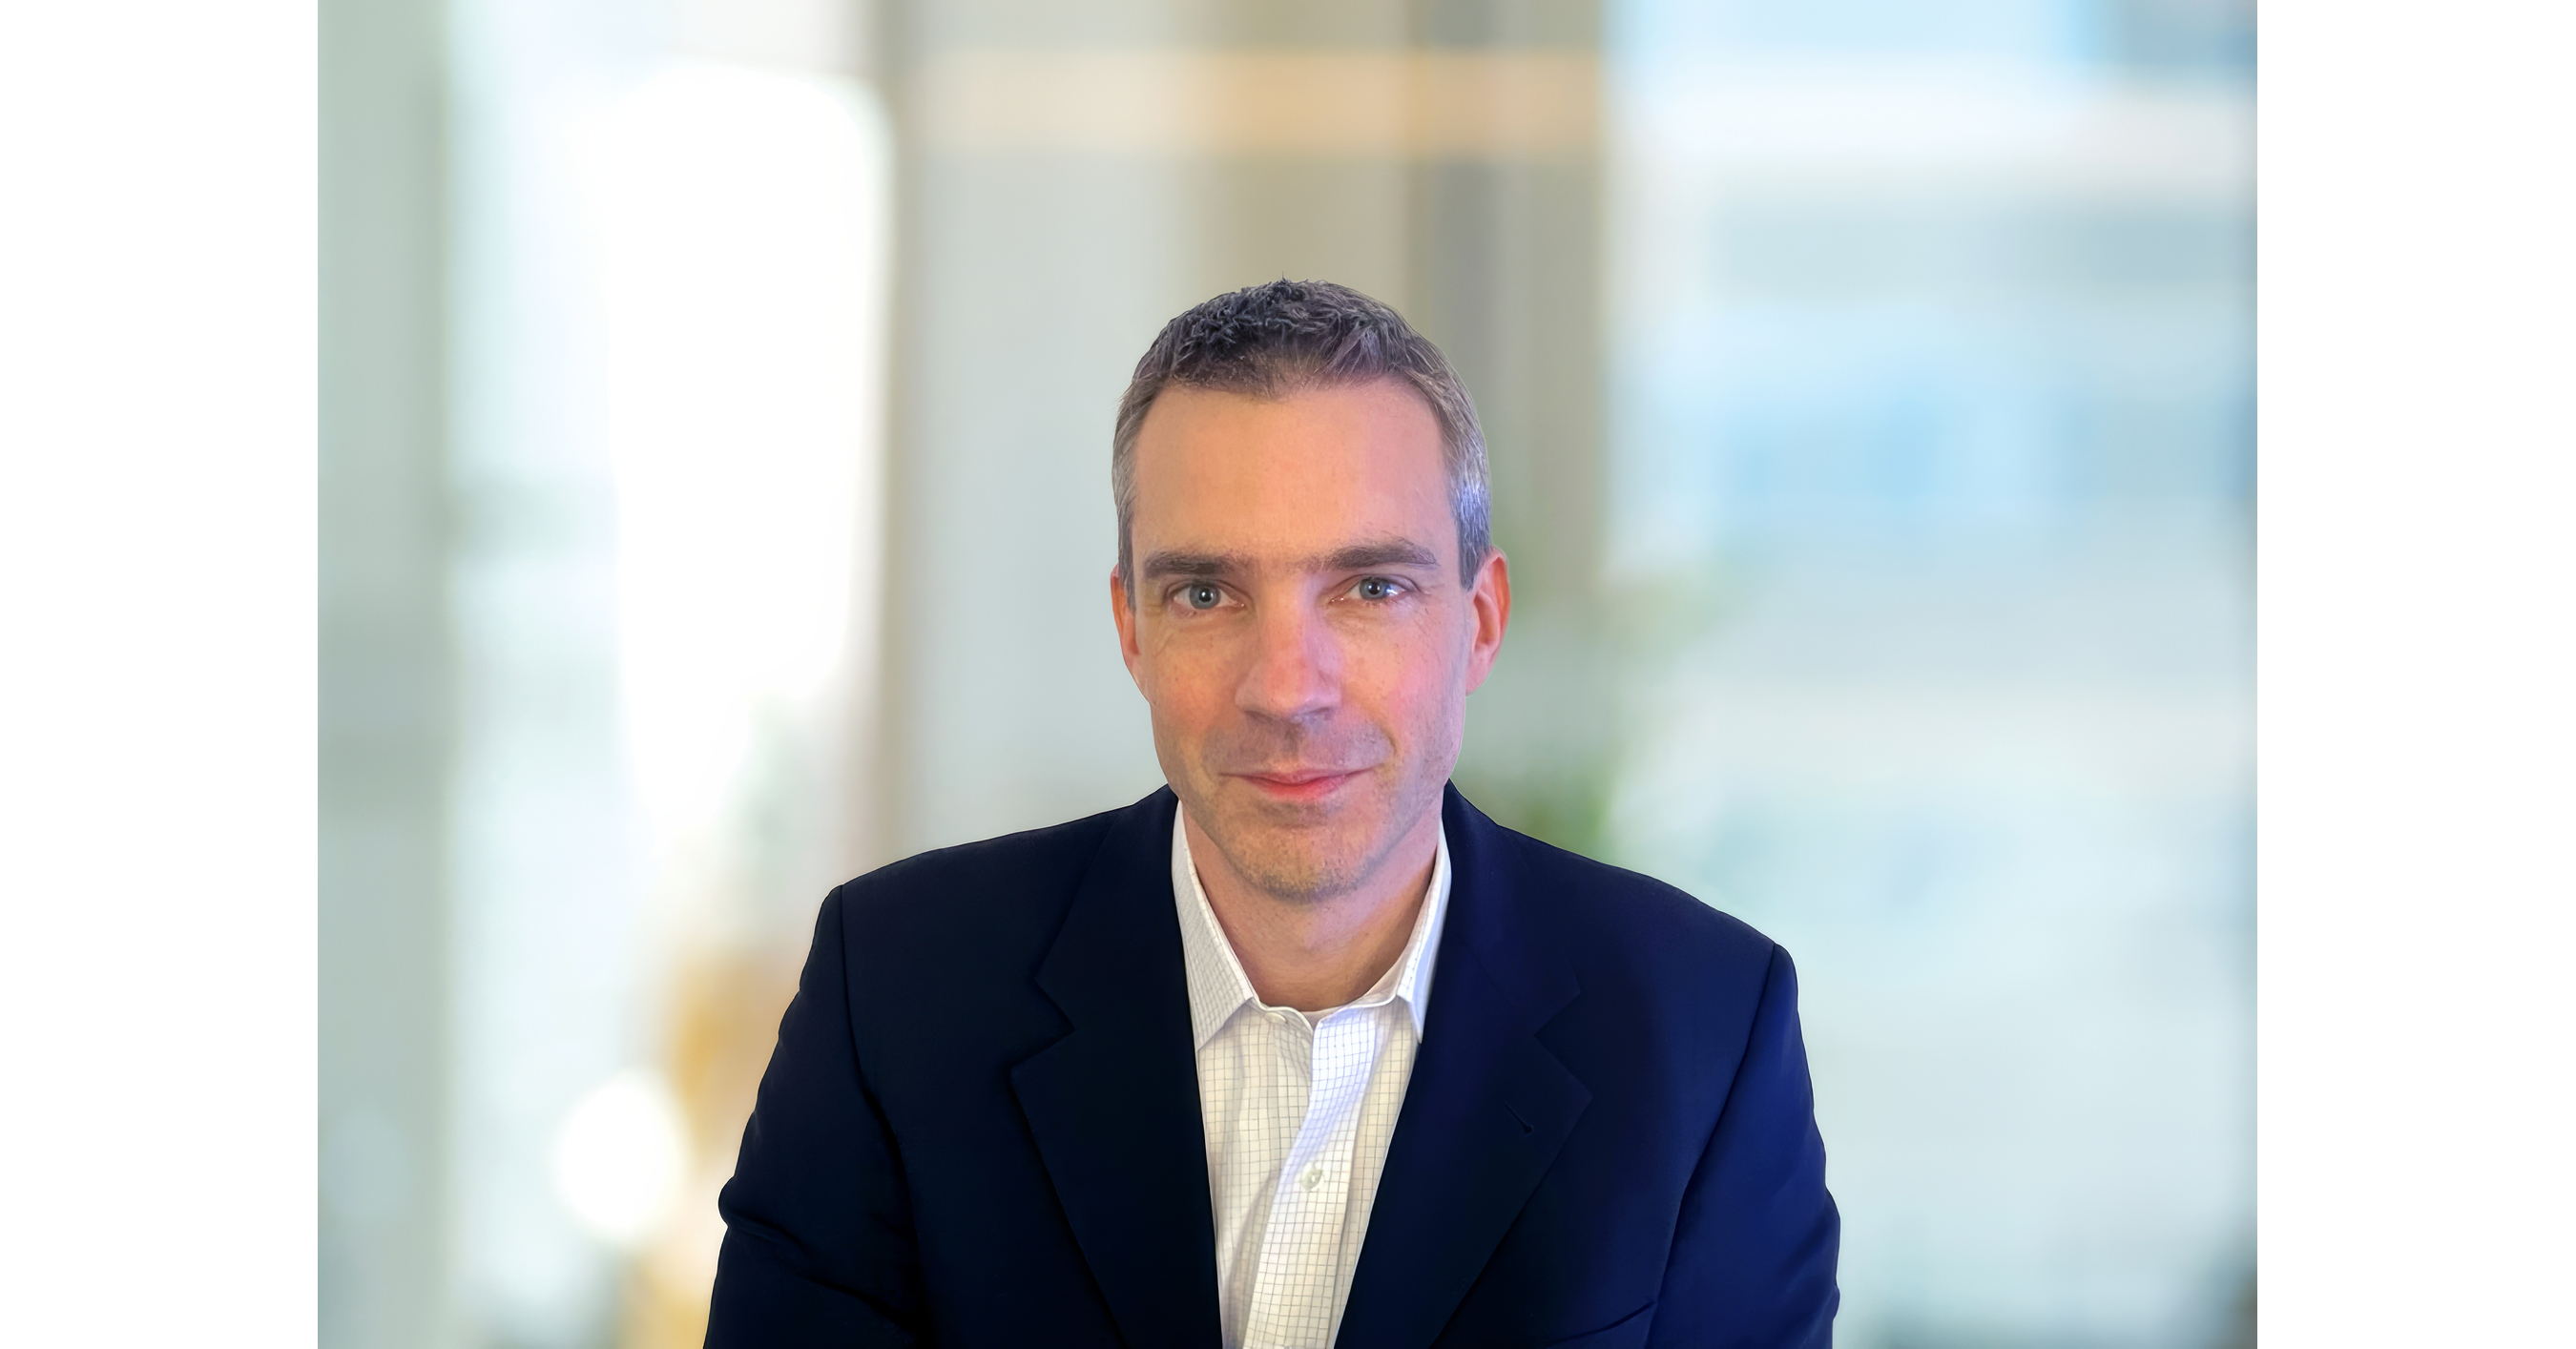
Kearney appointed Martin Denman as CFO after six months as acting CFO and nearly a decade in finance roles at the firm. Denman has led a finance transformation including a major technology-system upgrade, a global shared-services center, revised equity structure and integration of acquired companies. The appointment supports Kearney's stated investment in technology and new capabilities amid changing demand in management consulting.
Analysis
This is not a public-markets catalyst: Kearney is privately held, the appointment is internal, and there is no disclosed financial target, client contract, or transaction to underwrite. The relevant read-through is that large consultancies are prioritizing utilization, project-level margin measurement, shared-services leverage, and acquisition integration as AI compresses traditional advisory bill rates. Those initiatives can protect EBITDA, but they also signal a more competitive pricing environment for labor-intensive strategy and transformation work.
Near term, there is no actionable directional implication for listed consulting-adjacent names. Over 6-18 months, the sharper competitive risk is for firms with high exposure to discretionary strategy and technology-transformation spending—ACN, BAH, and CACI—if clients increasingly demand measurable ROI, fixed-fee structures, and faster delivery. Conversely, software vendors enabling project profitability, resource planning, and finance automation—ORCL, SAP, and NOW—retain a modest second-order benefit, although a single firm's systems upgrade does not alter their earnings outlook.
The contrarian point is that cost discipline at private consulting peers can be an early indicator of industry-wide margin defense rather than incremental demand. Watch ACN bookings, utilization, subcontractor expense, and pricing commentary over the next two earnings cycles; accelerating bookings alongside stable gross margin would invalidate the margin-compression concern, while weaker pricing or rising bench costs would make the read-through more material.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No new position on this announcement; treat it as a low-signal governance item rather than a tradable catalyst.
- Place an earnings watch on ACN over the next 1-3 months: consider a tactical short only if management reports slowing bookings or pricing pressure combined with rising utilization slack; cover if bookings reaccelerate and operating-margin guidance holds.
- For a broader AI-enabled consulting-efficiency theme, maintain ORCL/SAP/NOW on a 6-18 month watchlist, but require evidence of enterprise finance-automation backlog acceleration before initiating exposure.
- Monitor private-consulting industry signals for fixed-fee adoption and headcount reductions; confirmation across peers would favor an ACN underweight versus more government-contract-heavy BAH, whose demand base is less tied to discretionary corporate transformation budgets.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Ukraine says Starlink and Starshield high speed restrictions have been lifted
- Goldman says these top tech stocks have plenty of upside ahead of earnings