
"THE SPONGEBOB MUSICAL" HEADS TO SEA FOR THE FIRST TIME ON ROYAL CARIBBEAN'S HERO OF THE SEAS
Source: PR Newswire
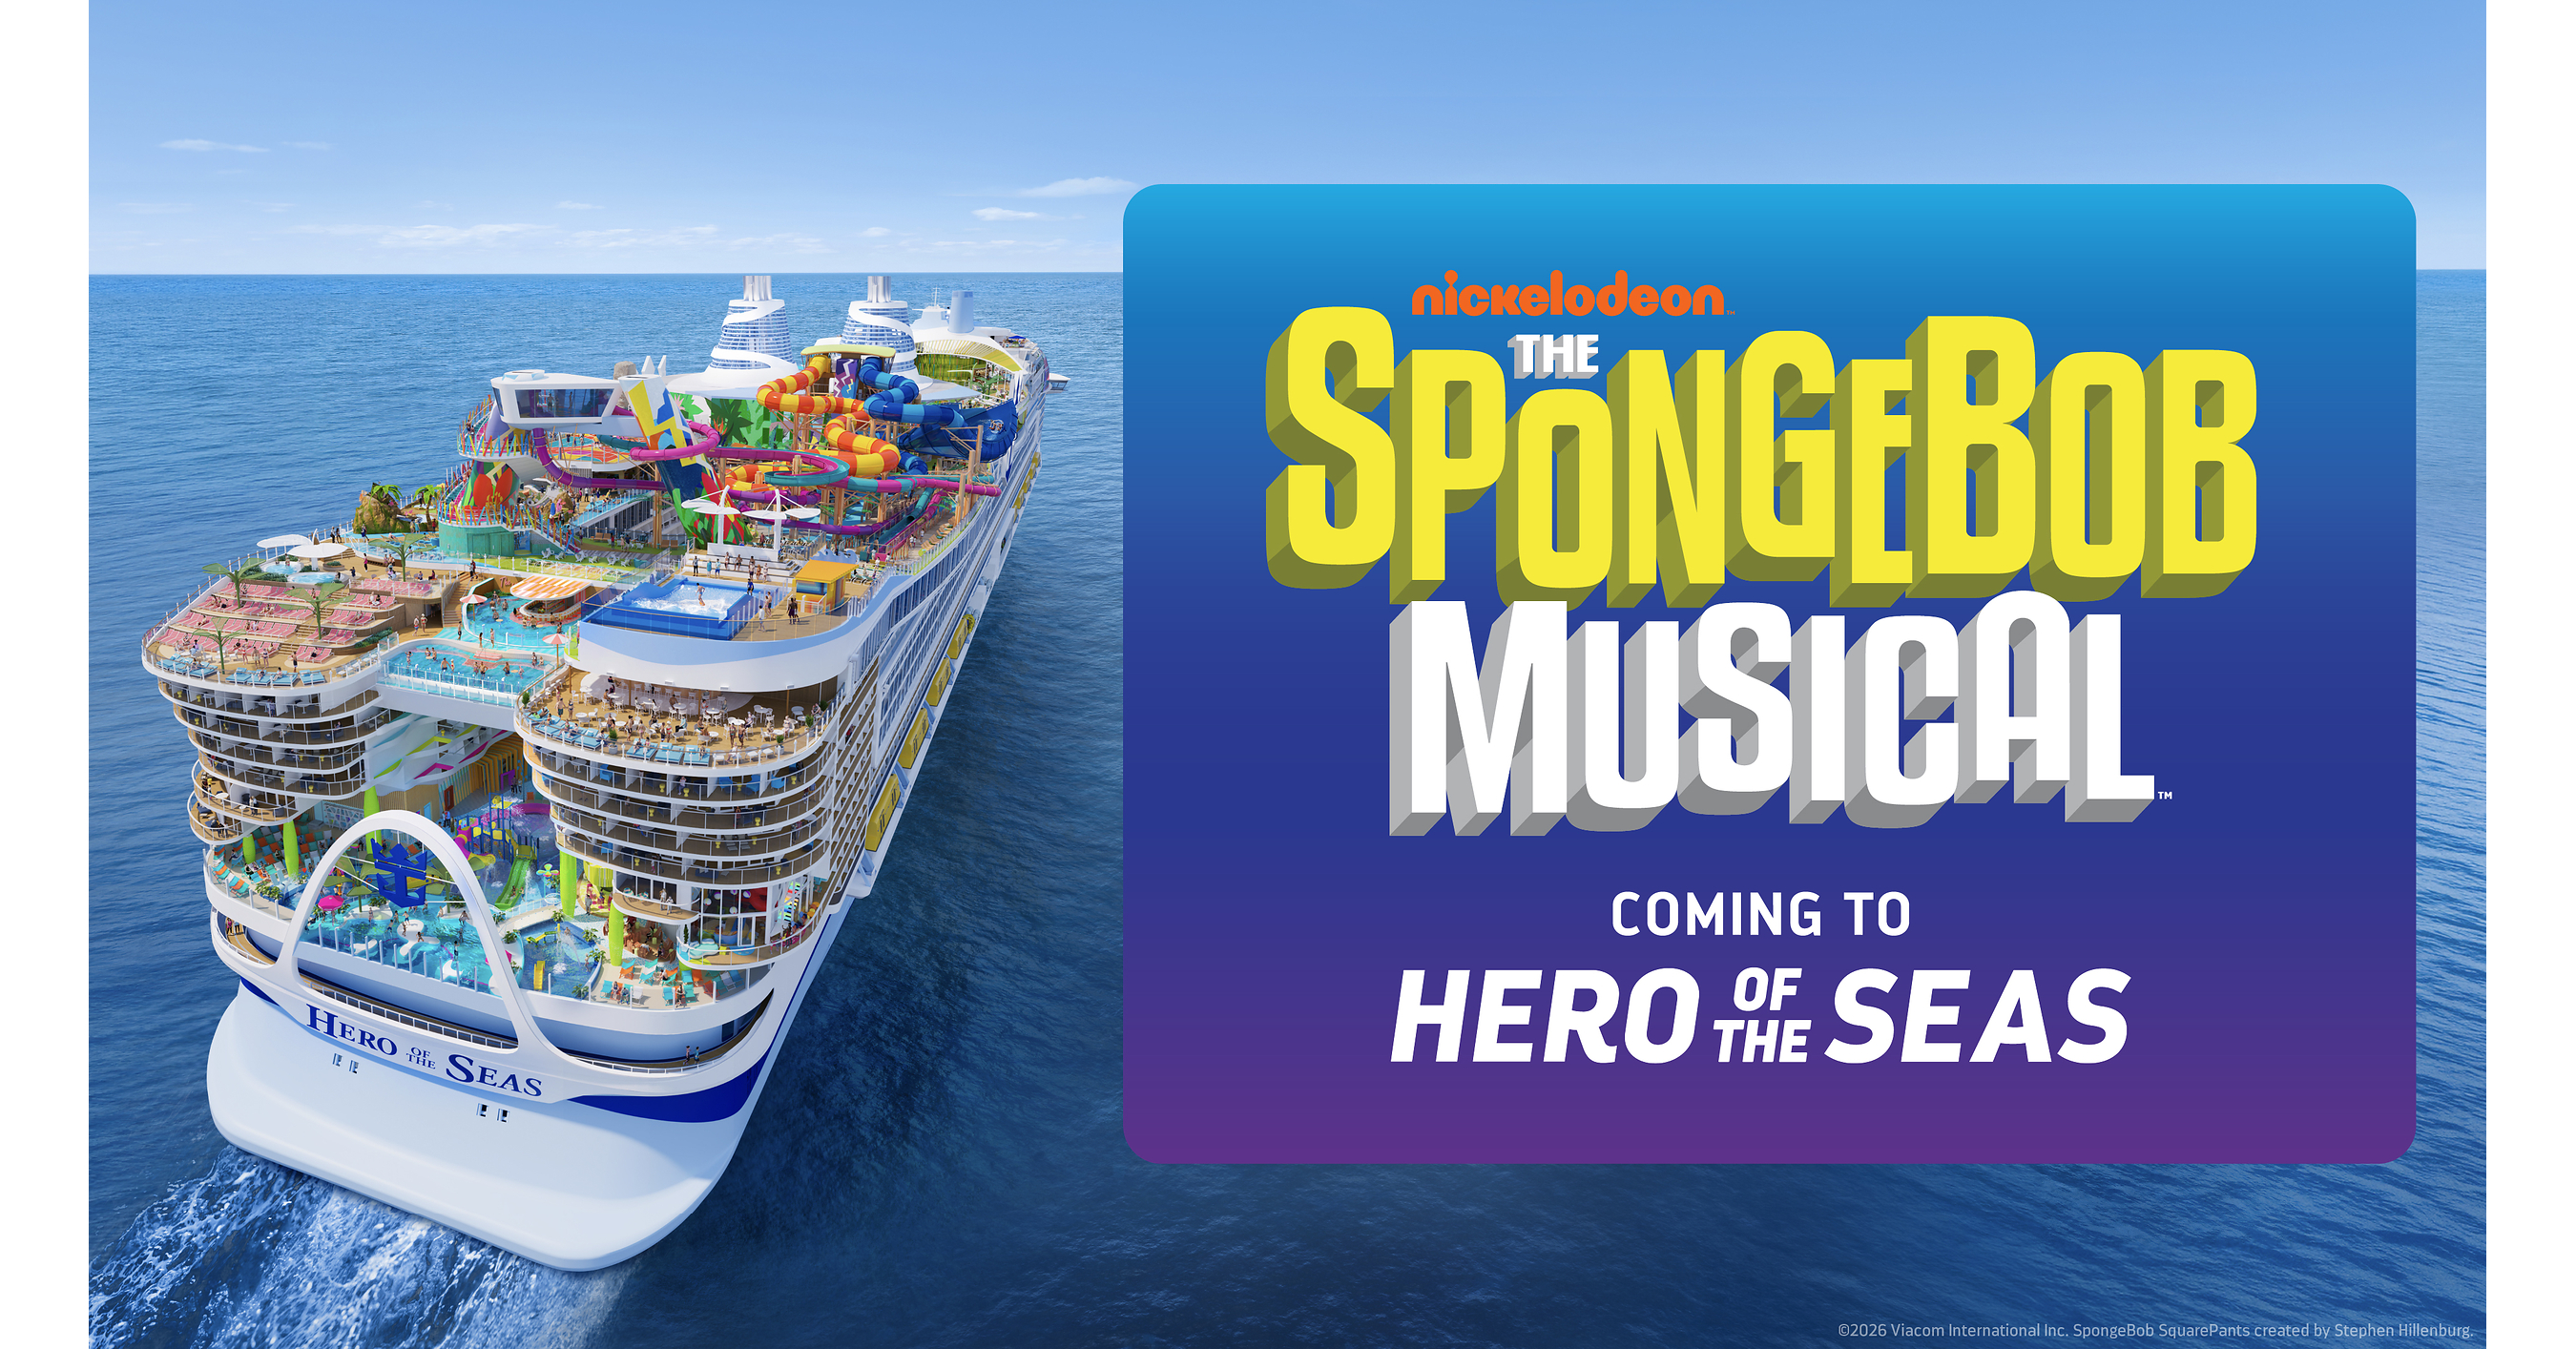
Royal Caribbean will debut "The SpongeBob Musical" aboard Hero of the Seas, its fourth Icon Class ship, when the vessel begins 7-night Caribbean sailings from Miami in August 2027. The exclusive production is part of a broader family-entertainment offering featuring eight neighborhoods, 28 dining venues, nine pools and Category 6, billed as the largest waterpark at sea. The announcement supports Royal Caribbean's product differentiation and family-vacation positioning, though it provides no booking, revenue or guidance figures.
Analysis
This is strategically more relevant to RCL's premiumization and family-share capture than to near-term earnings. A recognizable children’s franchise can improve booking conversion and reduce marketing cost per acquired family guest, but the economic value depends on whether Hero commands a sustained net-yield premium versus the existing Icon fleet rather than simply cannibalizing demand from other Royal Caribbean ships. The first meaningful read-through is likely booking velocity and price realization during the 2027 wave season, not this announcement.
PSKY receives a low-capital, high-margin licensing proof point, but one vessel is immaterial to consolidated financials. The more valuable second-order signal would be whether this becomes a multi-ship or broader location-based-experience rollout; that would validate SpongeBob as an evergreen experiential IP and improve the market’s confidence in consumer-products growth independent of linear-TV economics. Until royalty structure, merchandising participation, and expansion rights are disclosed, the financial uplift is not independently verifiable.
The key risk to RCL is that Icon-class amenity intensity raises fixed operating and maintenance costs just as the 2027 delivery enters a potentially softer consumer environment. If family discretionary spending weakens, the ship’s high headline price can require discounting that erodes yield and offsets any occupancy benefit; competing family products from CCL and NCLH can also respond through promotions rather than comparable capex. Conversely, strong early deposits could support a higher long-term multiple by demonstrating that RCL’s differentiated hardware-plus-IP model is widening its yield gap.
Contrarian view: the market should not capitalize this as a franchise-driven earnings event. The relevant investable thesis remains RCL’s ability to monetize constrained new-berth supply through pricing; this entertainment addition is a small data point, not a change in that thesis. A material positive reassessment requires disclosed booking premiums, onboard-spend uplift, or evidence that the concept transfers across the fleet.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No incremental directional position solely on the announcement; treat as a watch item for RCL’s 2027 booking launch. Add to an existing RCL long only if initial sailings show a durable net-yield premium versus comparable Icon itineraries without elevated promotional intensity.
- Monitor RCL quarterly commentary over the next 6-12 months for 2027 deposit cadence, onboard revenue per passenger cruise day, and incremental marketing spend. Thesis is weakened if management signals discounting or if net yields lag despite strong load factors.
- For PSKY, maintain a catalyst watch rather than initiate: a fleetwide licensing extension, disclosed minimum guarantees, or merchandising rights would be the trigger for reassessing consumer-products estimates. Absent those disclosures, the contribution is too small to underwrite.
- If RCL materially outperforms on pre-launch enthusiasm without supporting yield data, consider a tactical RCL versus CCL pair short over a 1-3 month horizon; the risk is that RCL’s broader fleet pricing and balance-sheet deleveraging continue to justify the premium independently of Hero.
More News
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- David Ellison says combined Paramount and Warner Bros. Discovery will be named Skydance
- Paramount and Warner Bros Discovery to become Skydance
- Paramount’s Warner Bros. megamerger will just be called Skydance
- David Ellison goes minimalist with his new name for his Paramount-Skydance-Warner-Bros-Discovery empire
- Paramount-WBD Will Now Be Called Skydance, David Ellison Reveals