
evolve and ELITEWHEELS Bring Engineering-Driven Cycling Performance to Italian Bike Festival 2026
Source: PR Newswire
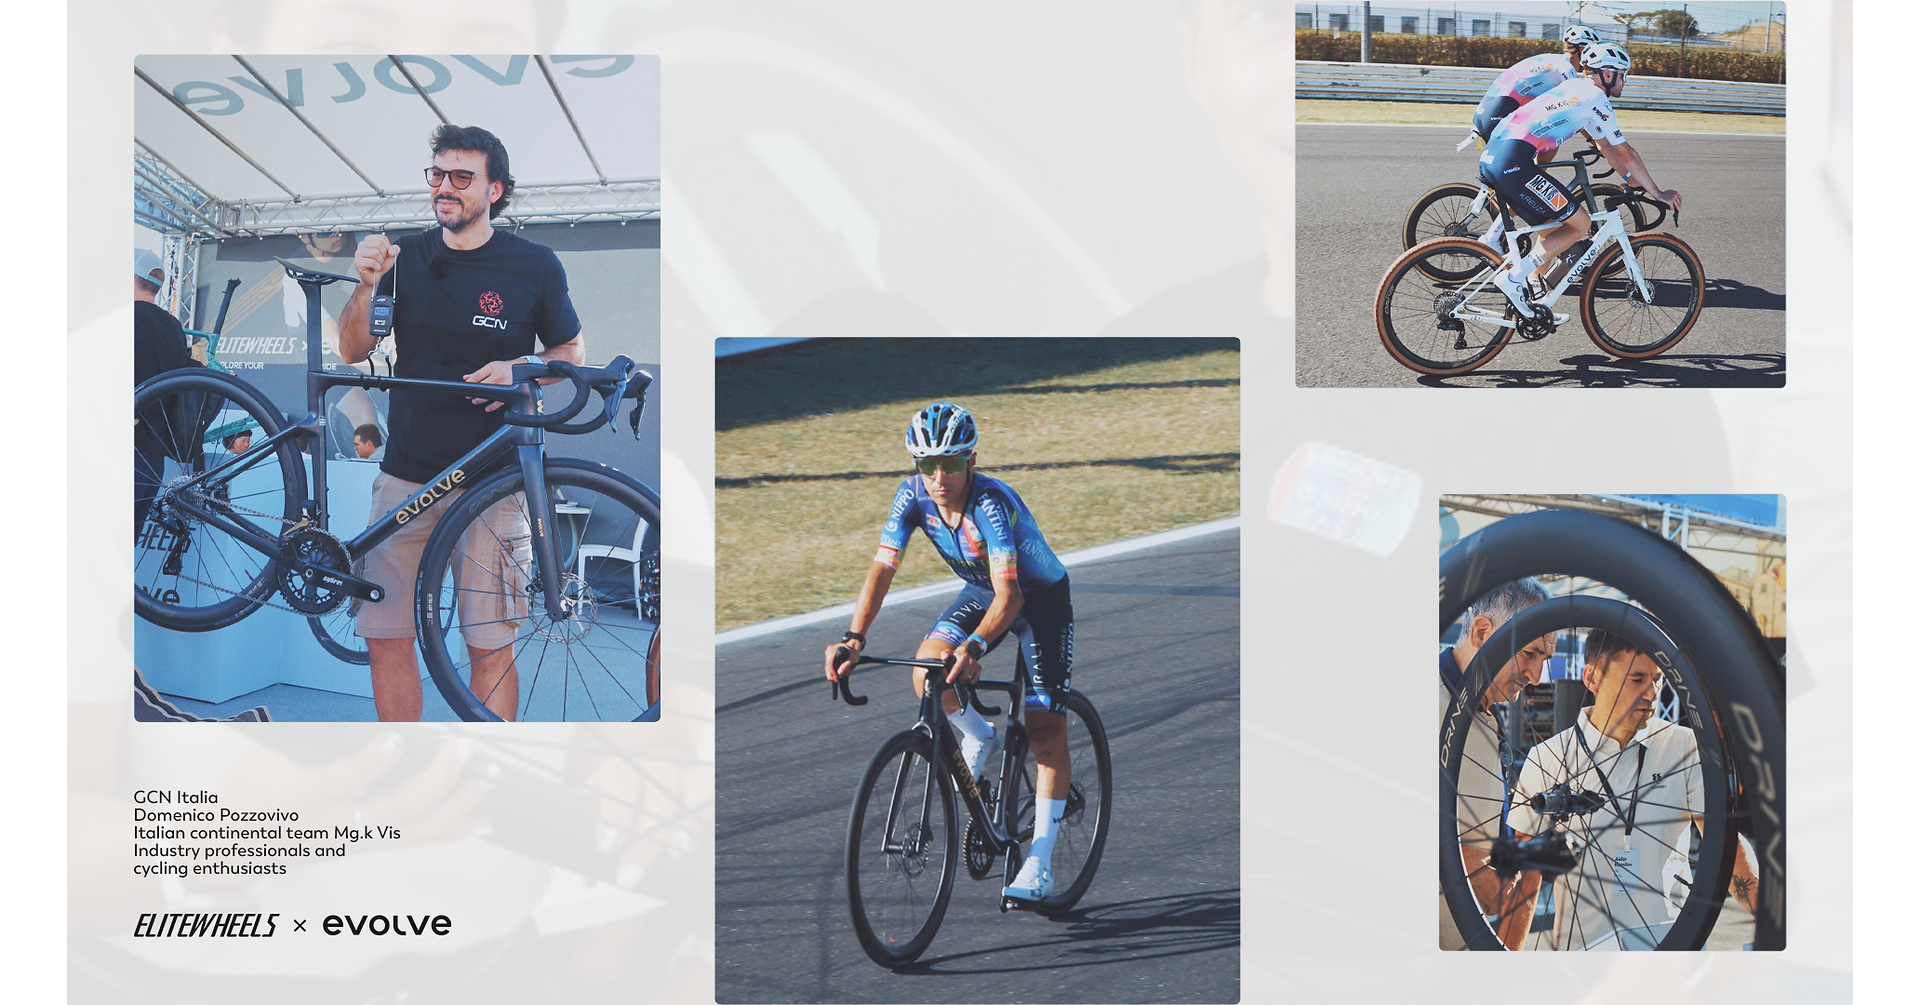
evolve and ELITEWHEELS are showcasing new engineering-driven cycling developments at IBF 2026 in Misano (Sept. 4–6), including evolve’s data-driven performance focus (weight, stiffness, aerodynamics) across its CIMA road and CIMA GR gravel platforms and ELITEWHEELS’ lightweight, aerodynamic carbon wheel systems. The brands are also hosting discussions with sponsored UCI riders and offering test rides, alongside expanding European market support via distribution partnerships and team collaborations. Overall, the article is promotional with no financials or guidance, suggesting minimal near-term market impact.
Analysis
This reads less like a revenue event and more like a credibility-building step in a category where trust and dealer endorsement matter more than one-off marketing. The real economic mechanism is margin defense: if lower-priced carbon-wheel brands can use pro validation and local distribution to move upmarket, they can pressure the gross-margin pool of incumbents that have historically monetized brand and warranty confidence. That pressure is likely gradual, showing up first in dealer assortment decisions and promo intensity rather than in any immediate shipment spike.
The second-order effect is on channel economics. Specialty bike retail is a small-surface-area market: every new brand that earns shelf space forces someone else to either cut price, increase co-op spend, or lean harder on OEM relationships. That tends to favor faster-moving direct-to-consumer players and punish legacy premium labels that depend on ASP stability; public-market read-through is indirect but important for any listed bike-adjacent manufacturer with exposure to accessory attach and aftermarket mix.
Near term, the catalyst path is all about whether this translates into reorder velocity over the next 1-3 months, not booth traffic. Over 6-18 months, the structural question is whether reliability claims hold up in field use; if warranty claims stay low, the low-cost/high-performance segment can continue taking share. The thesis is falsified if European dealers don’t expand assortment, if discounting widens, or if product issues force recalls/returns that erase the credibility premium.
Contrarian view: the market often overweights professional-rider validation and underweights service quality. In this niche, the winning product is not the most aerodynamic one but the one that survives hard use without support headaches; that means the long-term moat may be narrower than the marketing suggests. For now, this is more of a watch item than a stock-moving catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.08
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in TBHC; treat this as non-actionable until there is disclosed revenue, distribution, or customer-concentration data tied to the cycling business.
- Set a 60-90 day alert on European dealer/reorder checks for premium cycling components; if discounting appears, consider a short in FOXF on any strength, with the trade thesis invalidated if bike-segment margins and channel inventory remain stable.
- Watch 7309.T (Shimano) as the closest listed proxy for premium drivetrain pricing power; stay flat unless industry checks show meaningful ASP erosion, which would justify a relative short versus the broader consumer discretionary basket.
- If channel checks confirm sustained share gains for lower-cost performance wheel brands, build a basket short of legacy premium cycling suppliers versus the most price-sensitive segment; use widening promo spend or dealer pushback as the trigger, not brand publicity.
More News
- 'Cannot play hide and seek': Singapore minister's warning over haze sends agricultural stocks lower
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Elice shares plunge 28% on debut as investor doubts over AI trade deepen