
American Bitcoin Reports Third Quarter 2026 Results
Source: PR Newswire
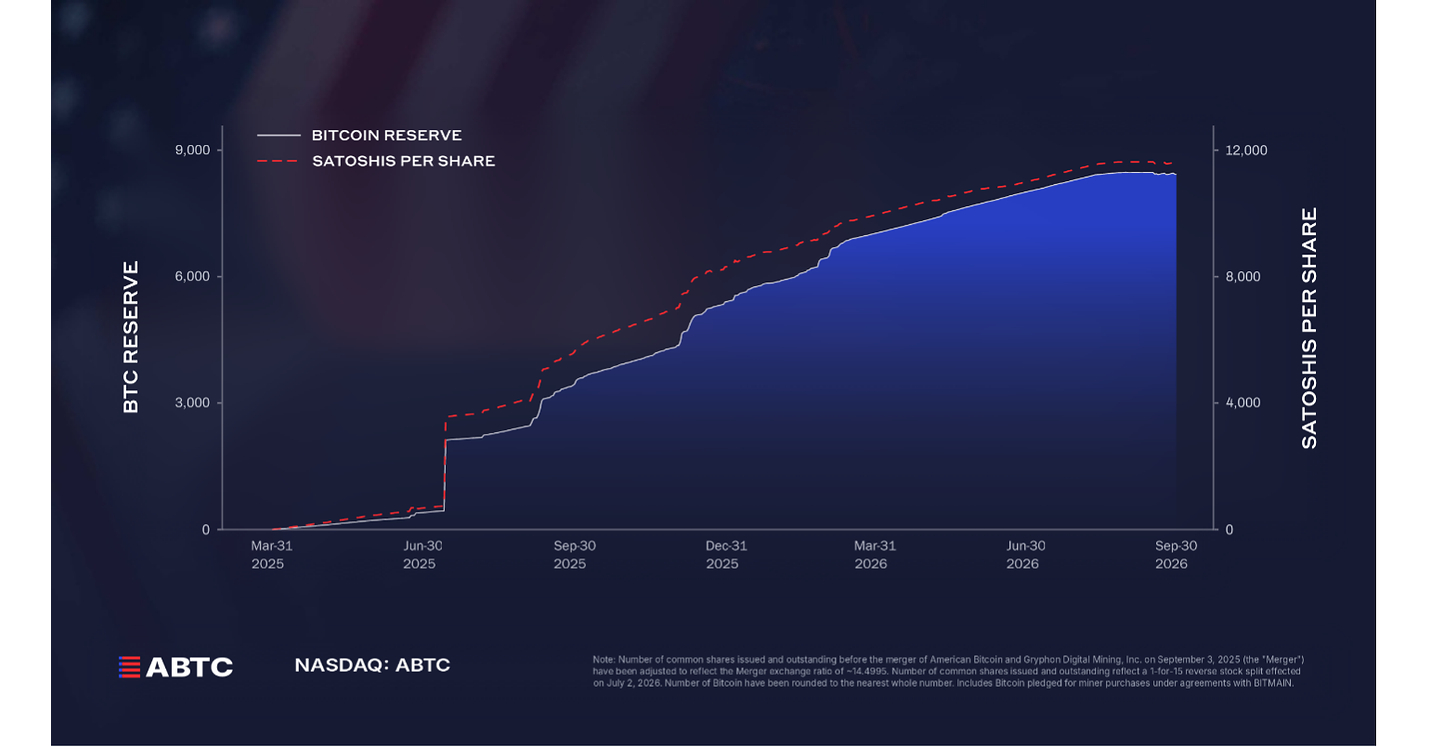
American Bitcoin reported Q3 2026 net income of approximately $126 million and Adjusted EBITDA of $221 million, versus a $57.2 million net loss and $45.0 million Adjusted EBITDA loss in Q2. Bitcoin holdings rose by approximately 425 BTC, or 5%, to about 8,427 BTC, while Satoshis Per Share increased approximately 5% without ATM share issuance or Bitcoin purchases. Mining revenue fell to $63.4 million from $67.0 million, and gross margin declined to about 41% from 49% as seasonal power costs lifted cost per Bitcoin mined to $42,100 from $36,500.
Analysis
Read-through: The headline metric is less durable than it appears. American Bitcoin’s reported profit was dominated by a large gain on digital assets, partly offset by derivative losses; neither GAAP net income nor the company-defined Adjusted EBITDA is a clean proxy for recurring mining cash generation. Operating leverage is moving the wrong way at the margin: higher power costs coincided with lower production and a sharp gross-margin decline. The claimed discount to spot therefore needs to be tested against power, depreciation, miner financing and other cash costs—not just the stated cost per coin.
The more important second-order issue for HUT is attribution. American Bitcoin is described as a majority-owned subsidiary of Hut 8, but its standalone results do not establish HUT’s attributable economics, cash available to the parent, or consolidated leverage. Verify HUT’s reporting treatment and ownership share before treating ABTC’s earnings or Bitcoin-per-share growth as HUT value creation. Further, a material portion of ABTC’s reported Bitcoin holdings is pledged under miner-purchase agreements: reserve growth is not equivalent to unencumbered liquidity.
Horizon and contrarian view: Today’s release may support Bitcoin-miner sentiment, but the 1–3 month test is whether unit margins recover as seasonal power pressure eases without sacrificing production or reserve growth. Over 6–18 months, halving/network difficulty, power availability and funding needs can outweigh Bitcoin accumulation. Consensus may overvalue SPS as a shareholder-return measure; it can rise while capital intensity and downside exposure also rise. This thesis weakens if subsequent filings show improving cash margins, lower encumbrance and durable per-share growth. No valuation or HUT-specific earnings attribution is provided here, so the release alone is not a strong directional HUT signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Do not chase HUT on ABTC’s headline net income. Before changing HUT exposure, verify in HUT’s filings the subsidiary ownership economics, consolidation treatment, cash flows attributable to the parent, and obligations linked to pledged Bitcoin and miner purchases.
- For the next 1–3 months, track ABTC’s cost per Bitcoin against realized mining revenue, production, gross margin and unencumbered Bitcoin holdings. A sustained margin recovery alongside reserve growth would improve the operating thesis; further margin compression or reserve growth reliant on encumbered assets would falsify it.
- For portfolios seeking Bitcoin exposure, prefer spot exposure over adding HUT solely on this release until the parent-level look-through is clear. Keep any miner exposure sized for operational and financing risk; the release does not establish a compelling standalone HUT long or short.
More News
- Hut 8 Reports Third Quarter 2026 Results
- NextDC shares surge 43% after Goodman, Digital Realty stake purchases
- Asian chip stocks slide as disappointing Qualcomm, Arm earnings weigh
- Oil and data centre stocks sink after US midterms
- Snap shares fall over 10% on third-quarter earnings miss
- After the midterms, a bigger clash over data centers could be coming