
Century Complete Now Selling New Homes from the Mid $200s at Shockley Bend in Anderson, SC
Source: PR Newswire
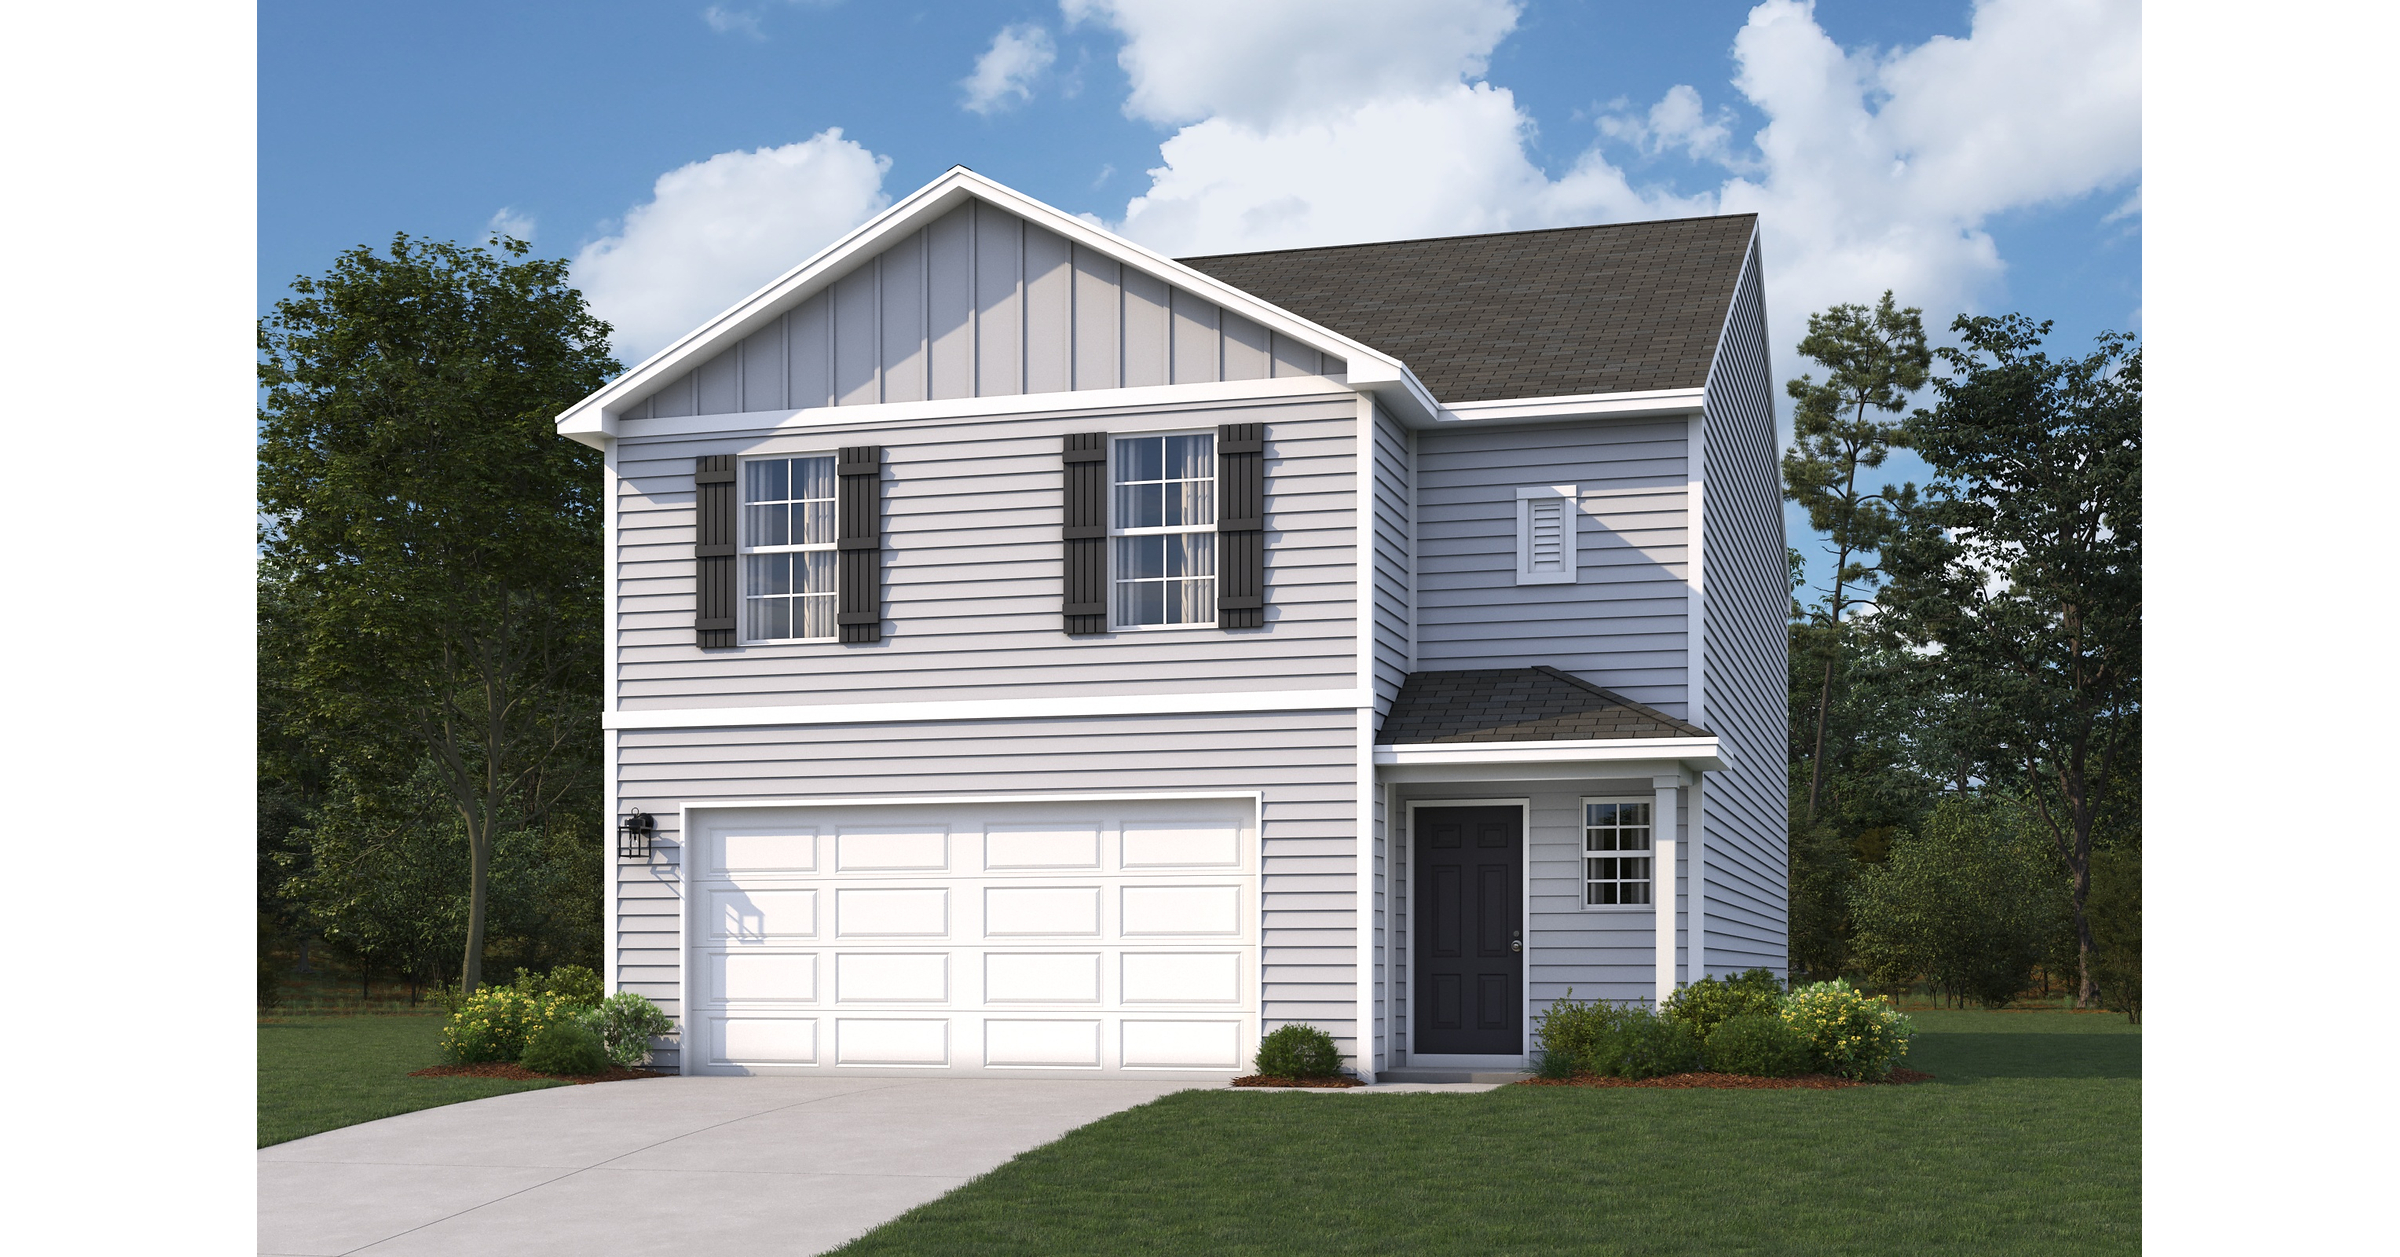
Century Communities' Century Complete brand began sales at Shockley Bend in Anderson, South Carolina, offering three single-family two-story plans priced from the mid-$200,000s. Homes range from 1,566 to 1,965 square feet with three to four bedrooms, and can be purchased through the company's online transaction platform. The community expands Century Complete's Upstate South Carolina offering but provides no sales-volume, margin, or financial-guidance update.
Analysis
This is not independently material to CCS earnings; the investable signal is whether the entry-level product can clear at advertised pricing without mortgage-rate buydowns that dilute gross margin. A small community launch should be treated as a local demand read-through, not evidence of national order acceleration. The relevant 1-3 month catalyst is CCS's next orders, cancellation, incentive, and gross-margin commentary for Southeast markets; conversion through its captive mortgage channel can support attach-rate economics but also exposes margins to rate-lock costs if rates rise.
Competitive pressure is most acute for entry-level builders with Carolinas exposure, including LGIH and D.R. Horton (DHI), where resale affordability and buyer payment sensitivity determine whether price points translate into absorptions. If incentives prove necessary, lower-priced production builders may preserve volume at the expense of gross margin, while land-light peers with less flexibility on price could lose share. Suppliers cited in the release are too diversified for a meaningful revenue implication; DOCU is likewise immaterial because digital contracting is a workflow feature rather than an incremental demand driver.
Contrarian view: the market may over-credit online sales as a structural margin advantage. Digital reservation lowers friction, but it does not solve underwriting, appraisal, or monthly-payment constraints; its practical value is faster conversion of already-qualified buyers. No standalone trade is warranted from this announcement absent evidence that Southeast absorptions improve while incentives remain stable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Maintain neutral CCS into the next earnings release; upgrade only if Southeast net orders per community rise sequentially while gross-margin guidance holds or improves. Falsifier: increased sales incentives or a downward gross-margin revision despite higher unit volume.
- Create a CCS versus LGIH (LGIH) relative-value watchlist for the next 1-3 months: go long CCS/short LGIH only if CCS demonstrates superior entry-level absorption without incremental buydowns. Target a 10-15% relative move; exit if LGIH reports better incentive-adjusted orders or CCS cancellations rise.
- Monitor DHI and LEN quarterly commentary for Carolinas incentive intensity and resale competition; broad-based payment stress would favor avoiding entry-level-builder beta rather than owning CCS on this local launch.
- No position in DOCU or LG based on this item; require disclosed contract-volume or appliance-order data before attributing any revenue impact.
More News
- Software value analysis: data analytics, infrastructure, and SaaS compared
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Karin Rådström is steering Daimler Truck in a new direction as the world’s biggest truckmaker faces a growing challenge from China
- China’s slower loan growth is the new normal, central bank governor says
- Americans' incomes rose and poverty fell in 2025, Census Bureau says
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes