
Skupina NOVVA získala od společnosti ABO Energy významné portfolio obnovitelných zdrojů energie o výkonu 3,17 GW, které bude napájet globální infrastrukturu umělé inteligence
Source: PR Newswire
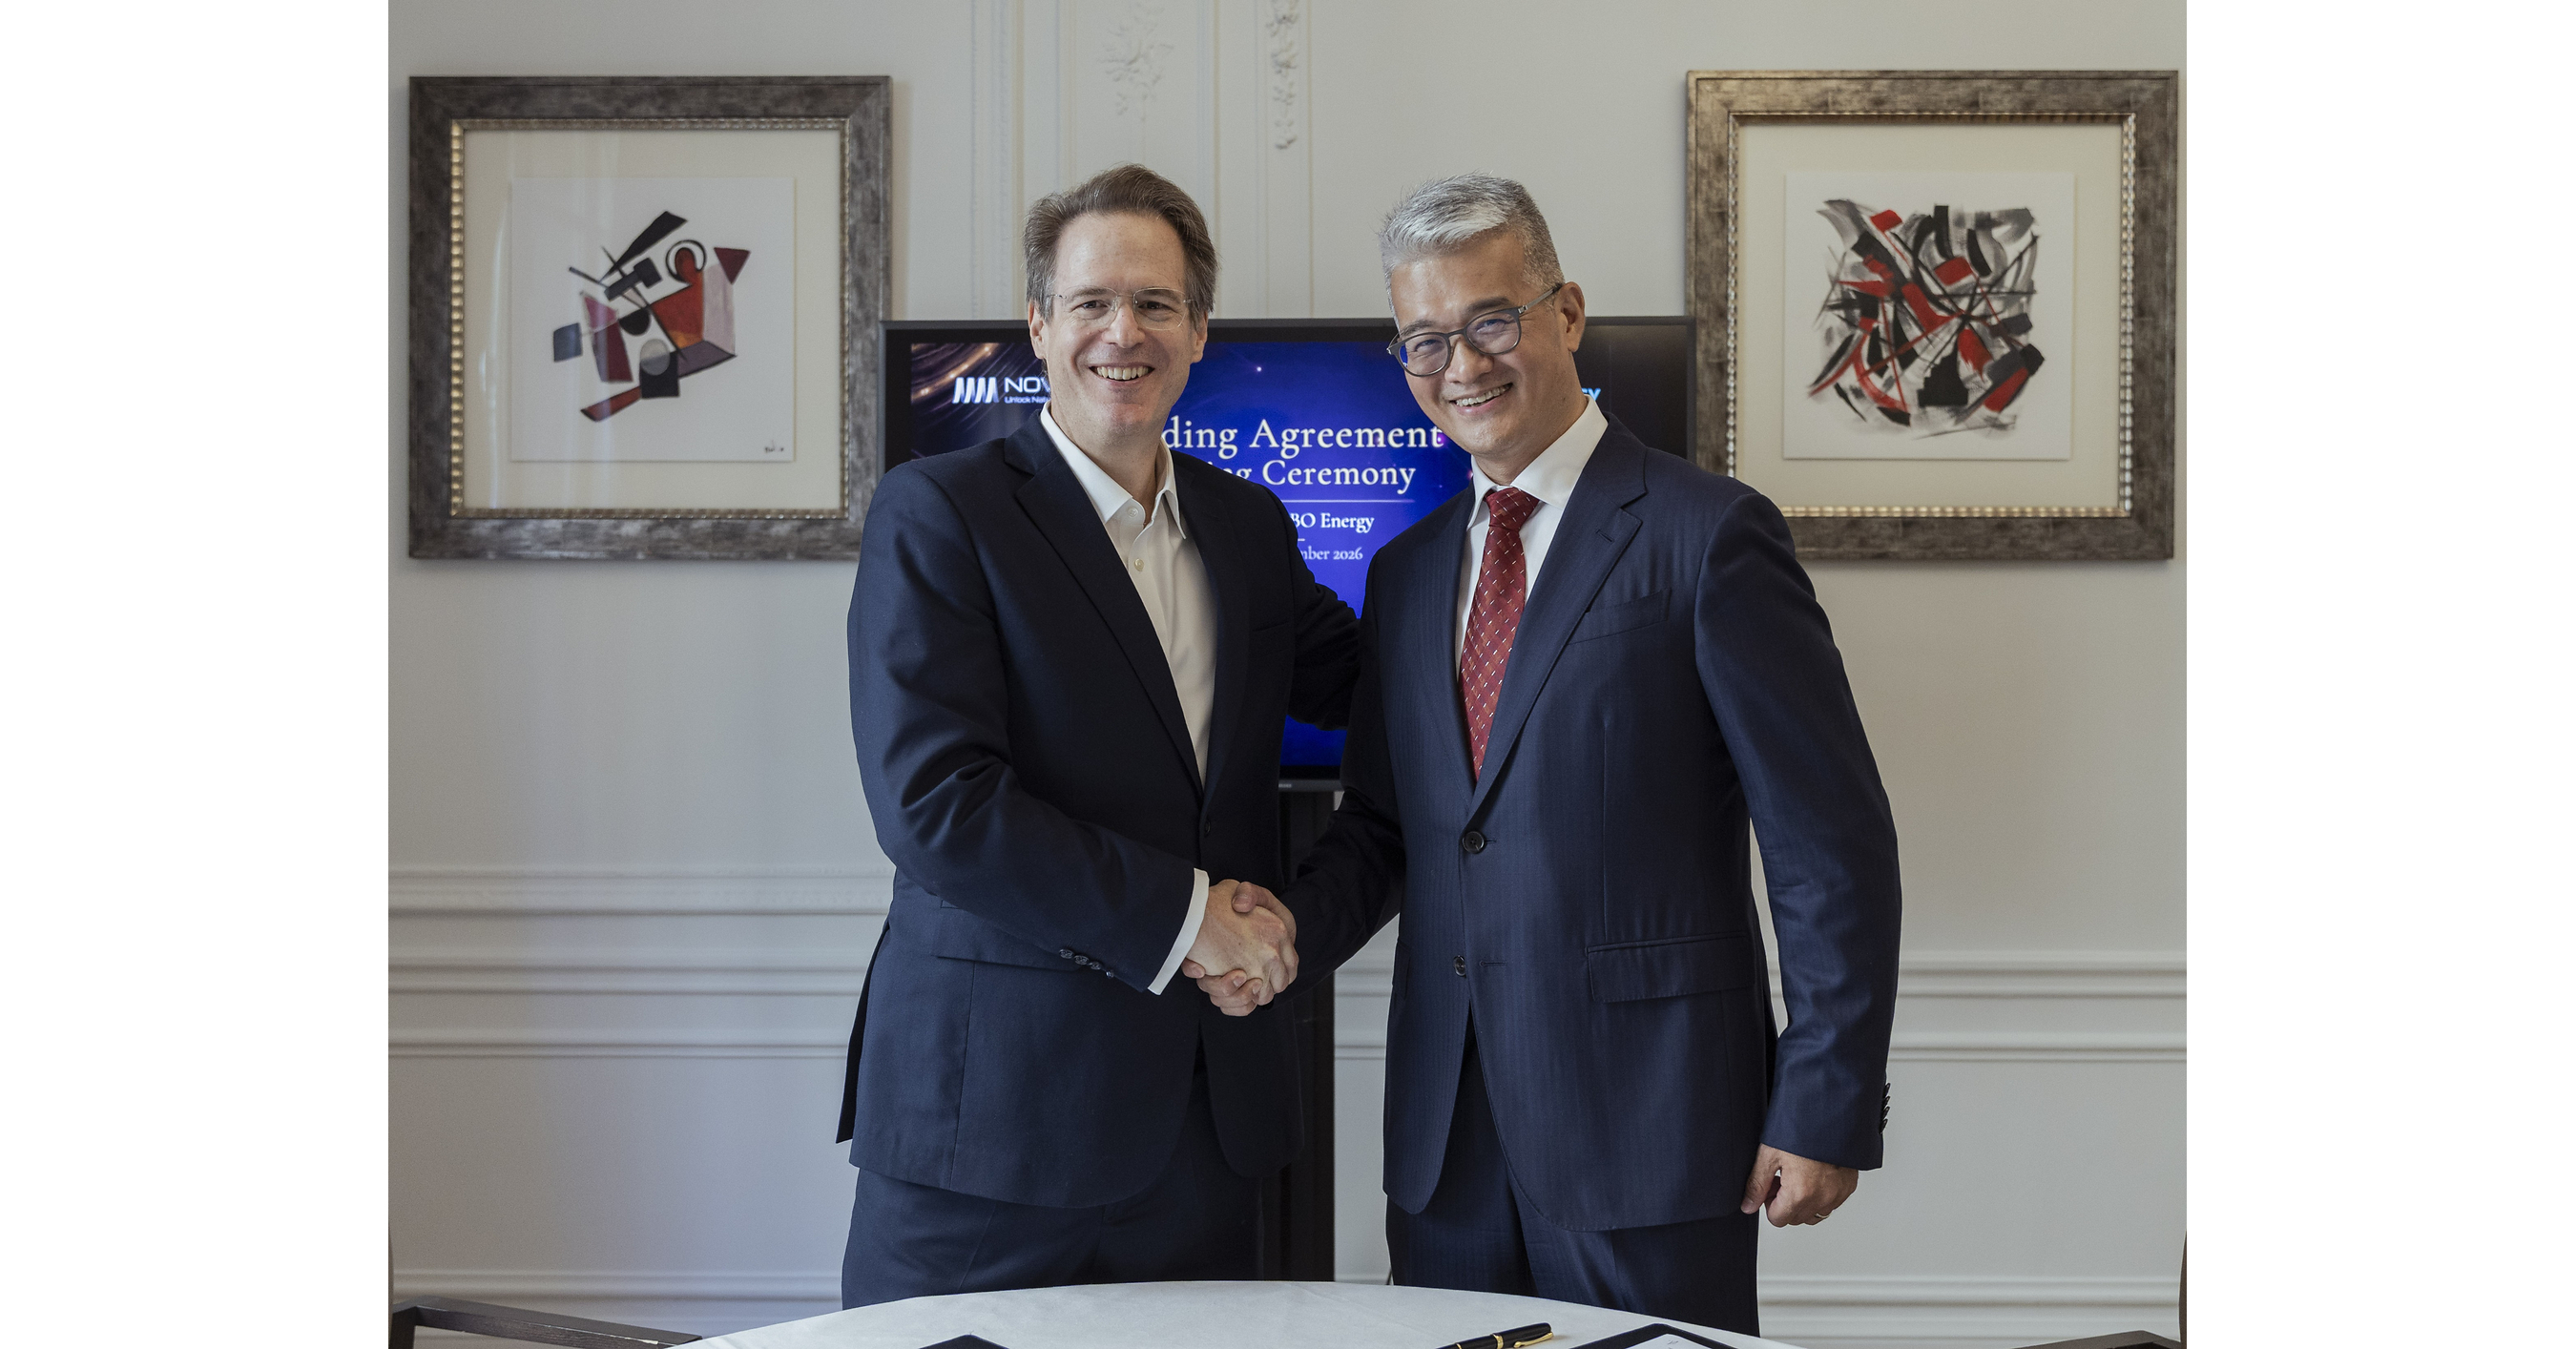
Novva signed a binding framework agreement to acquire a 3.17GW Argentine renewable-energy portfolio from Germany's ABO Energy, materially expanding its Latin American power-development pipeline. The wind and solar assets are intended to supply Novva's AI data-center, Powered Land and Powered Shell infrastructure, following its acquisition of three Colombian solar projects from ABO earlier this year. The transaction strengthens Novva's position in renewable infrastructure for AI-driven electricity demand, though financial terms and closing details were not disclosed.
Analysis
For AB9, the relevant question is not headline pipeline scale but conversion of development rights into cash. A sale to a private counterparty can improve capital recycling and reduce long-dated permitting, grid-connection and construction-financing exposure; however, absent consideration, payment timing, project stage and retained obligations, the transaction has no reliable NAV implication. The market should not capitalize developer-stage capacity at operating-asset multiples.
The AI-power linkage is directionally supportive but commercially indirect in Argentina. Data-center demand requires deliverable power at specific nodes, while renewable projects can face transmission bottlenecks, curtailment, hard-currency convertibility constraints and politically administered power-market terms; a remote generation portfolio is not equivalent to contracted AI load. These frictions favor developers able to secure interconnection and dollar-linked offtake, but they also make financing costs and sovereign-risk premia the dominant determinant of equity value.
Near-term upside for AB9 depends on a definitive agreement disclosing upfront cash proceeds, closing conditions and whether development milestones create contingent consideration. Over 6-18 months, successful execution would validate AB9's ability to monetize its international pipeline rather than hold it on balance sheet, potentially supporting a lower capital-intensity multiple; failure to close or a heavily back-ended earnout would do the opposite. The contrarian view is that investors may overread the buyer's AI narrative before evidence of bankable PPAs, transmission access and project finance is available.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Do not chase AB9 on the framework announcement. Set an event alert for definitive-sale terms; consider a long only if upfront cash consideration is disclosed at or above carrying value and a substantial portion is payable at closing.
- For a confirmed cash-close transaction, initiate a tactical 1-3 month long AB9 with a 10-15% rerating objective and a 7% stop-loss from entry; falsify on delayed closing, material buyer-financing conditions, or predominantly milestone-based consideration.
- Monitor Argentine sovereign spreads, FX-control changes and renewable grid-connection awards as gating variables. A widening sovereign-risk premium or evidence of curtailment would outweigh the strategic narrative and argues against adding exposure.
- Treat Vestas (VWS) and Nordex (NDX1) only as watch-list read-throughs rather than beneficiaries: supplier upside requires disclosed EPC/turbine awards, not a portfolio transfer between developers.
More News
- NOVVA Group adquiere una cartera histórica de energía renovable de 3,17 GW a ABO Energy
- NOVVA Group secures landmark 3.17 GW renewable energy portfolio from ABO Energy to power global AI infrastructure
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks