
Rochefort Asset Management Co-Leads $150+ Million Series D for Firehawk Defense to Scale Domestic Propulsion and Munitions Production
Source: PR Newswire
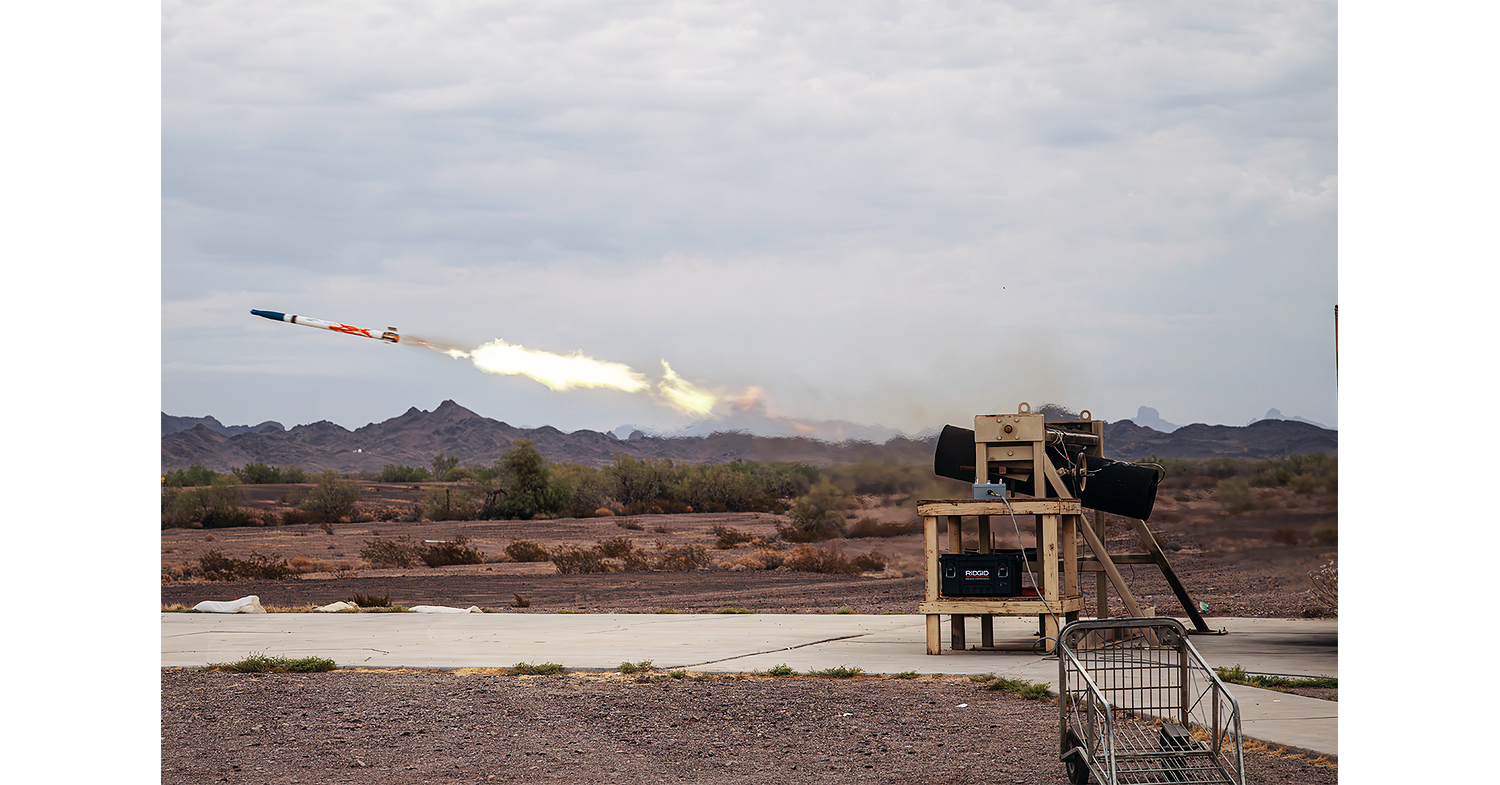
Rochefort Asset Management and Advent International co-led a Series D financing of more than $150 million for Firehawk Defense, adding to Rochefort’s senior secured loan made in April 2026. Proceeds will expand propulsion manufacturing in Oklahoma and Mississippi and accelerate production for U.S. and allied customers amid constrained artillery and rocket-propulsion supply. Firehawk expects its Lawton plant to commission in early 2027 with annual output of 740,000 pounds of thermoplastic propellant, scalable to more than 3.1 million pounds.
Analysis
The investable signal is not the financing itself but whether Firehawk can convert claimed process-speed advantages into qualified, repeatable deliveries. For General Dynamics (GD), the teaming arrangement could ease a constrained input bottleneck and support broader ammunition awards; the counterpoint is that Firehawk’s eventual scale could shift value toward a new supplier rather than materially increase GD’s economics. The release gives no contract value, margin-sharing terms, or expected contribution to GD, so the parent-level earnings impact is unverified.
Near term, treat the announcement as strategic validation, not evidence of commercial throughput. Over 1–3 months, watch for named procurement awards, customer qualification milestones, and evidence that the Lawton commissioning schedule remains intact. Over 6–18 months, the key test is whether installed capacity becomes qualified output and whether buyers place repeat orders; nominal capacity is not equivalent to usable supply. A delay in commissioning, qualification slippage, or failure to secure funded orders would undermine the scale-up thesis. The longer-term upside is a faster, less constrained propulsion supply base, but incumbent producers may respond with capacity additions, limiting pricing power.
Contrarian read: the financing may be interpreted as proof that supply scarcity creates an attractive growth runway. The harder constraint may instead be qualification, process control, and funded demand—not factory footprint. There is insufficient public evidence here to underwrite a GD earnings revision or a broad defense-sector trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in GD on this announcement alone. Do not translate Firehawk’s private financing or stated capacity into a GD revenue or EPS estimate without disclosed contract economics.
- Keep GD on a catalyst watch: reassess on a funded award, U.S. qualification milestone, or disclosure of material program economics. A repeat-order signal would strengthen the read-through; missed qualification or commissioning milestones would weaken it.
- For private-market exposure, treat Firehawk as a high-execution-risk scale-up rather than a proven capacity addition. Verify actual production, customer acceptance, and order backlog before underwriting the stated capacity as available supply.
More News
- We’re downgrading Alphabet after its rough quarter. Here’s where we’d buy again
- Stocks slump, bonds leap as AI giants’ spending spooks investors
- DoorDash offers $17 billion for Instacart: ‘the largest companies are only eating more and more of the pie’
- Christine Lagarde, Boris Vujčić: Monetary policy statement
- ‘Whenever I want it to end’: U.S. tells Middle East allies to prepare for possible new strikes on Iran after the midterms
- PC chip plunge wipes out a quarter of Intel’s value