
Prediction: Buying Archer Aviation Today Could Set You Up for Life
Source: fool.com
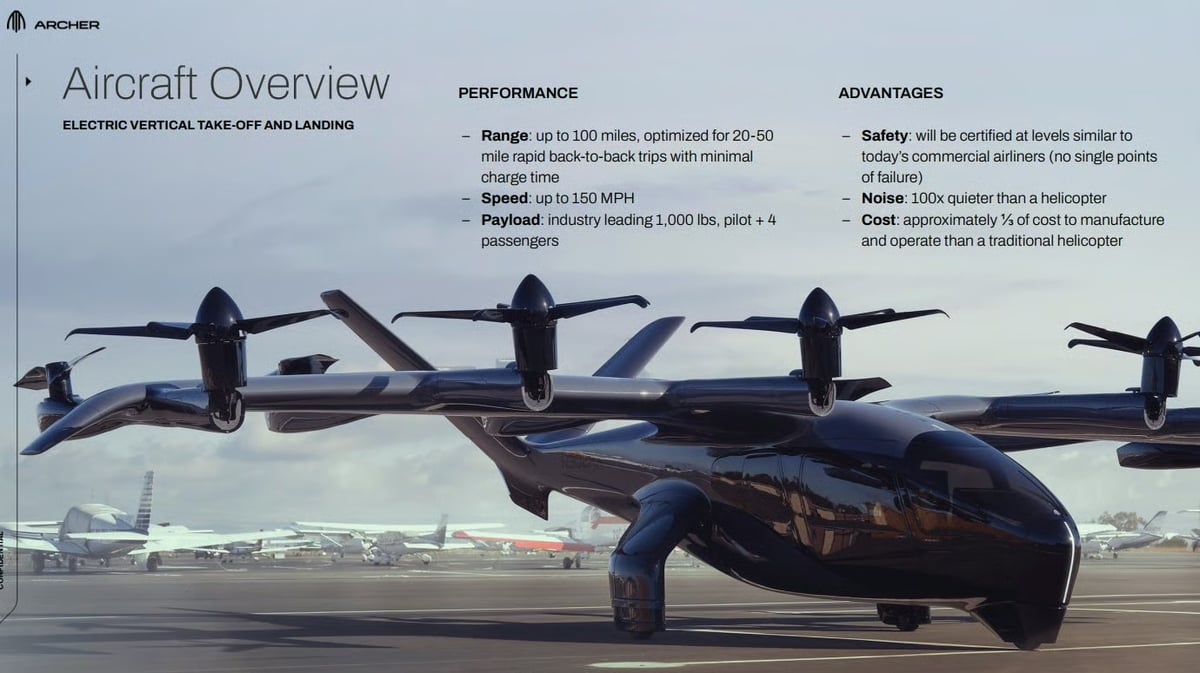
Archer is developing its Midnight eVTOL aircraft and plans to acquire Wisk, Insitu and SkyGrid from Boeing, a deal that the companies say would add more than $200 million in annual revenue from Insitu alone. Archer had about $1.6 billion in cash at the end of June but lost $263 million in Q2, and the acquisition would require issuing shares and dilute existing investors. The article presents substantial long-term upside as speculative, noting the company remains in an early development stage; ACHR was quoted down 6.07%.
Analysis
The key underwriting issue is whether the Boeing asset package reduces Archer’s dependence on certification and fleet commercialization—or merely adds revenue while accelerating dilution. Insitu’s cited revenue is not equivalent to cash flow: purchase price, margins, working-capital needs, contract duration, and closing conditions determine whether the deal improves Archer’s funding profile. Wisk and SkyGrid could add strategic capabilities, but integration and overlapping development priorities may consume management bandwidth precisely when aircraft certification and operating approvals are the gating items. For Boeing, any sale may simplify its portfolio, but proceeds and retained obligations matter more than headline revenue transferred.
Near term, the stock’s speculative valuation leaves it sensitive to financing terms and any slippage in the transaction or certification milestones. Over 1–3 months, watch definitive deal terms, share issuance, regulatory/closing milestones, and Archer’s cash-flow statement—not just net loss. Over 6–18 months, the thesis needs evidence of certification progress, repeatable customer demand, and credible unit economics; a larger addressable market alone does not validate returns. The contrarian risk is that investors treat acquired revenue as diversification, while it may be low-margin or contract-dependent and do little to fund eVTOL scale-up. Conversely, if the assets bring durable cash generation at a disciplined price, dilution could be outweighed by reduced financing risk.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on this article alone. Keep ACHR on a catalyst watchlist; consider only a small, defined-risk exposure after verifying transaction consideration, expected dilution, acquired-business profitability, and closing conditions.
- Do not infer Archer’s cash runway from the reported quarterly loss. Track operating cash burn, capex, and liquidity against certification and commercialization milestones; worsening cash conversion or a financing raise before those milestones would falsify the de-risking case.
- For a potential ACHR long, require evidence that the acquired businesses contribute cash flow rather than revenue alone, alongside certification progress. Failure to secure approvals on schedule, material deal dilution, or guidance that raises funding needs would argue to exit or avoid the position.
- Treat Boeing as a separate, unconfirmed read-through: assess proceeds, retained liabilities, and strategic value of the divested assets before framing the transaction as either positive or negative for BA.
More News
- We're dipping into our large cash pile to buy this bank on Thursday's sell-off
- Apple and Home Depot join list of objectors to tokenized stock plan pushed by NYSE owner
- Magnificent 7 loses $1 trillion. The most eye-popping stats from Thursday's tech stock plunge
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Wall Street’s best post-midterm rally in 44 years lasted just one day—then $3 trillion vanished as chip stocks plunged over AI fears
- AI stocks plunge after election, driving down US markets