
Dahua Technology představuje na IFA 2026 integrované řešení pro chytré bydlení a inovace
Source: PR Newswire
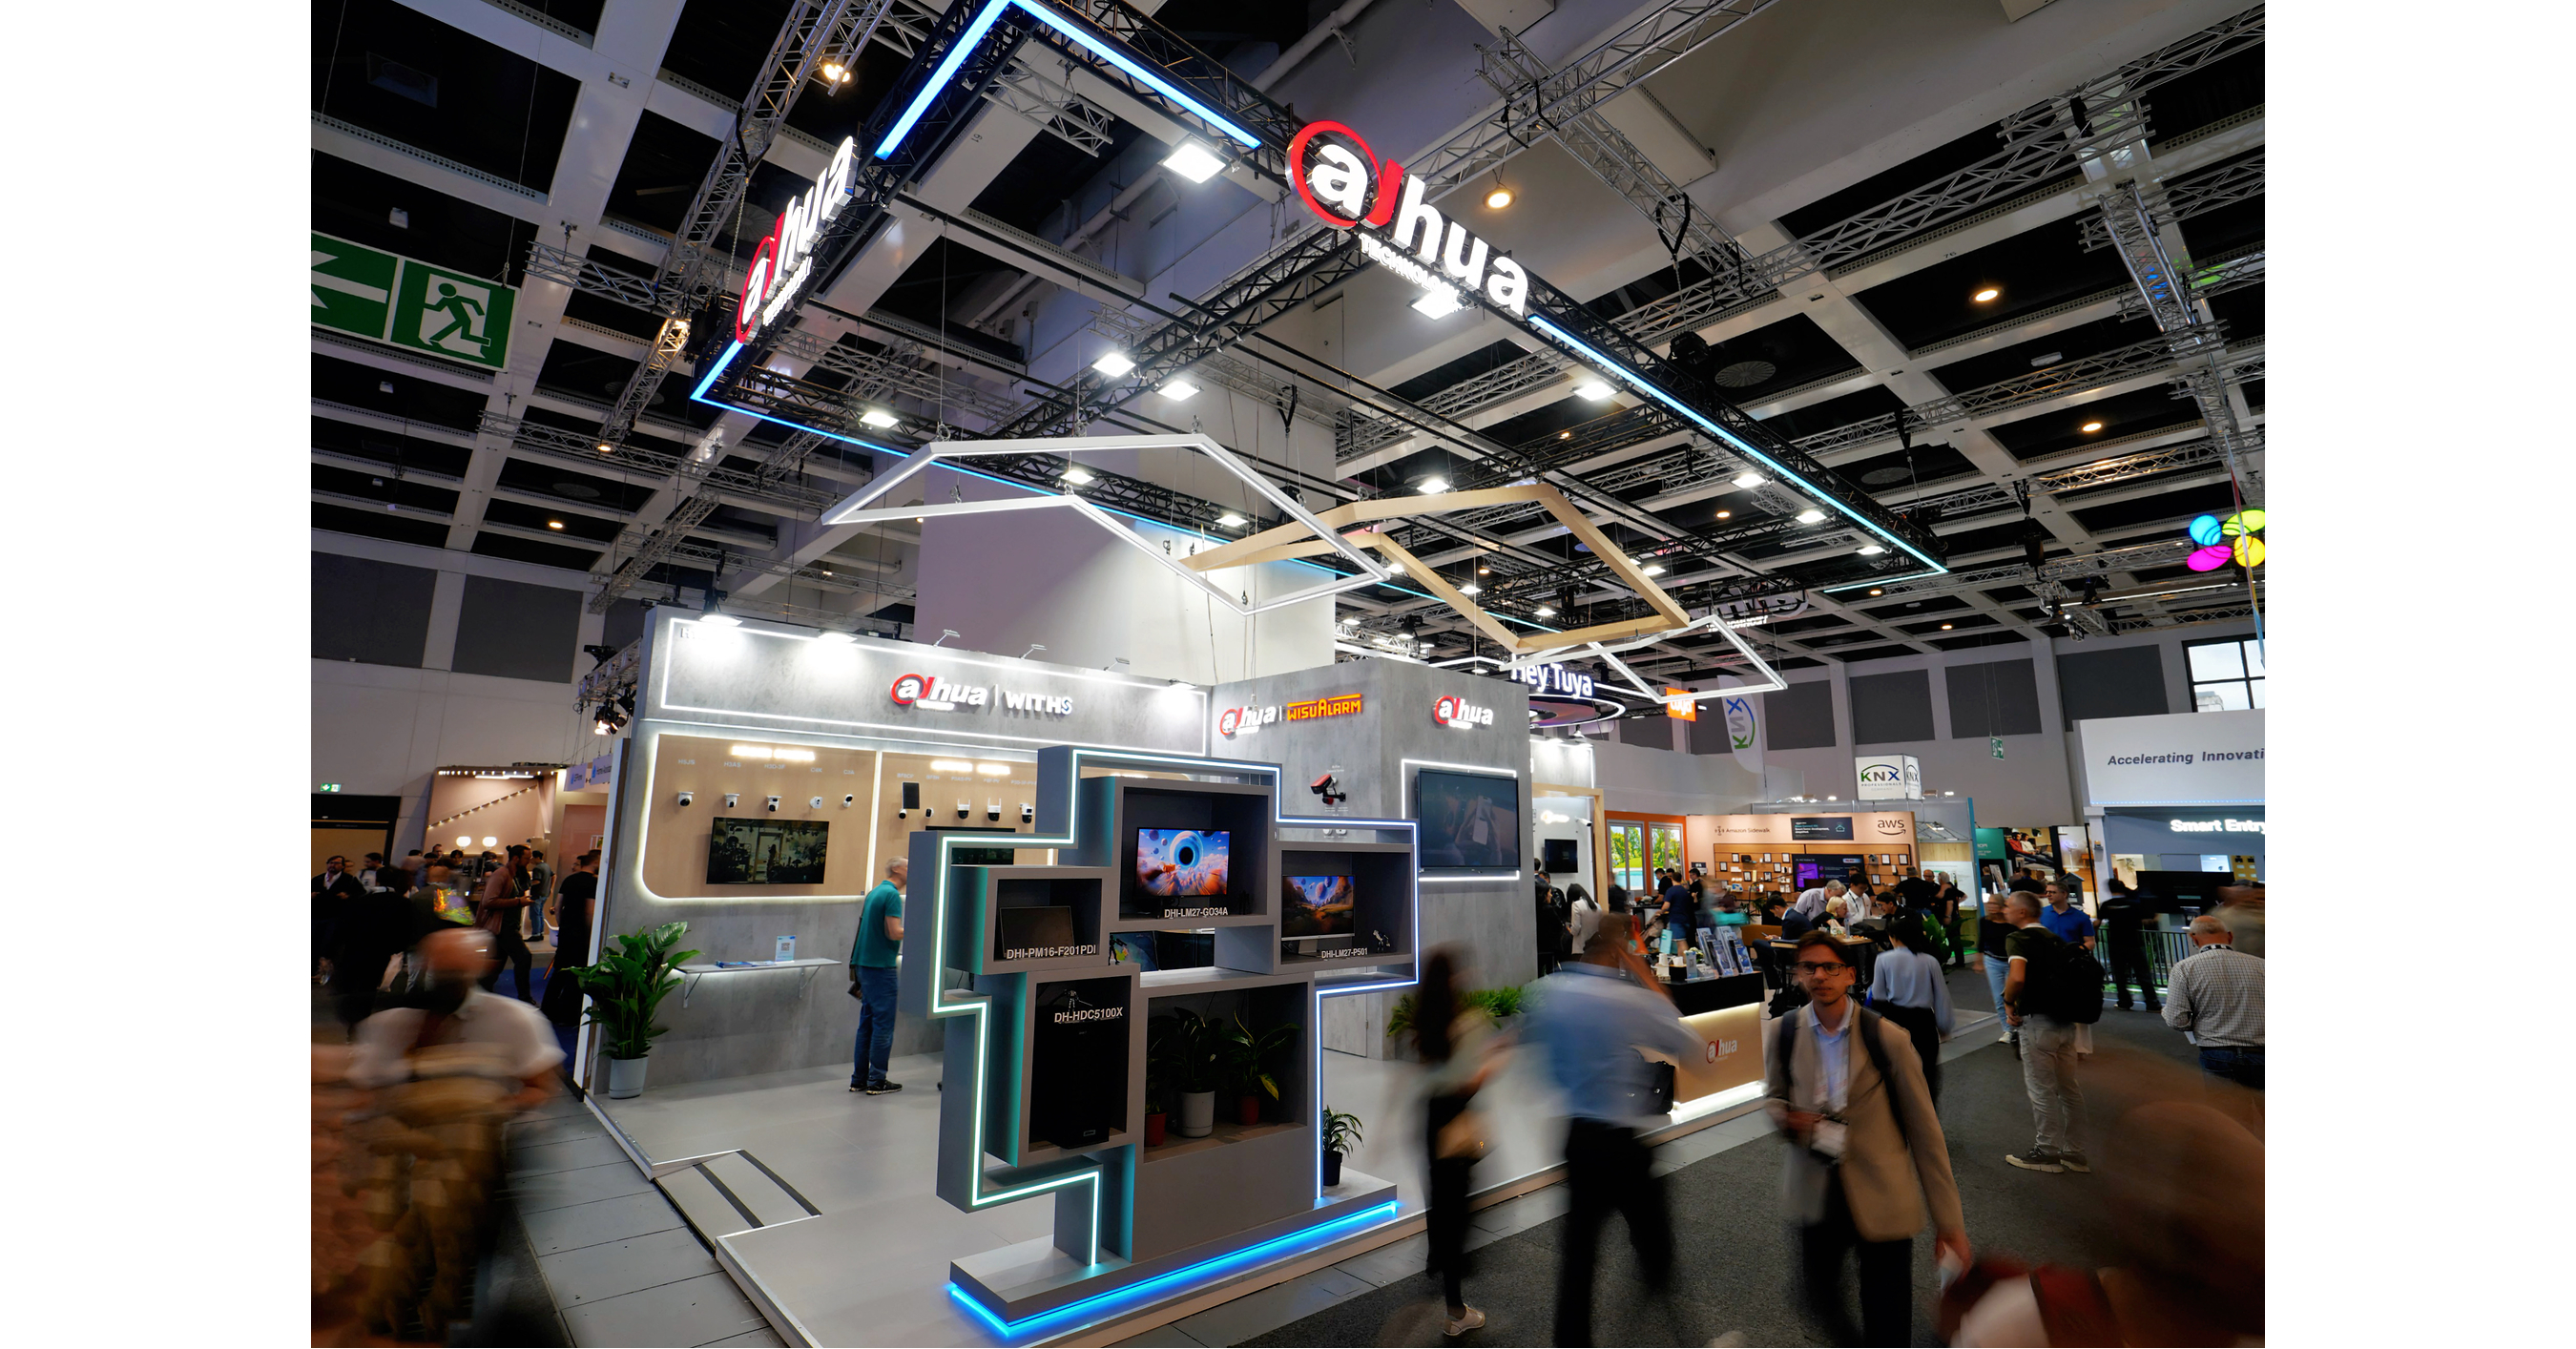
Dahua Technology unveiled an expanded AIoT smart-living portfolio at IFA Berlin 2026, including WITHS wireless surveillance, AirShield intrusion protection, WizTalk AI video intercoms, AI-enabled fire safety systems and gaming monitors. Key offerings integrate Wi-Fi/4G connectivity, cloud management, AI detection of people, vehicles, packages and pets, and selected 5MP or 5MP+2MP dual-camera intercom configurations. The announcement demonstrates product-line expansion beyond core video surveillance but provides no financial targets, contracts, sales data or earnings implications.
Analysis
This is strategically more relevant as a channel-pressure signal than as a near-term earnings catalyst. A broader one-vendor stack can lower installer procurement and integration costs, but it also shifts Dahua toward lower-margin, highly promotional consumer and small-business categories where inventory turns, warranty costs, cloud-support expense, and retailer rebates matter more than camera hardware differentiation. The likely pressure point is European distributors and independent installers that currently mix surveillance, intrusion, intercom, and display vendors; bundled pricing can compress their gross margins before it materially expands Dahua's own revenue.
For listed peers, the clearest read-through is modestly negative for Hikvision (002415.SZ), which faces a similar need to monetize beyond core video hardware, and selectively negative for pure-play security-platform vendors such as Alarm.com (ALRM) and Resideo (REZI) if low-cost integrated hardware gains installer acceptance. That said, cloud subscription ecosystems, professional monitoring relationships, and regulatory-certified fire systems remain materially harder to displace than endpoint hardware. Canon/Axis has comparatively less direct volume risk in regulated enterprise deployments, where data governance, cybersecurity documentation, and approved-vendor status outweigh upfront device cost.
The near-term market impact should be negligible absent evidence of European sell-through, distribution wins, or price actions. Over 1-3 months, monitor IFA follow-up announcements and channel checks for bundle discounts, installer certification uptake, and any expansion in cloud-connected recurring revenue; these are more informative than product specifications. Over 6-18 months, the principal risk to the expansion thesis is that privacy, procurement, and cybersecurity restrictions limit addressable Western-market demand, forcing heavier reliance on price-sensitive channels and worsening hardware margins.
Contrarian view: investors may overread a broad portfolio as proof of platform economics. Without disclosed attach rates, subscription ARPU, return rates, or distributor commitments, the more probable outcome is SKU proliferation rather than a higher-quality revenue mix. The thesis is falsified positively if Dahua demonstrates sustained overseas revenue acceleration without incremental receivables or channel inventory growth; it is falsified negatively if competitors respond with bundled pricing and sector gross margins weaken.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate directional trade: treat this as a channel-intelligence item, not a standalone catalyst. Reassess after 1-2 quarters only if independently verifiable European distribution agreements, sell-through data, or recurring-service metrics emerge.
- Maintain a watchlist pair of long ALRM / short 002415.SZ over a 6-12 month horizon if low-cost integrated hardware meaningfully penetrates installers. ALRM's subscription and monitoring-adjacent revenue should be more resilient than a hardware-heavy peer; avoid entry until relative valuation and China-market liquidity are reviewed.
- For REZI, monitor Security segment organic growth, gross margin, and dealer retention at the next two earnings releases. A guidance cut tied to installer price competition would support a tactical short; absent that evidence, do not infer material earnings risk from a product-show announcement.
- Set an alert for new EU privacy, cybersecurity, or public-procurement restrictions affecting Chinese connected-security vendors. Such developments would be more actionable for a long ALRM or long Canon (7751.T) versus Chinese video-surveillance hardware than the product launch itself.
More News
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Wake up! The long bond’s up two points!
- US tech stocks tumble as investors fret over AI spending
- Mark Zuckerberg owns 13% of Meta but controls 61% of its votes. California’s wealth tax would bill him on the 13%