
Essato&Co Launches a New Vision for Medicalwear Where Function Meets Personal Style
Source: PR Newswire
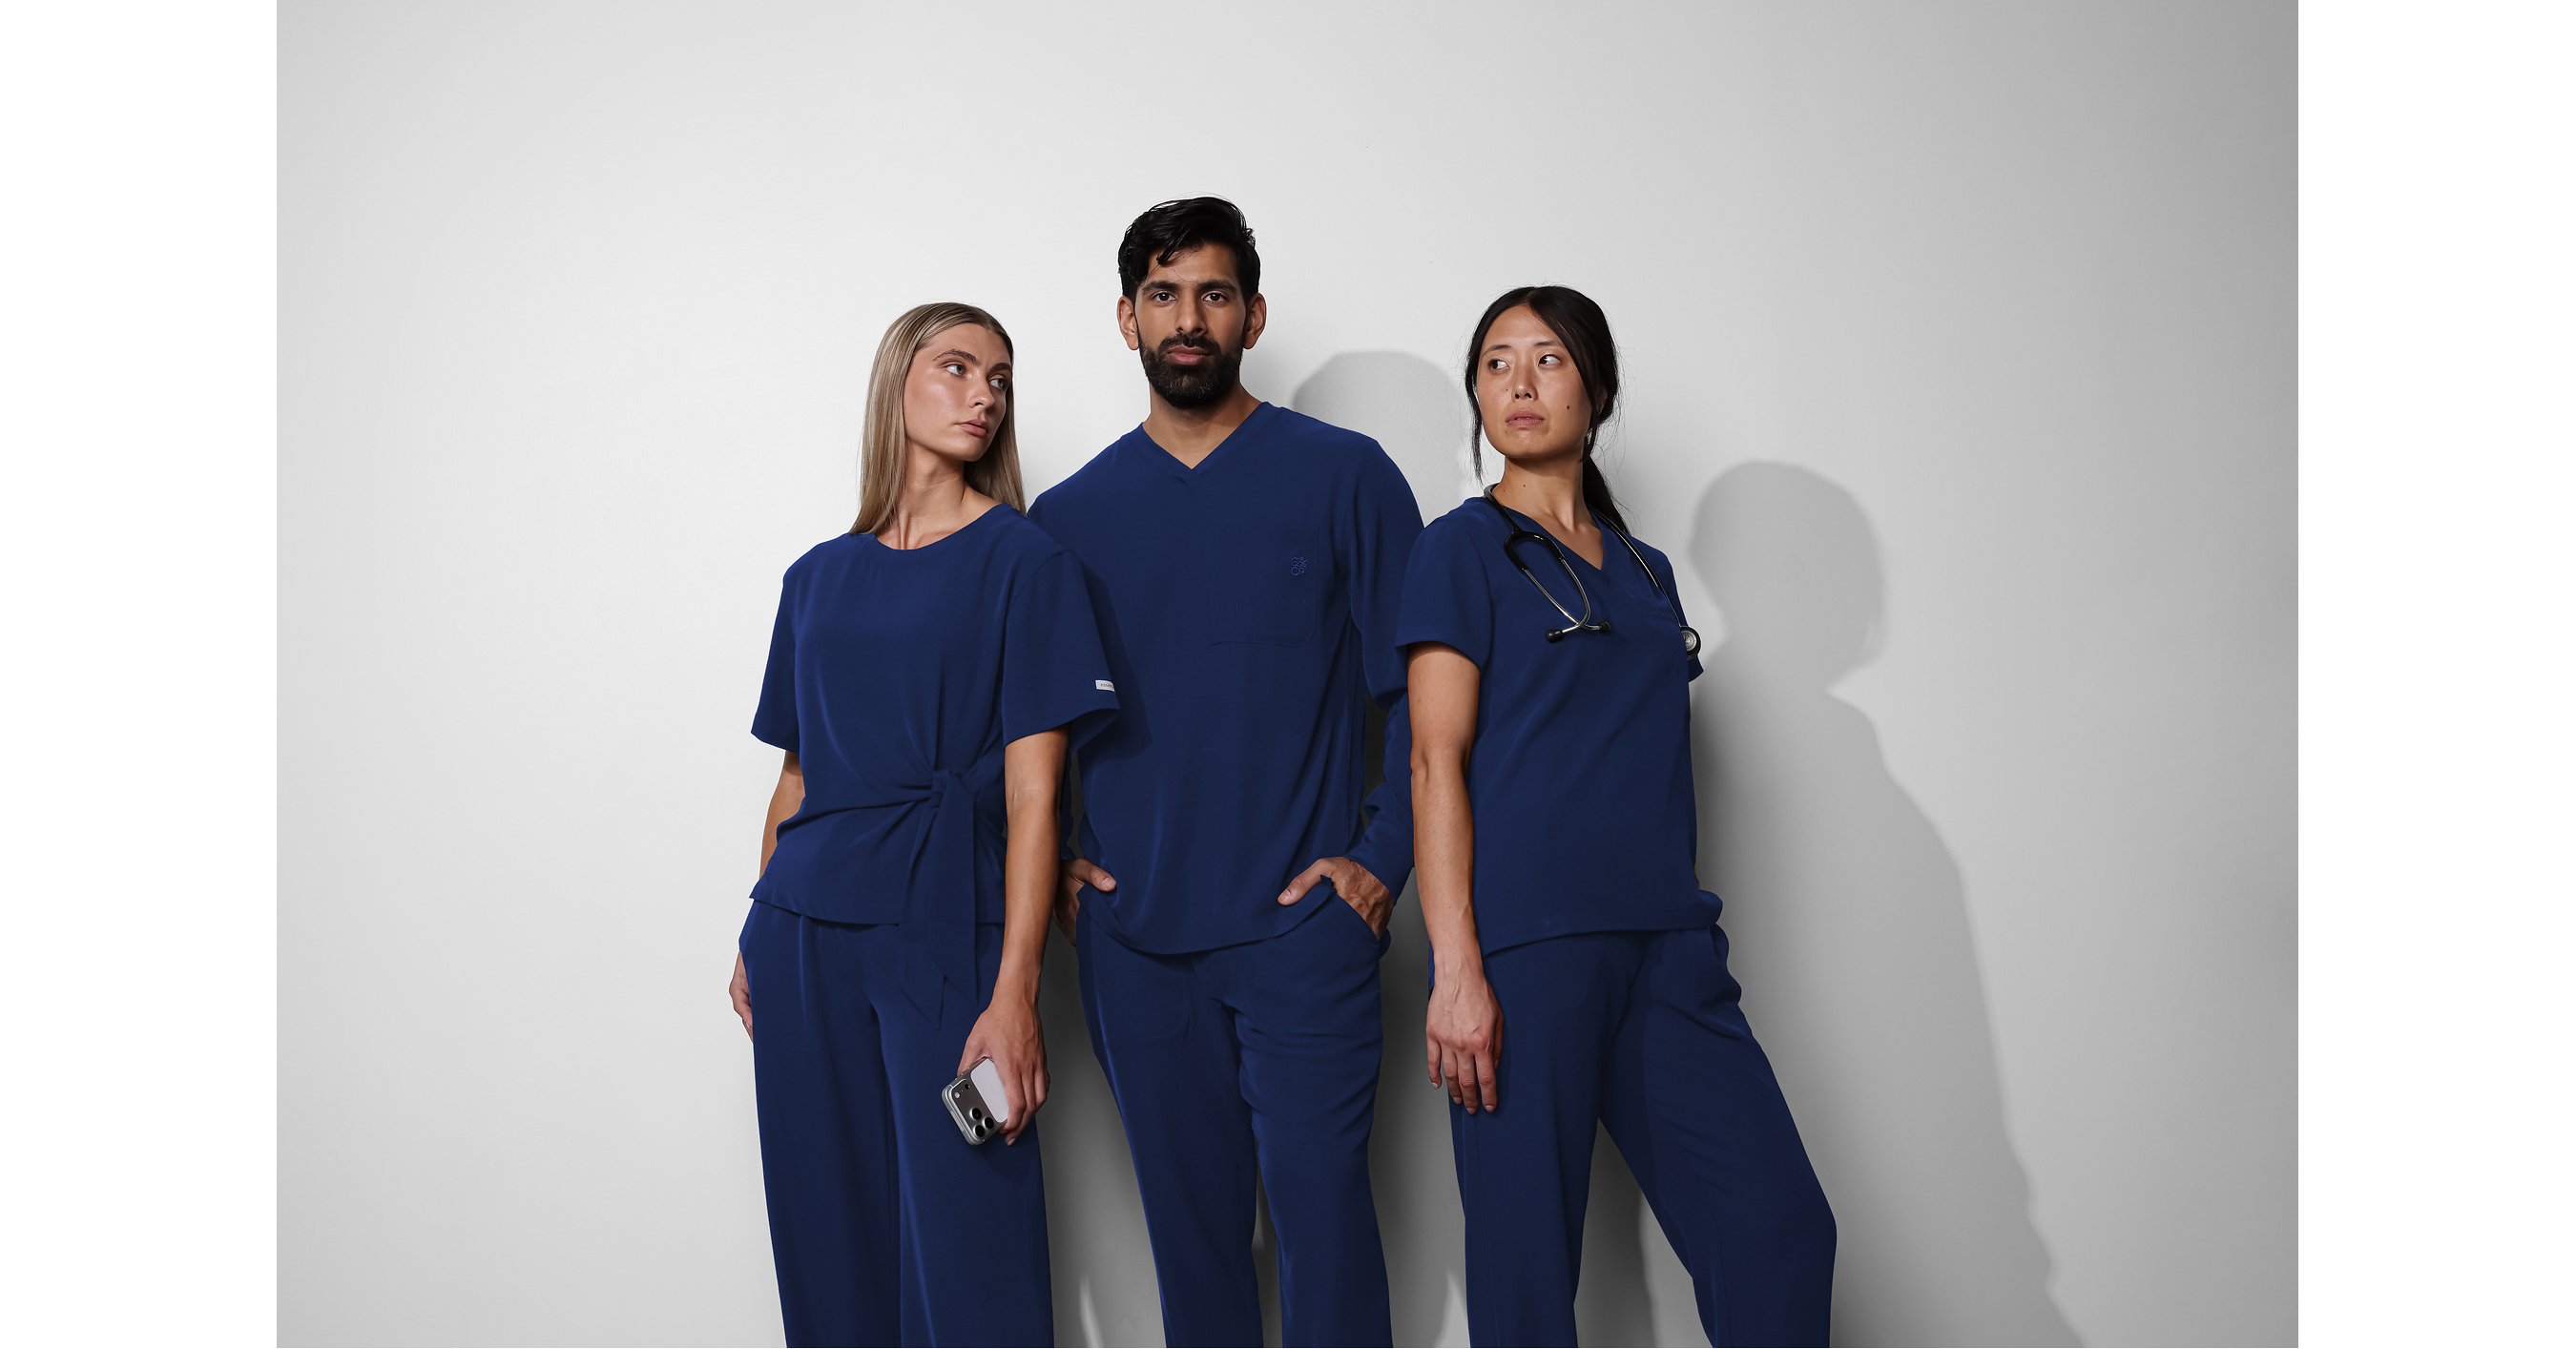
Essato&Co launched its first medical-wear collection, targeting healthcare practitioners with performance-focused apparel priced from $54 to $72 and offered in sizes XS–3XL. The direct-to-consumer brand emphasizes proprietary PerformaCREPE fabric, ergonomic design and a durable, curated wardrobe approach, but disclosed no sales, funding, distribution scale or financial outlook.
Analysis
This is not investable in its current form: a privately held, direct-to-consumer launch with no disclosed funding, distribution, unit economics, customer-acquisition costs, or sales data does not change public-market earnings estimates. The relevant read-through is that premiumization remains the primary competitive axis in medical apparel, but the stated price range sits near incumbent scrub offerings rather than establishing a clear luxury price umbrella.
FIGS is the closest public proxy, although a single niche entrant is immaterial to revenue near term. The more relevant risk is cumulative: digitally native brands targeting style-conscious clinicians can raise paid-search and social acquisition costs, pressure repeat-purchase rates, and fragment a category where differentiation increasingly depends on brand and fit rather than functional fabric claims. Retailers with broad uniform assortments, including Carhartt-license channels and specialty distributors, face less direct risk because institutional purchasing, breadth, and physical distribution remain meaningful moats.
Over the next 1-3 months, there is no identifiable catalyst absent evidence of practitioner adoption, wholesale placement, or unusually high social engagement. Over 6-18 months, watch whether new entrants migrate from DTC into hospital-system contracts; that would matter more for incumbents because procurement wins create recurring volume and lower customer-acquisition costs. The contrarian view is that category fragmentation may actually favor FIGS: smaller brands can validate premium demand but often lack the balance sheet, assortment depth, and fulfillment scale required to sustain growth once initial influencer-driven demand fades.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No new position based on this launch; treat as a competitive-intelligence alert rather than an earnings-relevant event.
- Maintain FIGS on watch for evidence of category fragmentation: reassess only if management reports rising digital marketing expense, declining active-customer growth, or repeat-order deterioration over the next two earnings cycles.
- For an existing FIGS long, use quarterly gross-margin performance and selling-expense leverage as the key falsifiers; sustained gross-margin compression or worsening customer-acquisition efficiency would indicate that competitive entry is becoming financially material.
- Monitor private-brand wholesale expansion and healthcare-system procurement announcements over 6-18 months. A credible contract channel, rather than DTC product claims, would be the threshold for considering a relative-value short FIGS versus broader apparel exposure.
More News
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Federal Reserve decision, retail sales, and oil inventories due Wednesday
- Wells Fargo sees improvement in a key metric — plus, Lilly gets praise beyond GLP-1s
- Hong Kong unveils first five-year plan to add jobs, homes, align closer to mainland China
- Beta Bionics prices $150M public offering at $17.25/share