
TURPAZ EXPANDS ITS FLAVOR AND FRAGRANCE ACTIVITIES IN AFRICA WITH THE ACQUISITION OF SOUTH AFRICA'S SENSORY FX
Source: PR Newswire
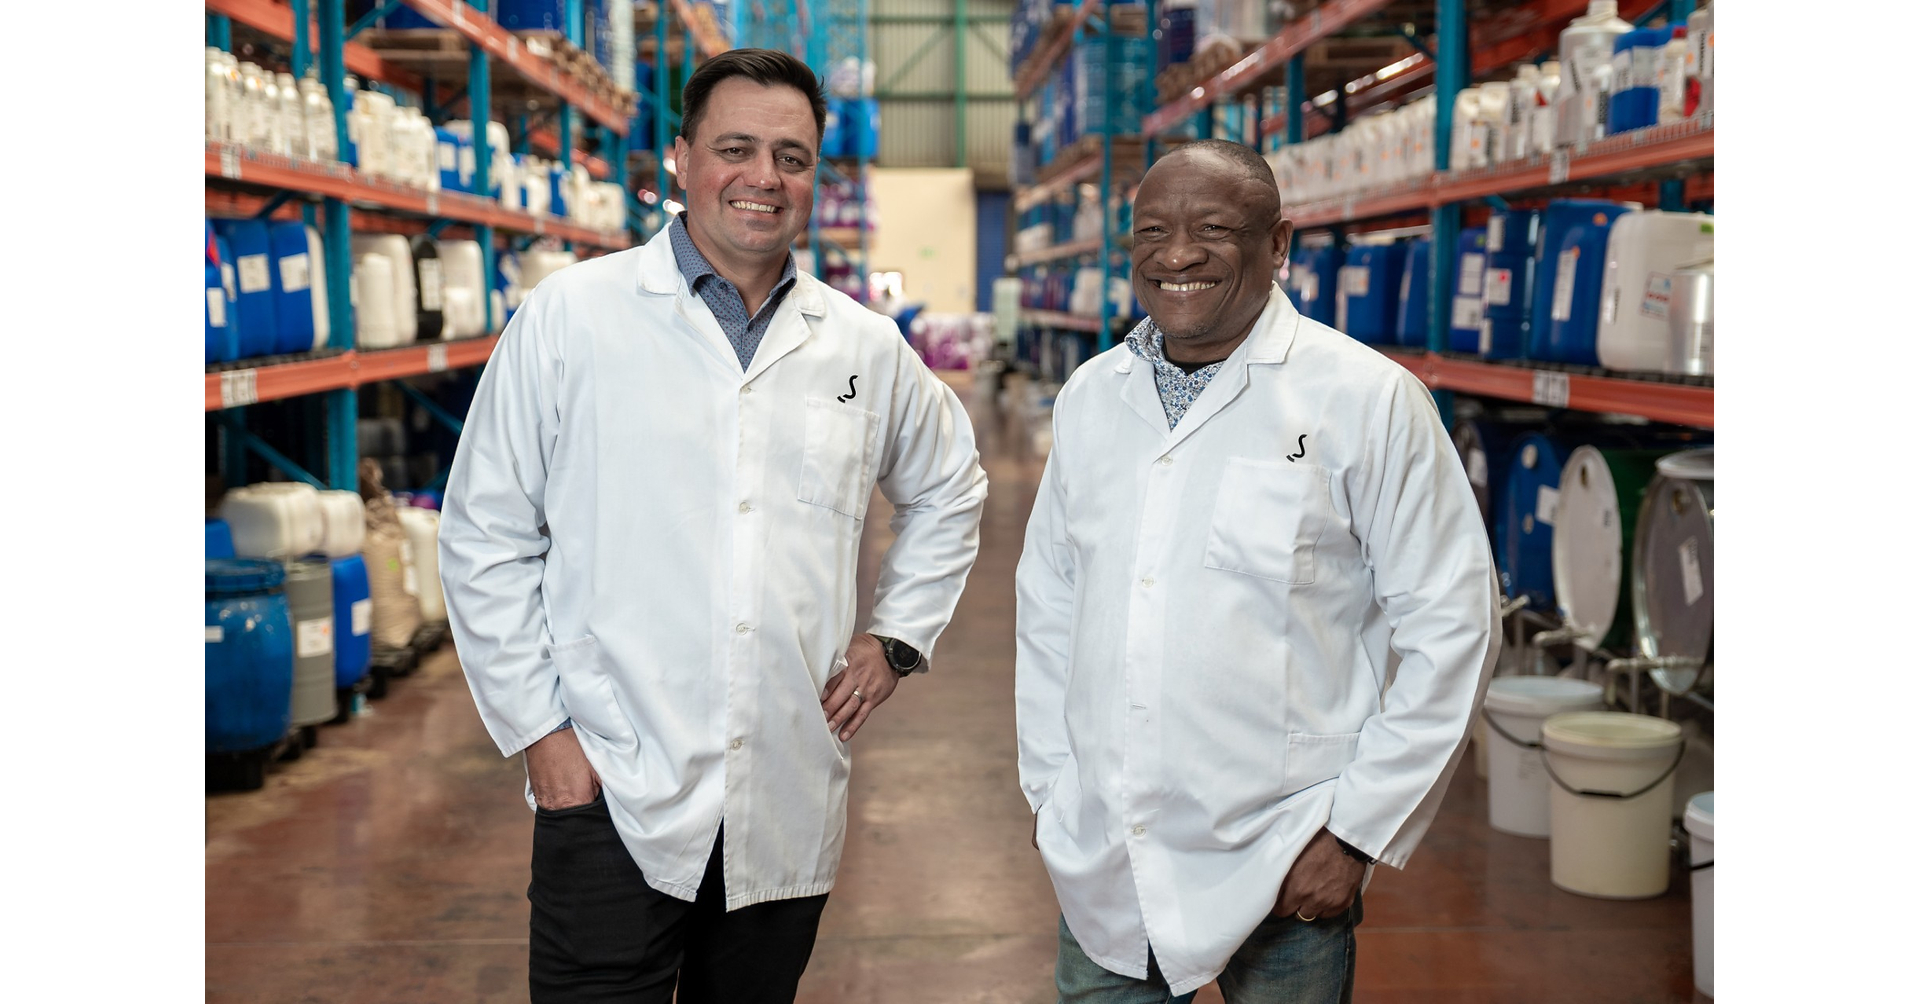
Turpaz acquired 70% of South African flavor and fragrance company Sensory for approximately $10.6 million (ZAR 177.4 million), plus performance-based consideration, financed with long-term bank debt. Sensory reported FY2026 revenue of $10.9 million, up approximately 18%, and EBITDA of $2.4 million; its existing shareholders retain 30% and continue managing operations. Turpaz expects the deal to support its first entry into South Africa's fragrance market and build an integrated African platform, with potential synergies and cross-selling opportunities.
Analysis
The strategic value is less the acquired earnings than a local fragrance manufacturing and R&D foothold that can be paired with Turpaz’s existing South African flavor businesses. Cross-selling and shared procurement could improve returns, but these are management targets—not booked synergies—and execution depends on retaining Sensory’s technical team and customer relationships. Global flavor-and-fragrance competitors such as Givaudan, IFF and Symrise are plausible competitive pressure; local responsiveness may help Turpaz compete, but does not establish pricing power.
At the stated consideration, a simple pro-rata equity-value implication is about $15.1 million, or roughly 6.3x Sensory’s reported EBITDA. This is not an enterprise-value multiple: net debt/cash, the performance payment and transaction adjustments are unknown. Debt funding adds financing exposure; the future put/call over the retained stake may require cash or create dilution, depending on the election and terms. Rand volatility also makes local operating performance and dollar-reported results diverge.
Near term, the announcement is a modest positive signal of acquisition execution, not enough information to underwrite a material group-level earnings revision. Over 1–3 months, verify earnout terms, funding cost, and any quantified synergy or integration guidance. Over 6–18 months, test whether cross-selling and regional expansion deliver organic growth without customer or talent attrition. The thesis weakens if Sensory’s EBITDA falls below its reported $2.4 million baseline, key staff/customers depart, or debt and remaining-share consideration outpace cash generation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- Treat as a strategically positive but not yet earnings-material catalyst; avoid chasing an announcement-driven move without evidence of a consolidated earnings or guidance revision.
- For a 1–3 month watch, seek disclosure on net debt/cash, earnout mechanics, financing cost, and the put/call valuation formula before treating the headline consideration as a definitive acquisition multiple.
- If building TRPZ exposure, favor staged entry after the initial reaction; reassess if management quantifies synergies and subsequent reporting shows sustained Sensory growth and EBITDA at or above the disclosed baseline.
- Monitor the ZAR and retention of Sensory’s senior technical team and customer base; material currency weakness or departures would challenge the regional-platform thesis and could impair the value of the retained-stake options.
More News
- Marvell to buy Lumentum in $115 billion deal in AI data-center bet
- Marvell, Lumentum tout historic $115B deal to create ‘category leader' in AI connectivity
- Palantir reports booming U.S. commercial revenue growth, topping government for first time
- Anthropic releases amended IPO prospectus with third-quarter financials
- Coinbase has been battered over the past month. Morgan Stanley says steer clear
- The AI boom is facing another supply crunch. This time it’s the amount of capital available to feed Silicon Valley’s endless need for cash
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- How to Use AI for an Initiating Coverage Report
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)