
Garmin expands its flagship performance smartwatch lineup with fēnix 9 and fēnix 9 Pro
Source: PR Newswire
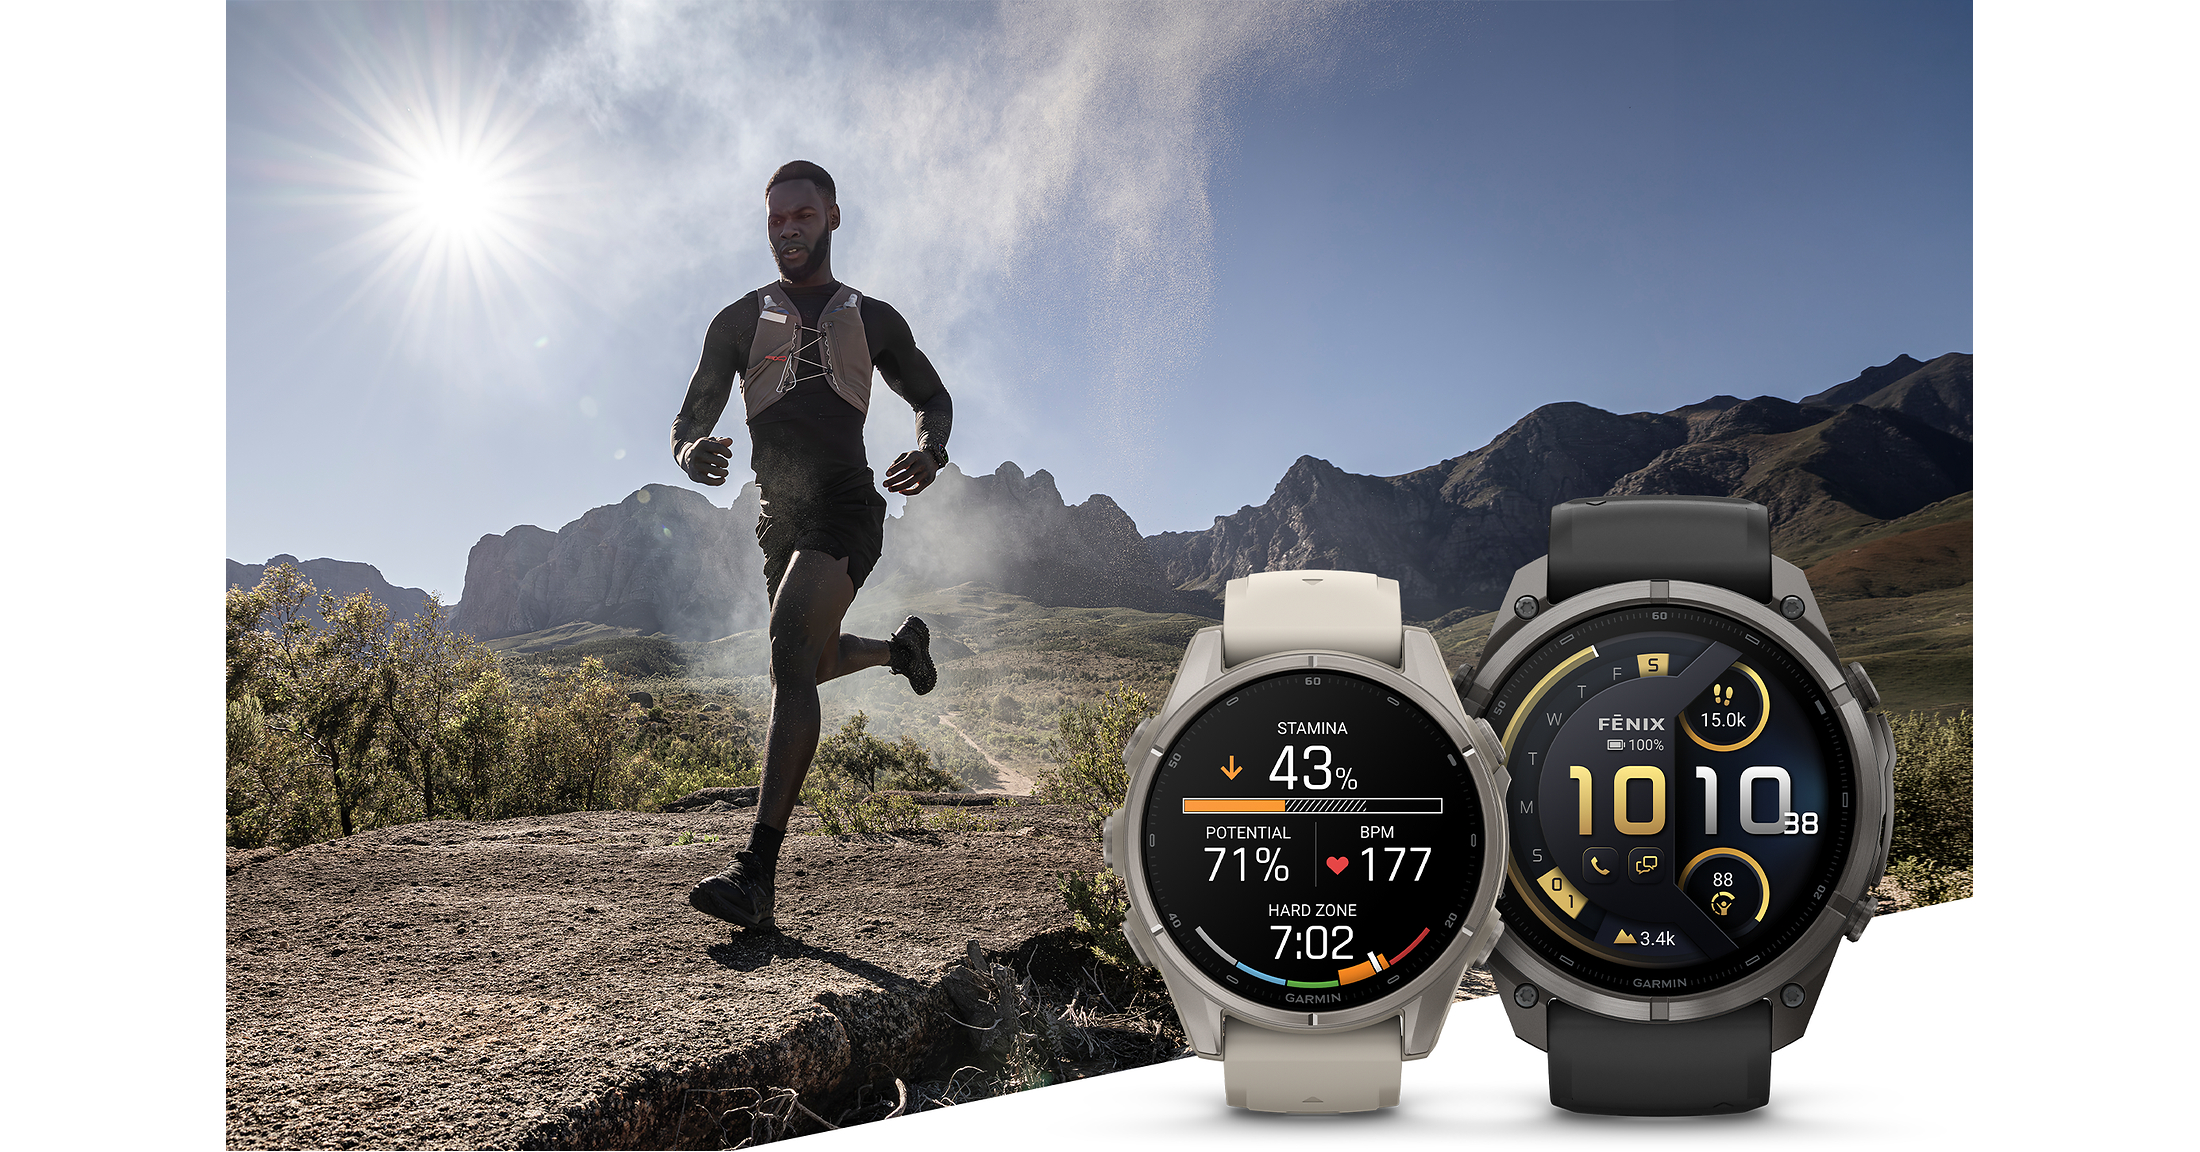
Garmin launched fēnix 9 and fēnix 9 Pro, introducing a titanium watch case (first for the line), brighter AMOLED displays up to 3,000 nits, and a new Garmin Epic feature that groups multiple activities into shareable stories. Pricing starts at $999.99 for fēnix 9 and $1,099.99 for fēnix 9 Pro, with select solar models rated up to 57 days of battery life. The product update also adds phone-free satellite/LTE connectivity on all Pro sizes, including voice/text/SOS and new LiveTrack/Locate features via Garmin Messenger.
Analysis
This looks more like a mix-and-mix story than a step-change earnings event. The immediate upside for GRMN is mix: premium positioning can defend price and may lift gross margin modestly, but the bigger economic lever is whether the newer connectivity stack converts one-time device buyers into recurring service revenue. If attach rates are low, this is just a replacement cycle; if attach rates surprise, the multiple can expand because the market will start capitalizing a higher-quality revenue stream.
Competitive pressure is asymmetric. Apple Watch Ultra remains the obvious substitute for affluent buyers who want premium hardware, but Garmin still owns the battery/navigation/safety use case where phone-free reliability matters more than app breadth. The second-order winner could be Garmin’s ecosystem economics: more time in Garmin Connect increases switching costs and makes future upsells easier, while smaller outdoor-watch rivals likely face harder customer acquisition if Garmin keeps widening the feature gap.
The main risk is that the launch is ahead of demand, not a demand catalyst. Premium watches are discretionary, and at this price point adoption is sensitive to consumer confidence and carrier/service friction; any weak activation data would quickly cap the thesis. Over 1-3 months, watch sell-through and attach-rate checks matter more than the press release; over 6-18 months, the key question is whether Garmin can turn safety/connectivity into a recurring subscription layer rather than a one-off hardware refresh.
Contrarian view: the market may overreact to the titanium/display narrative and underappreciate that the real driver is service monetization, which is harder to prove. Absent evidence of stronger LTE/inReach adoption, I’d treat this as a defendable franchise update, not a reason to pay up aggressively.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Maintain a small long GRMN bias, but only on pullbacks; upside is driven by premium mix and service attach, not the product launch alone. Use a 1-3 month horizon and require evidence of stronger channel sell-through before adding.
- If GRMN spikes >3-5% on launch enthusiasm, fade part of the move with a tactical short or covered-call overlay; thesis: hardware-cycle headlines usually outrun estimate revisions unless activation data confirms recurring revenue.
- Watch LTE/inReach activation trends and commentary on subscription attach in the next earnings cycle; if service revenue growth reaccelerates, add to GRMN for a 6-18 month multiple-expansion trade. Falsifier: flat device ASPs or no service revenue acceleration.
- Relative-value idea: long GRMN vs. a broad consumer-discretionary proxy on any risk-off tape, since Garmin’s premium outdoor buyer base is less promotional and more replacement-driven than general consumer electronics.
More News
- ‘The gap was not the awareness’: The company phishing trainings you loathe aren’t enough when nearly 1 in 4 security pros say their MFA is optional
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- This exchange stock is a buy on renewed options deal, Morgan Stanley says
- India calls JD Vance's comments about immigrants 'deeply offensive'
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash
- AlphaSense Pricing: What Public Contract Data Shows in 2026