
Eagle Materials Deserves To Fly Higher
Source: seekingalpha.com
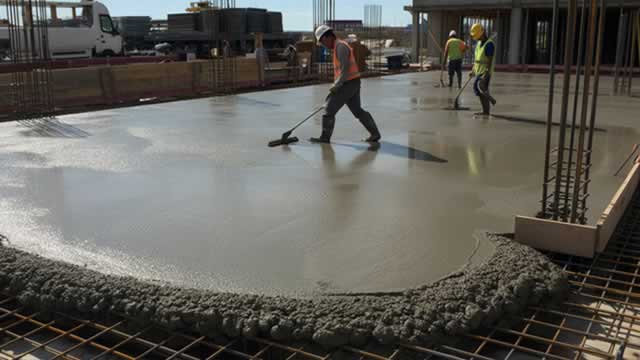
Eagle Materials (EXP) remains rated “Buy” despite a 20% stock decline and ongoing profitability pressure. Revenue is rising, driven by Cement and Recycled Paperboard, but higher costs and weak pricing are squeezing margins; management is expanding and modernizing capacity to target lower costs and higher production.
Analysis
The setup is a margin-conversion test, not simply a growth story: higher volume or revenue will not support the long thesis if realized cement pricing continues to lag input-cost inflation. Cement is locally competitive because freight limits the economic reach of supply, so EXP’s new capacity could strengthen its position where demand absorbs it—or weigh on regional pricing and utilization if additions outpace construction demand. Compare project timing and regional pricing with Cemex, Martin Marietta, and Vulcan Materials rather than assuming the capacity build is uniformly accretive. Recycled Paperboard adds a separate check: growth there may not offset weakness in cement if recovered-fiber, energy, or packaging-cycle economics deteriorate.
Near term, the 20% share-price decline alone is not evidence of undervaluation; the article provides no valuation, decline period, or cash-flow detail. Over 1–3 months, watch earnings commentary for the price-cost spread, utilization, and capex/commissioning milestones. Over 6–18 months, successful modernization could improve cost competitiveness, but delayed ramp-up or weak demand would leave investors bearing capital costs before returns arrive. The contrarian risk is that investors focus on current margin pressure while underestimating eventual operating benefits; the counter-risk is treating planned capacity as realized earnings without proof.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Avoid buying solely because EXP is down 20%. Consider a staged long only after evidence that cement pricing is keeping pace with costs and new capacity is ramping; verify valuation and free-cash-flow implications first.
- Set an alert for the next results and guidance: track cement price realization versus input costs, segment margins, utilization, capex, and project commissioning. A further deterioration in margins or delays to stated projects would falsify the recovery thesis.
- Monitor regional supply additions and pricing from Cemex, Martin Marietta, and Vulcan Materials. If supply grows faster than local demand, reassess EXP’s expected volume gains and pricing power rather than extrapolating revenue growth.
- No high-conviction pair trade is supported by the supplied information: peer valuations, regional overlap, and comparable segment economics are missing.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- Why is Rocket Lab stock tumbling today?
- AI infrastructure stocks tumble. Here's a few reasons for the sell-off
- Why is Netwealth stock sliding today?