
En s'intéressant de plus près aux besoins concrets des particuliers, EZVIZ présente à l'IFA des innovations et des produits domotiques de nouvelle génération, avec des scénarios d'utilisation élargis
Source: PR Newswire
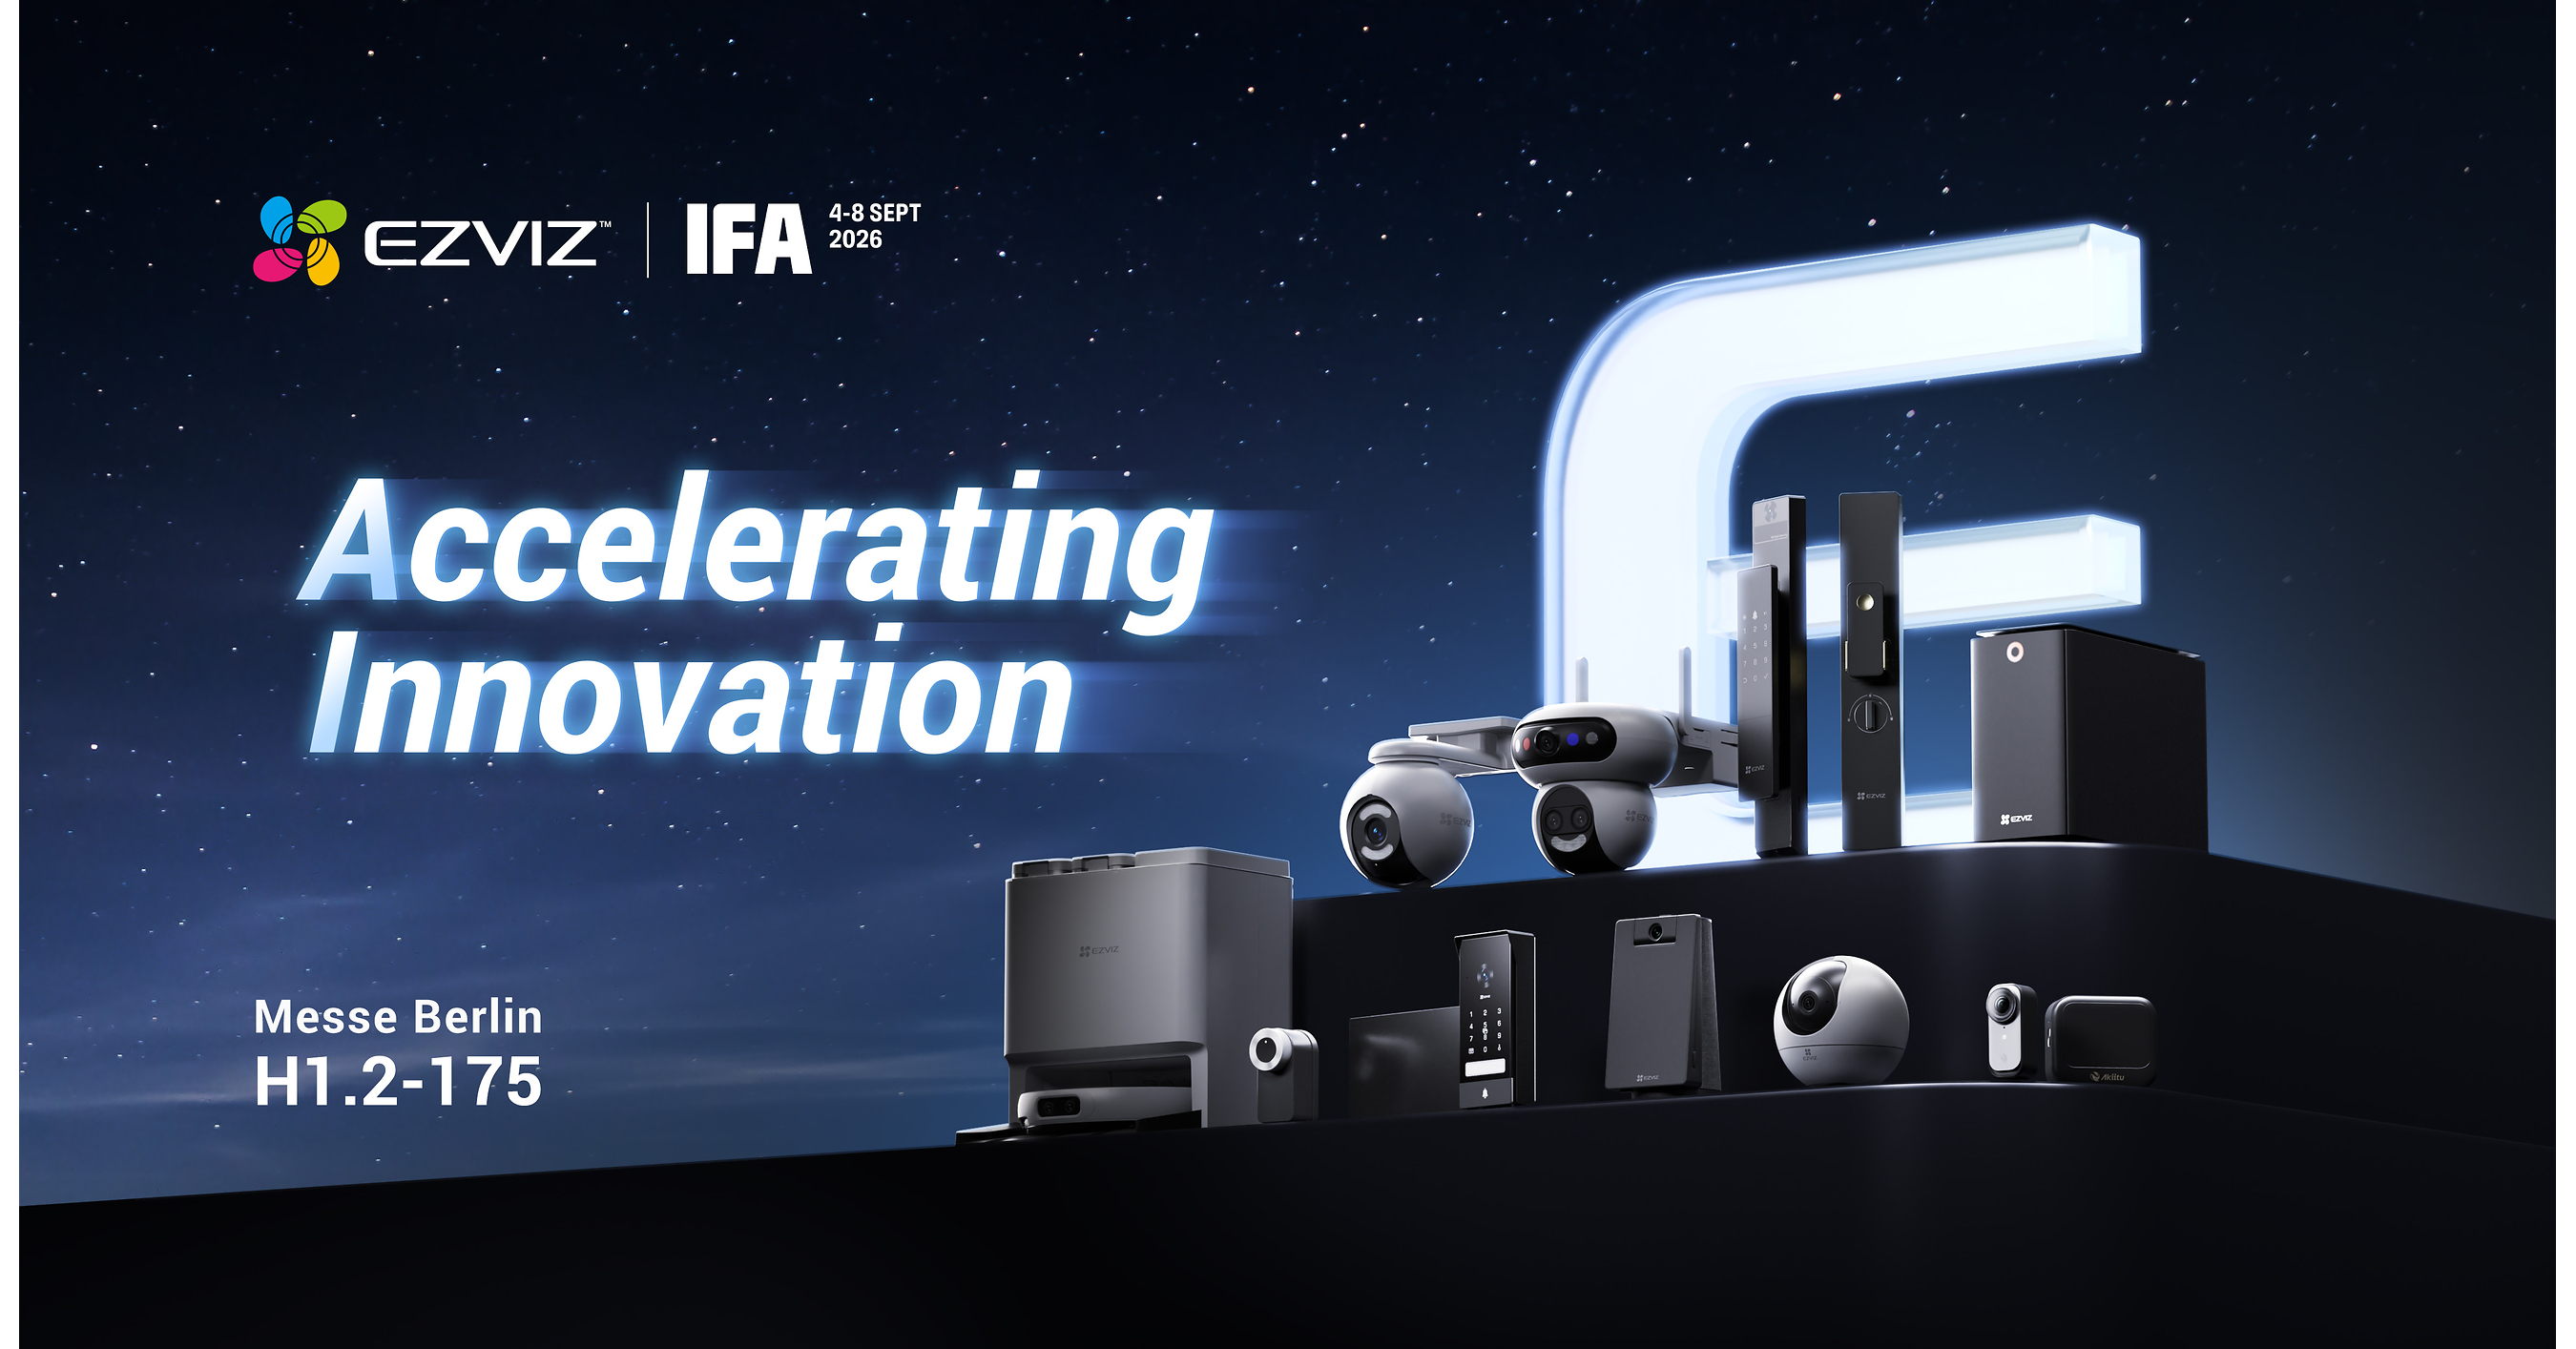
EZVIZ showcased new IFA 2026 smart-home and security products, including triple-objective 90f series cameras (12x mixed zoom) and a compact dual-objective CB60 camera with switchable 4G-Wi‑Fi, aimed at expanding local, on-device AI functionality. The company also launched an AI CoreX dock offering local (no-cloud) storage/search for large files and multi-device management. Overall tone is product-led and optimistic, but the article is largely a launch/feature update with limited direct financial impact details.
Analysis
This reads less like a one-off product announcement and more like evidence that the smart-home category is shifting from cloud-dependent features to edge inference and local storage. That matters because the economics tilt from recurring software/service revenue toward one-time hardware gross profit, which is good for component suppliers and OEMs with distribution scale, but structurally harder for subscription-first security platforms. If consumers start viewing privacy-preserving local AI as the default, the monetization gap between premium hardware and low-ARPU monitoring services narrows quickly.
The most exposed losers are businesses whose differentiation depends on cloud analytics, video retention, or paid detection bundles; local AI reduces the perceived necessity of a subscription and can raise churn at renewal. Second-order winners may be the chip/content layer behind on-device compute: edge AI cameras, locks, and hubs need better SoCs, memory, power management, and low-latency connectivity, which supports the thesis for names tied to embedded AI rather than pure cloud software. Retail channel partners also benefit if upgraded devices increase attach rates across cameras, locks, and hubs, but the margin pool likely shifts toward hardware mix rather than expanding overall category profitability.
Near term, this is mostly a sentiment and roadmap signal, not a hard revenue catalyst, so the first watch item is channel data over the next 1-3 months: shelf space, ASPs, and whether subscription attach rates weaken in security camera and doorbell cohorts. Over 6-18 months, the risk is that edge AI becomes table stakes, forcing incumbents to spend more on silicon integration while accepting lower recurring revenue per device. The thesis is falsified if public peers continue to grow paid services faster than unit shipments, or if consumers prioritize ecosystem lock-in over local privacy features.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- Watchlist: ARLO as the cleanest public proxy for subscription risk from local-AI cameras; do not short immediately, but look to fade rallies if next quarter shows weaker paid user growth or retention.
- Conditional pair trade: short ARLO / long a diversified edge-AI beneficiary such as QCOM or AMBA only if channel checks confirm that local inference is driving incremental camera and hub demand rather than just replacing cloud features.
- Avoid paying up for cloud-reliant smart-home platforms until 1Q channel data confirms subscription attach resilience; the first falsifier is stable or improving ARPU despite broader local-AI adoption.
- Set an alert on AMZN/Ring and GOOGL/Nest ecosystem commentary: if they respond with local processing upgrades, the competitive pressure on smaller security vendors likely intensifies over the next 2-4 quarters.
- If using the theme tactically, favor suppliers to embedded AI content over finished-device OEMs; hardware mix can help, but the biggest economic leverage should accrue to the chip layer if this architecture shift broadens.
More News
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Asian stocks skid, Wall Street and bonds aided by oil slip
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- Zoom and big financial firms add ‘Proof of Human’ badges from Sam Altman’s World to stop fraud and deep fakes