
Mindray North America celebra la inauguración oficial de su almacén ampliado en Mahwah
Source: PR Newswire
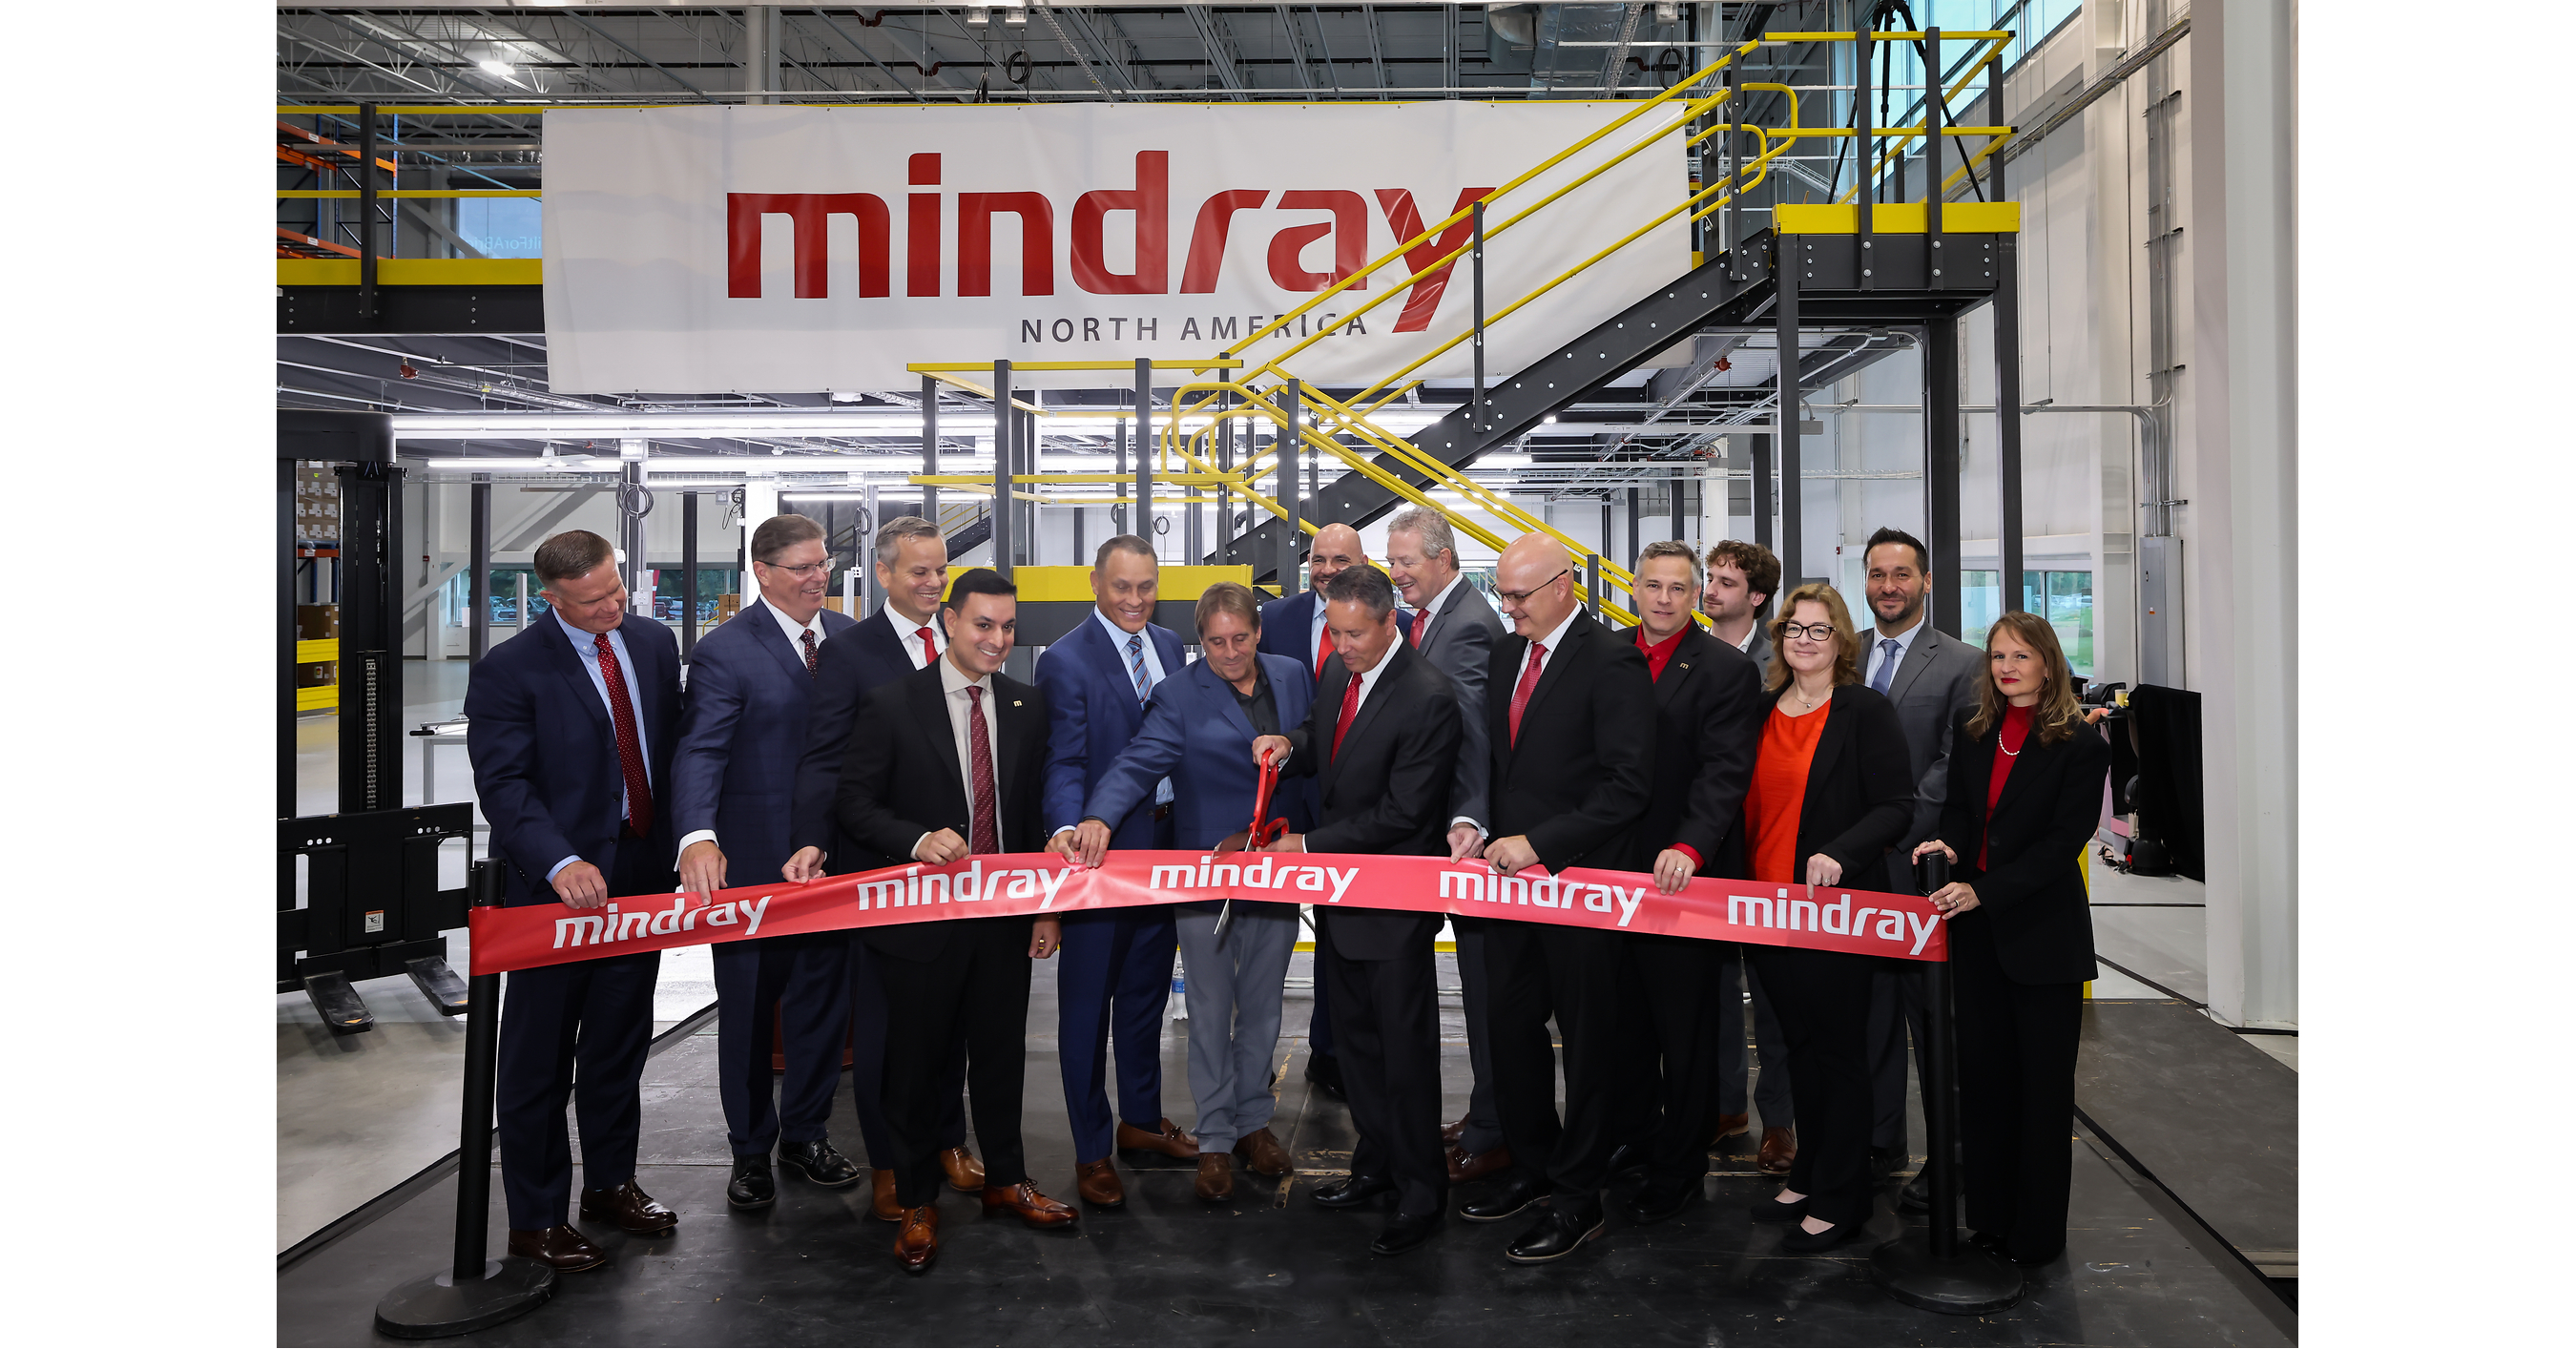
Mindray North America completó una inversión “multimillonaria” para centralizar operaciones externas en una sede, con el objetivo de optimizar logística, mejorar la gestión de pedidos y reducir complicaciones de envío. La expansión busca recortar plazos de entrega y fortalecer una cadena de suministro más resiliente y sostenible, reduciendo transporte por carretera y la huella de carbono al consolidar envíos. En paralelo, la empresa acelera una diversificación de portafolio (incluida una nueva línea de respiradores) con ampliaciones previstas en los próximos 18 meses.
Analysis
This reads more like an execution upgrade than a demand inflection, so the near-term P&L impact is likely modest. The real mechanism is commercial: better domestic logistics and shorter lead times matter most in acute-care devices where procurement cycles are slow but switching costs are low once service reliability slips. That can improve win rates in mid-market hospitals and buying groups, especially in monitors, ventilators, and perioperative equipment where downtime and installation friction are hidden losses.
Second-order, the bigger effect is on competitive positioning rather than current revenue. If Mindray can ship and support faster in North America, it narrows the service moat of larger incumbents whose advantage is installed base plus field support, not product superiority. That could pressure renewal pricing and spare-parts economics for GE HealthCare and, to a lesser extent, Medtronic and Philips in categories where buyers benchmark total cost of ownership more than brand.
The contrarian view is that investors may overread a warehouse/consolidation story as a growth signal. Without evidence of backlog conversion, GPO wins, or margin expansion, the move mainly improves fill rates and working capital, not terminal value. The key falsifiers are flat U.S. order growth over the next 1-2 quarters, no improvement in delivery times, or any sign that hospital capex remains deferred as budgets tighten into year-end.
Over 6-18 months, the optionality is the broader product rollout: if the expanded footprint helps Mindray land an installed base ahead of new ventilator launches, consumables and service revenue can compound with better margin mix. But that only matters if they can convert distribution capacity into recurring utilization; otherwise this is a cost-efficiency story, not a share-gain regime.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No direct single-name trade on the headline; treat as a monitoring item until there is evidence of U.S. share gains or margin lift over the next 1-2 quarters.
- Relative-value alert: consider a modest long GEHC / short IHI basket only if Mindray commentary starts showing faster North America order growth or backlog conversion; otherwise the signal is too weak to short incumbents on its own.
- If hospital-capex sentiment improves, use this as a secondary positive for IHI over XLV on a 3-6 month horizon, because logistics improvements tend to benefit equipment-heavy names first, but keep sizing small given limited read-through.
- Set a falsifier around next earnings: if Mindray does not show lower lead times, improved North America bookings, or any margin expansion, fade any initial optimism and avoid chasing the stock or peers.
- Watch ventilator/ICU equipment peers for pricing pressure; if Mindray’s U.S. distribution gains coincide with softer dealer inventories, a short-term relative short in higher-cost service models could emerge, but only after hard data confirms it.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate
- Meta is breaking out after introducing Muse AI agent. Where the stock is going, according to the charts