
NetCarrier Appoints Jason Ruth as Chief Revenue Officer
Source: PR Newswire
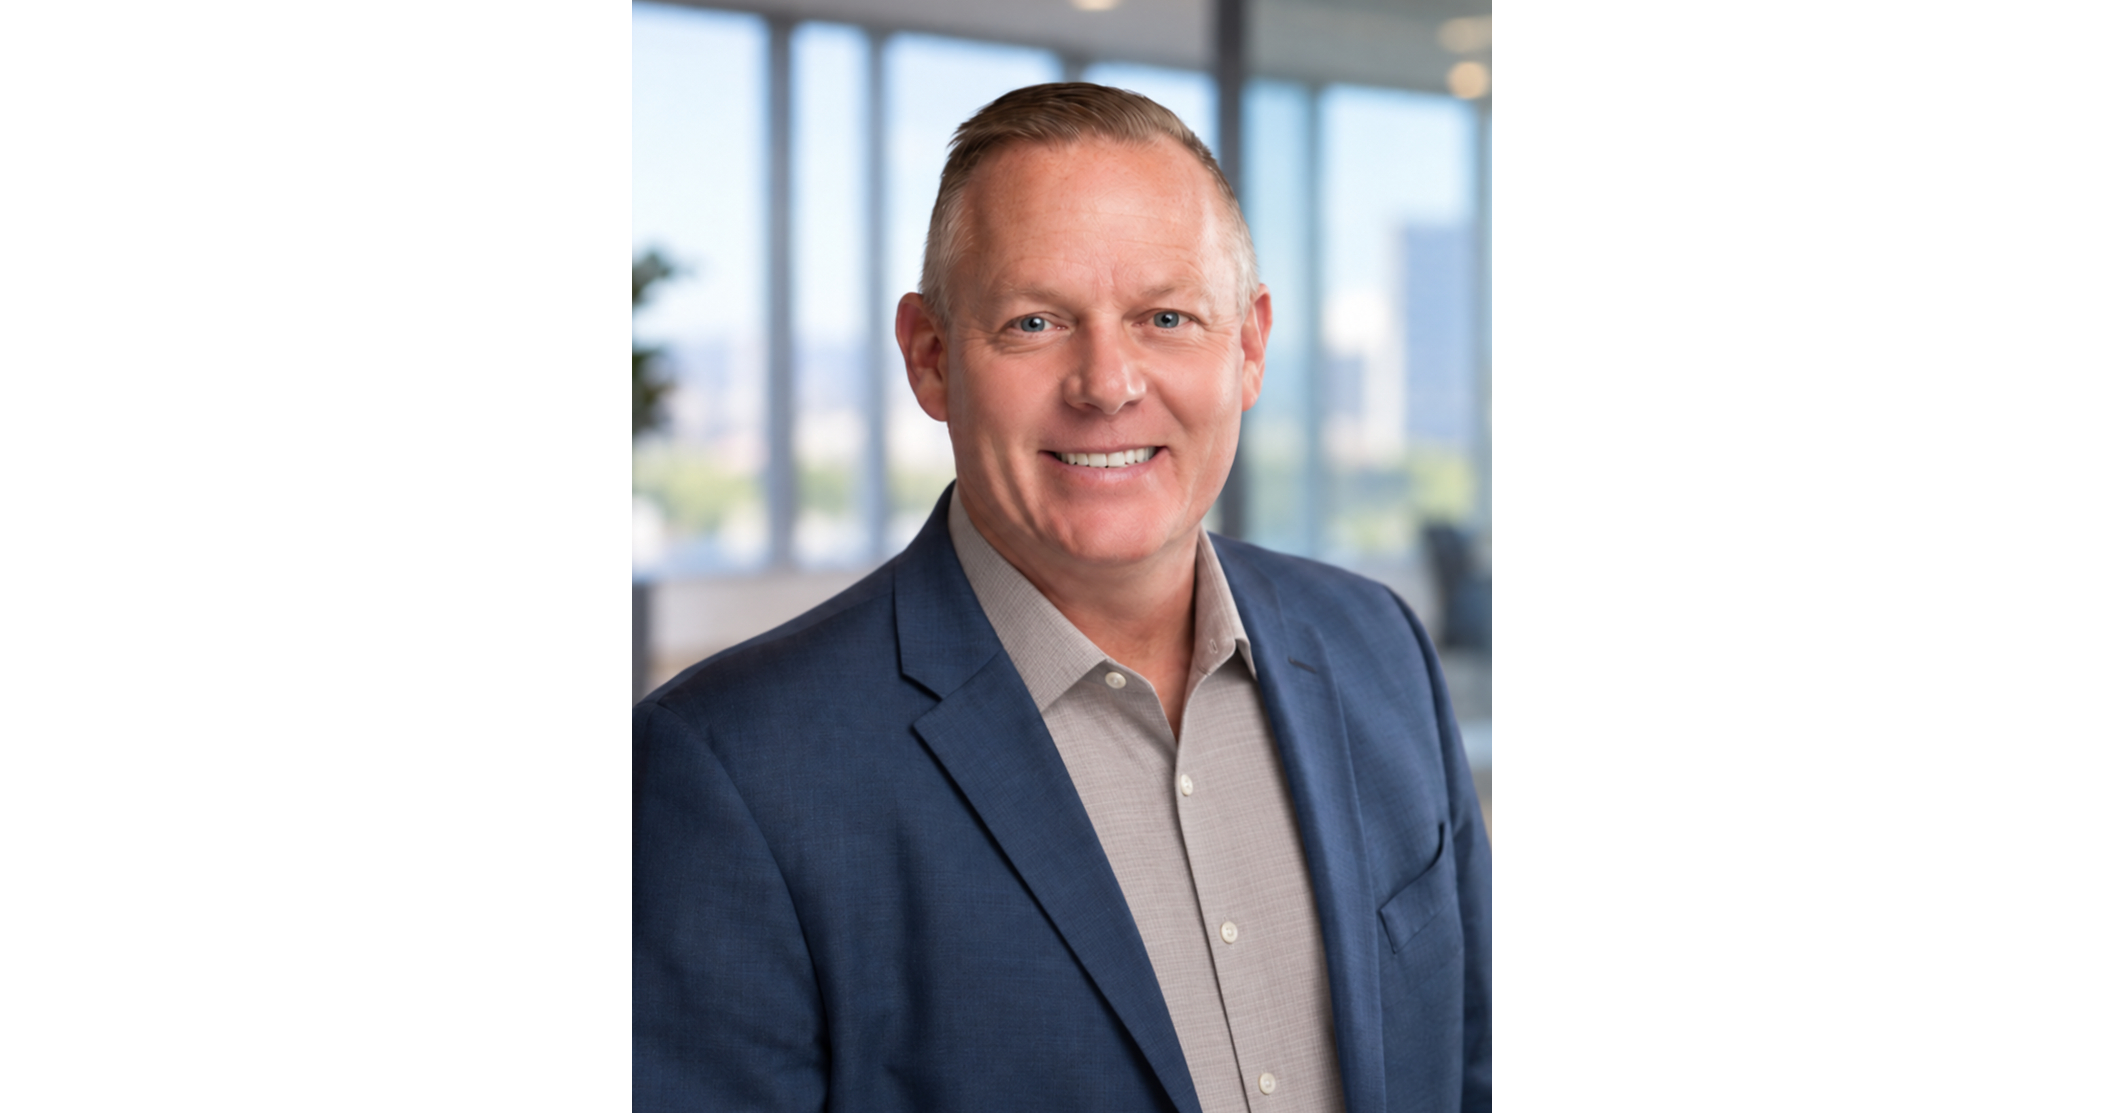
Privately held NetCarrier appointed Jason Ruth as chief revenue officer, effective July 13, 2026, to lead long-term revenue growth, channel partnerships, wholesale initiatives and white-label expansion. Ruth brings more than 25 years of sales and channel leadership experience, most recently as C1's Director of Sales, East. The appointment supports NetCarrier's effort to expand its cloud communications and AI-powered voice automation offerings for small and mid-sized businesses.
Analysis
This is not a tradable fundamental catalyst for listed communications peers: a private vendor’s commercial hire provides no independently verifiable bookings, retention, pricing, or unit-economics signal. The more relevant read-through is that channel distribution remains central to SMB voice/UC adoption, where incumbents with established MSP/TSD relationships can defend customer acquisition costs and cross-sell AI features without relying solely on expensive direct sales.
Competitive pressure is most likely at the low end of UCaaS and contact-center markets, where feature parity makes white-label distribution a source of price compression rather than a durable moat. Public vendors such as 8x8 (EGHT), RingCentral (RNG), and Zoom (ZM) would only face material exposure if channel-led alternatives begin winning measurable seat migrations or forcing lower net revenue retention; there is no evidence of that here. AI voice automation could expand attach rates, but it may also cannibalize billable agent seats, making revenue recognition and gross-margin effects dependent on whether automation is priced per interaction rather than bundled.
Over the next 1-3 months, the actionable catalyst is sector-level evidence from earnings: partner-sourced pipeline, SMB churn, AI-contact-center attach rates, and sales-and-marketing efficiency. Over 6-18 months, the structural risk for smaller UCaaS providers is distributor-led commoditization, while scaled platforms with proprietary workflow/data integrations should retain pricing power. A sustained acceleration in EGHT or RNG net retention and AI-related bookings would falsify the price-compression concern; absent such data, this announcement should not move public-market positioning.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No standalone trade in ASCN: confirm ticker mapping and public float before action; the disclosed company is privately held and the event contains no valuation-relevant financial disclosure.
- Maintain a watchlist on EGHT and RNG into the next earnings cycle; consider a short only if SMB churn rises or net revenue retention/guidance deteriorates while AI attach-rate commentary fails to offset sales-and-marketing spend. Cover on improved retention or material AI ARR disclosure.
- Prefer ZM over smaller UCaaS peers on a 6-18 month relative basis only if evidence emerges that AI automation is sold as a paid workflow layer rather than bundled voice functionality; use EGHT as the relative short leg, with quarterly enterprise/SMB retention as the key falsifier.
- Monitor TSD/MSP channel checks for seat migrations, wholesale pricing, and white-label win rates. Treat evidence of broad discounting as an alert for UCaaS multiple compression, not as a conclusion from this personnel announcement.
More News
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- California AG Bonta on Paramount-Warner Bros., Meta and AI
- A breakout in the 10-year Treasury yield could hold back stocks if it reaches this level
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research