
Huawei представляет обновленную сеть Stellar AI для обеспечения безопасного и интеллектуального подключения к агентскому миру
Source: PR Newswire
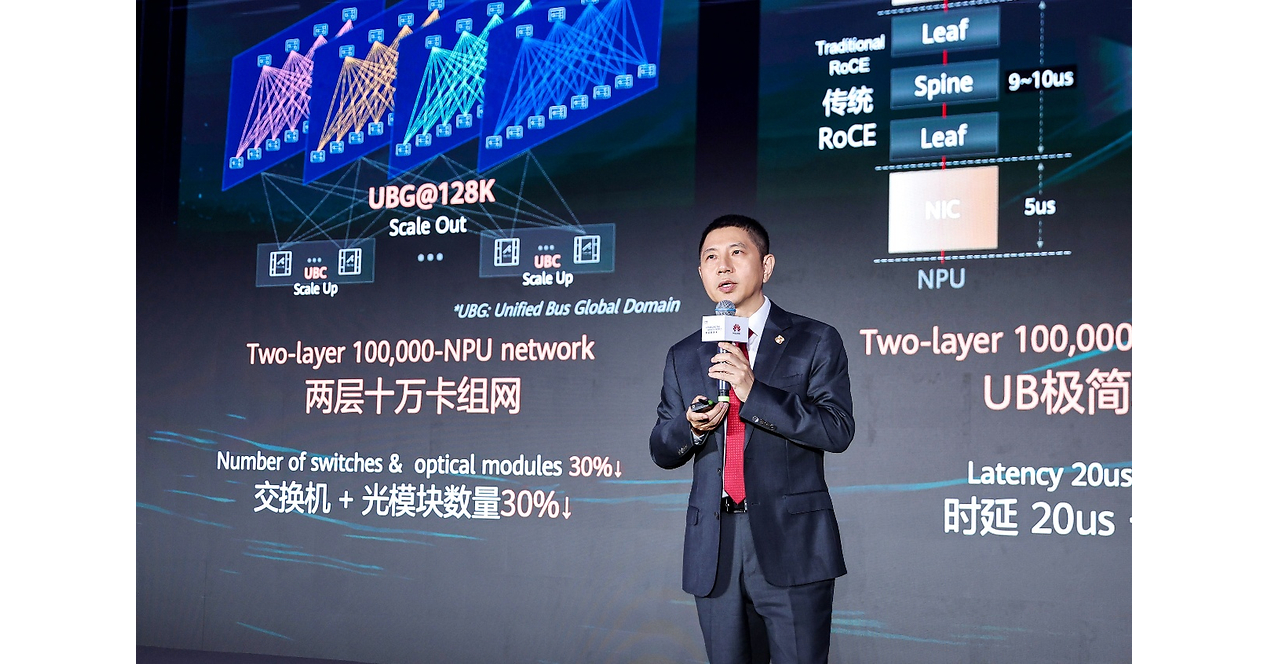
Huawei unveiled its upgraded Stellar AI Network at HUAWEI CONNECT 2026, targeting AI data-center, WAN and campus connectivity as daily AI token consumption has increased 260x year over year. The AI Fabric 2.0 claims 30% lower network deployment costs, latency reduced from 20 microseconds to 11 microseconds, and zero packet loss during link switching; its XH9300-EN switch cuts interconnect power use from 1,000W to 600W. Huawei also cited security detection rates above 95%, remote-computing efficiency above 95% over 1,000 km, and campus-network MTTR below five minutes, positioning the offering as an enterprise AI infrastructure and security upgrade.
Analysis
Huawei’s unlisted status shifts the investable implication to competitive pressure rather than direct ownership. Its integrated AI networking-and-accelerator stack is most relevant in China and sanctioned markets, where domestic substitution can reduce the addressable market for NVIDIA (NVDA) InfiniBand/Ethernet, Arista (ANET), Broadcom (AVGO) switching silicon and Cisco (CSCO) enterprise networking. The near-term revenue effect for US vendors is likely limited by export controls already constraining their highest-end offerings, but the second-order risk is that a credible domestic reference architecture lowers Chinese customers’ willingness to return to US ecosystems even if restrictions ease.
The key issue is whether Huawei can convert performance assertions into repeatable cluster deployments and third-party software compatibility. If it does, the pressure is greater on premium gross margins than on global unit volumes: AI-fabric buyers increasingly evaluate total cluster utilization, power and serviceability rather than port speed alone. Over 6-18 months, this could reinforce a bifurcated AI infrastructure market—US-led systems in allied hyperscalers, Huawei-led stacks in Chinese enterprises and sovereign deployments—reducing the valuation premium attached to a single global networking standard.
Consensus may overestimate the immediate threat to ANET: its hyperscaler exposure, installed-base software and supply-chain qualification cycles remain substantial defenses, while Huawei’s claims are promotional and lack independently audited throughput, failure-rate and customer economics. The more actionable signal is for Chinese procurement data, Ascend server shipments, and evidence that local cloud providers standardize on Huawei networking; absent these, this is not a standalone catalyst. A material thesis reversal would be renewed broad access for Chinese customers to leading US AI accelerators and networking, or evidence that Huawei deployments require sustained price discounts and elevated support costs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain, rather than add to, any 1-3 month short ANET or CSCO exposure solely on this announcement; require evidence of at least two large-scale Chinese production wins or a downward revision to China-related networking guidance before acting.
- For a 6-12 month relative-value hedge, consider long ANET / short CSCO only if ANET’s hyperscaler order commentary remains intact: Huawei’s principal addressable market overlaps more directly with CSCO’s enterprise and campus portfolio, while ANET retains stronger exposure to US cloud capex. Exit if ANET guides cloud revenue growth below 20% or reports meaningful China-driven pricing pressure.
- Monitor NVDA and AVGO China revenue disclosures and export-control developments around the next earnings cycle. A disclosed deterioration in China demand not offset by sovereign or US hyperscaler demand would support reducing AI-infrastructure beta; this product release alone does not justify it.
- Watch China-listed network-security and telecom-equipment proxies such as ZTE (0763.HK) for procurement spillover, but treat as an alert rather than a recommendation until contract awards, margins and component sourcing are independently visible.
More News
- Google's Gemini becomes latest AI model to break out and hack computer systems
- Trump says U.S. to build a 'large Military presence' in Greenland as part of a security deal with it and Denmark
- UBS now expects AI capex to reach nearly $1tn this year and around $1.4tn by 2027
- Stocks face a key hurdle in next week’s U.S.-China summit. Here’s what’s at stake
- Houthis accuse Saudi Arabia of launching 26 strikes in 24 hours
- European Economies Eye Another Energy Crisis Heading Into Winter