
L'usine GAC Cambodia KD démarre sa production et établit une nouvelle référence en matière de fabrication locale
Source: PR Newswire
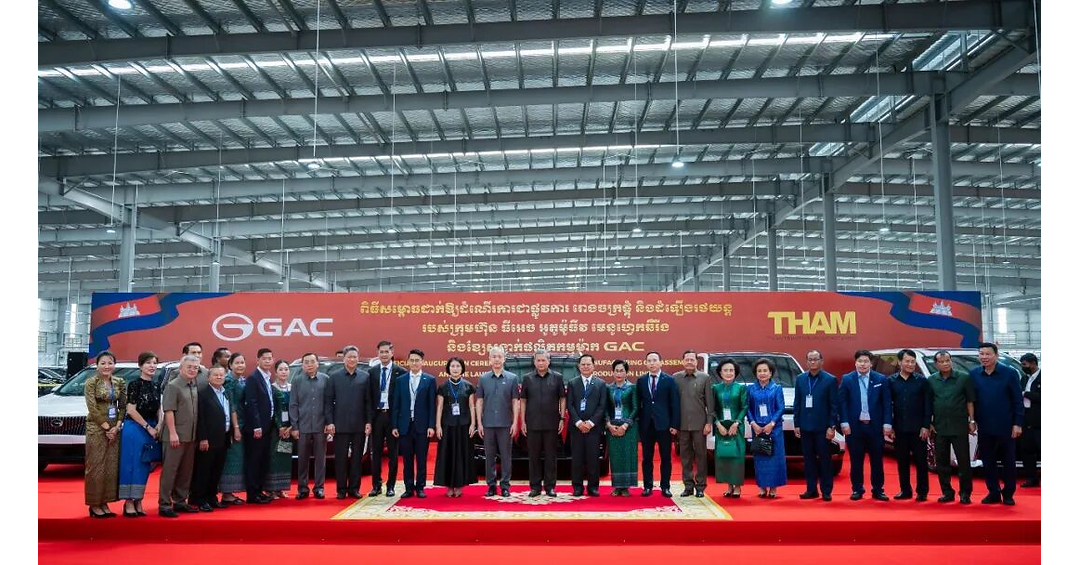
GAC has begun production at its Cambodia KD assembly plant in Kampong Chhnang, shifting from fully built vehicle imports to local manufacturing with planned annual capacity of about 10,000 units. The facility, developed with TH Group, is intended to provide local assembly, jobs and technical capability, while GAC supplies CKD kits and production support. GAC says its TRUMPCHI brand has posted a more than 300% average annual growth rate in Cambodia over the past three years and ranked first among Chinese auto brands in the country in 2025.
Analysis
This is not a material earnings event for the TH ETF; the referenced local partner is not an investable proxy, and Cambodia’s passenger-vehicle market is too small for a 10,000-unit assembly line to alter regional auto-sector valuations. The relevant listed exposure is GAC Group (2238 HK / 601238 CH), where the capital-light CKD structure shifts fixed-asset and local execution risk to the distributor while preserving kit sales and technical-service revenue. The near-term financial contribution is likely immaterial, but the model can improve GAC’s ASEAN unit economics if local assembly secures tariff advantages and lowers working-capital intensity versus fully built vehicle exports.
The more important second-order effect is competitive: localized Chinese capacity raises the probability of price competition across ASEAN’s lower-cost ICE and hybrid segments. BYD (1211 HK), Geely (175 HK), Great Wall Motor (2333 HK), and SAIC (600104 CH) may need to respond with local-content, financing, and dealer-support spending, pressuring regional margins before volumes become large enough to offset it. GAC’s claimed growth trajectory is not independently sufficient to underwrite a demand forecast; dealer inventory, retail registrations, and discounting are the key missing data.
Over 1-3 months, this is primarily a sentiment and strategic-optionality datapoint rather than a catalyst for estimates. Over 6-18 months, repeatable CKD rollout across ASEAN could modestly support GAC’s export mix and reduce exposure to domestic Chinese price deflation, but it also creates reliance on policy stability and a local distributor’s balance sheet. The thesis fails if registration growth stalls after launch, inventories rise, or tariff/local-content rules change such that assembly no longer produces a meaningful landed-cost advantage.
Contrarian view: investors may overvalue factory announcements as evidence of durable overseas demand. A small CKD facility can be commercially rational as a tariff and channel-defense tool without proving brand power; the first evidence worth paying for is sustained sell-through at limited incentives, not nominal capacity or ceremonial support.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No position in TH on this news: treat the ticker linkage as non-economic unless a verified portfolio holding or corporate relationship is identified.
- Place GAC Group (2238 HK) on a 1-2 quarter watchlist rather than initiate a directional trade; require evidence of ASEAN retail registrations, dealer inventory discipline, and export-margin disclosure before attributing valuation upside to localization.
- Monitor a relative-value setup: long 2238 HK versus short a broader China auto basket only if GAC demonstrates sequential export-volume growth without incremental discounting. Use a 10-15% relative stop-loss; falsify on weaker export mix or higher dealer incentives.
- For holders of BYD (1211 HK), Geely (175 HK), Great Wall (2333 HK), and SAIC (600104 CH), watch ASEAN pricing and local-content announcements over the next 6-12 months. Broad Chinese OEM localization would be margin-negative for the group even if unit growth remains strong; reduce exposure if regional incentives accelerate faster than deliveries.
More News
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Here's who we know is going to the Trump-Xi dinner so far
- How a Bangladeshi garment-maker is fighting the Middle East energy crunch
- +17% in a single session: This AI-picked stock catches a data-center breakout
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Alternative Data Due Diligence for Institutional Investors
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors