
Russo's New York Pizzeria Opens Second Arizona Location in Tempe
Source: PR Newswire
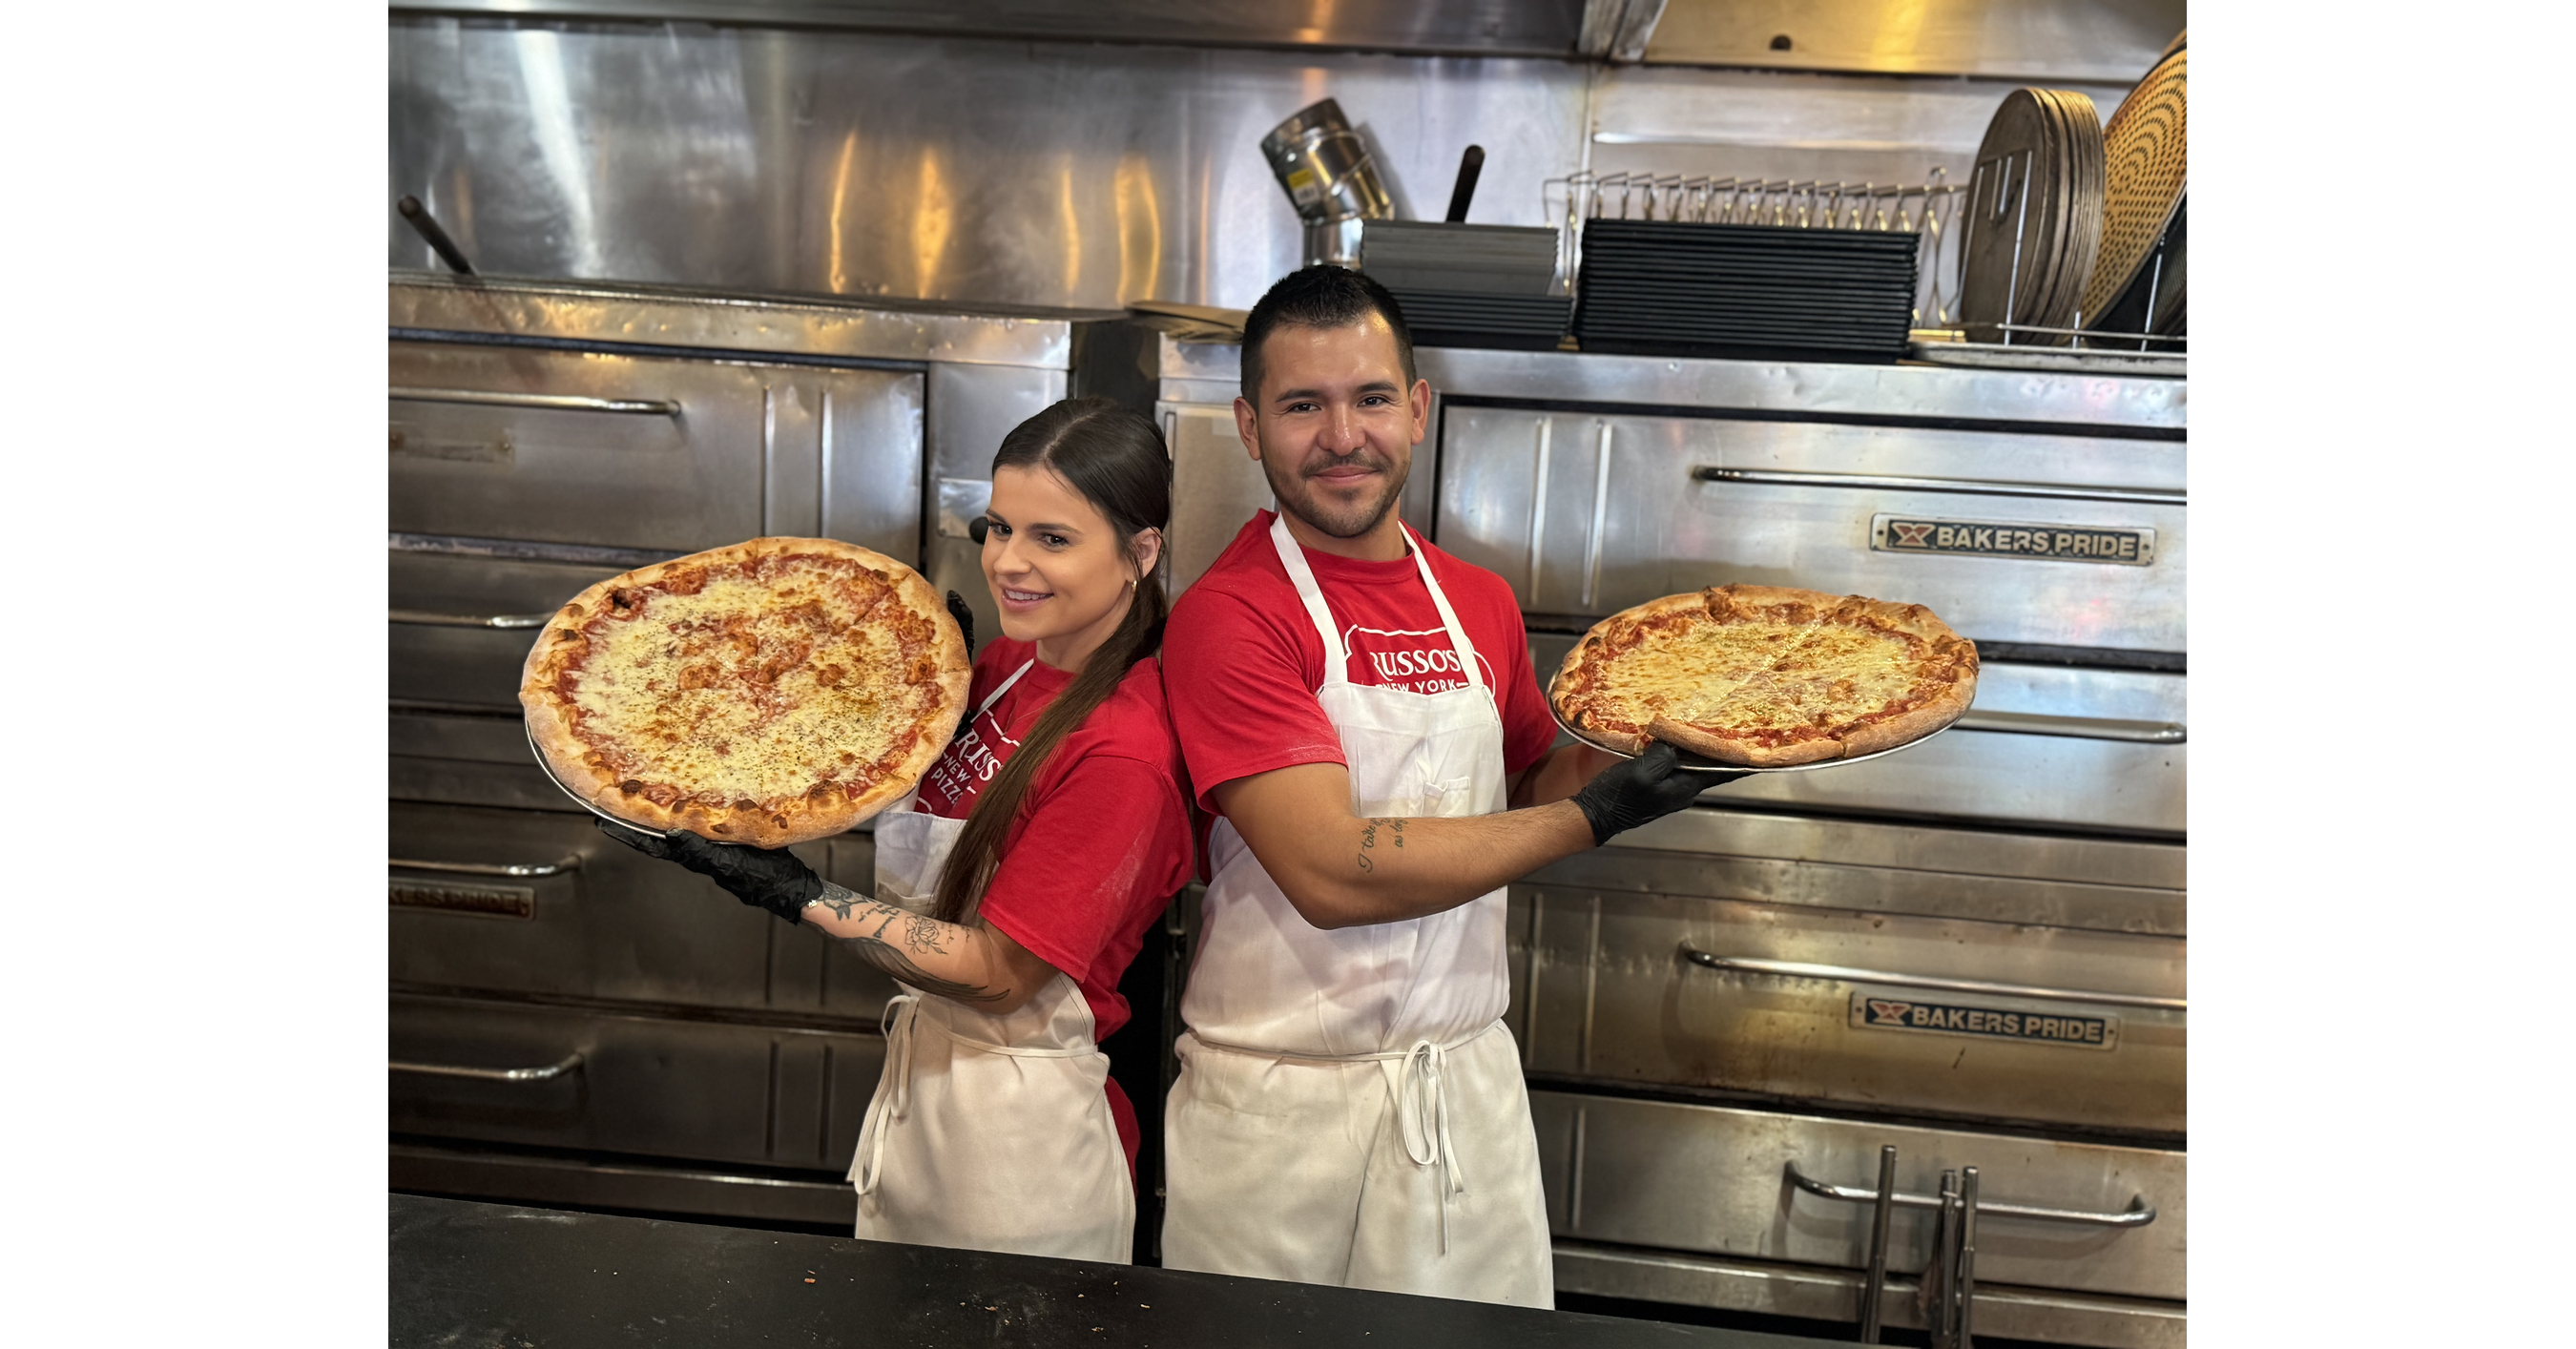
Russo's New York Pizzeria opened its second Arizona location in Tempe, advancing its franchise expansion across the Southwest and broader U.S. The company cited franchised average unit volumes of approximately $1.1 million and offers compact restaurant formats beginning at roughly 1,500 square feet. The opening targets ASU students, residents, businesses and visitors, but is unlikely to have material public-market impact.
Analysis
This is not investable as a standalone event: Russo's is privately held, the unit opening is immaterial to public restaurant-sector earnings, and the cited unit-volume metric is franchise marketing rather than independently comparable same-store-sales or cash-on-cash-return data. The relevant read-through is limited to whether value-oriented, occasion-driven restaurant traffic around university campuses remains resilient as consumers trade down from full-service dining.
A scratch-made, premium-input positioning creates a structurally higher food-cost and labor-intensity profile than scaled quick-service pizza. If the format expands, it is more exposed to dairy, wheat, protein, and wage inflation, while lacking the purchasing scale, digital ordering ecosystem, and delivery leverage of Domino's (DPZ), Papa John's (PZZA), or Yum! Brands' Pizza Hut system (YUM). Conversely, a successful small-footprint model would underscore continued fragmentation in independent pizza, but is unlikely to alter national chains' economics.
For the next 1-3 months, use Tempe-area restaurant commentary only as a micro signal for student and local discretionary demand; it should not change sector positioning. Over 6-18 months, the more important competitive variable is whether national chains defend value through promotions, which can pressure franchisee margins even if traffic holds. The thesis that premium local pizza can take meaningful share is falsified if DPZ/PZZA report stable transaction growth and improving franchisee profitability while independent operators face renewed food or labor inflation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No direct trade: do not treat a single private-franchise opening as a catalyst for DPZ, PZZA, YUM, or broader restaurant ETFs.
- Maintain DPZ as the preferred public pizza exposure over PZZA on scale, digital mix, and franchisee economics; reassess only if quarterly U.S. transaction trends decelerate materially or value promotions begin compressing margins.
- Watch wheat, mozzarella/dairy, and Arizona minimum-wage trends over the next 6-12 months as leading indicators of margin stress for subscale independent pizza operators; this becomes relevant to public peers only if commodity inflation forces industry-wide pricing or promotion changes.
- For a consumer-demand read-through, prioritize upcoming same-store-sales and traffic disclosures from DPZ, YUM, and campus-exposed fast-casual operators rather than extrapolating from local expansion announcements.
More News
- Jensen Huang’s $21 billion net worth in AI rout—Nvidia’s recovery will be ‘capped’ after he admitted affair with alleged Chinese spy
- Nvidia's CEO turmoil gives newly empowered Democrats fresh ammunition in pursuit of oversight
- Paraguay raids ex-president’s home: Why a bank crash brought down Pena
- Eli Lilly’s Foundayo obesity pill eases sleep apnea in late-stage trial, paving way for approval
- Musk says Tesla will refund some Cybertruck deposits, defends decision to end production
- Weekend trading of Nvidia scandal shines light on new financial products