
Theory Wellness Announces New St. Paul, Minnesota Recreational Cannabis Dispensary Opening September 15th
Source: Newswire
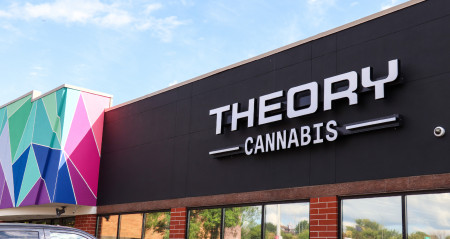
Theory Wellness will open its first Minnesota recreational cannabis dispensary in St. Paul on September 15, 2026, expanding its footprint to 14 dispensaries across six states. The vertically integrated location includes on-site cultivation and production visible to customers through in-store grow windows, supporting fresh product supply and a differentiated retail experience. The company will offer its own cannabis portfolio alongside locally produced third-party products.
Analysis
This is not directly investable because Theory Wellness is private, and a single store opening does not establish Minnesota demand, pricing, or unit economics. The relevant read-through is that vertically integrated entrants are allocating capital to experiential retail rather than discount-led share capture, implying management expects early adult-use consumers to reward branded quality and convenience. That could modestly support wholesale realization for established Minnesota operators, but attached cultivation also reduces Theory’s dependence on third-party suppliers and adds localized price competition over the next 6-18 months.
The near-term variable is regulatory throughput: dispensary openings can create temporary scarcity-driven traffic, but durable revenue depends on cultivation-license expansion, municipal restrictions, and the pace at which competing retail licenses become operational. On-site cultivation is operationally differentiated but not necessarily margin accretive; indoor grow economics are highly exposed to power costs, labor intensity, compliance overhead, and utilization. A broad decline in flower pricing as state supply ramps would make this format a fixed-cost liability rather than a premium-brand advantage.
For public markets, the cleaner exposure remains the broader U.S. cannabis regulatory and capital-markets trade rather than this opening. MSOS constituents with balance-sheet capacity and multistate operating infrastructure could benefit if Minnesota becomes a meaningful incremental market, while Canadian LPs with limited U.S. cash-flow participation should not receive a fundamental read-through. There is no evidence here to revise earnings estimates or initiate a single-name position.
Contrarian view: investors may overvalue first-mover retail narratives in newly legal states. Early store volumes often reflect constrained access and novelty, not repeatable customer economics; the key falsifier is whether basket size, loyalty retention, and realized gross margin remain intact after competing supply and storefront density increase over the next 2-4 quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No immediate trade from this announcement; keep Minnesota as a state-level demand and pricing monitor rather than an earnings catalyst.
- Use MSOS as the liquid watch proxy for U.S. cannabis-policy beta, but only add on independently confirmed federal reform momentum or accelerating state-market sales data; this store opening alone does not alter risk/reward.
- Monitor Minnesota monthly adult-use sales, wholesale flower prices, license issuance, and retail-store count over the next 3-6 months. A rapid increase in cultivation and retail capacity would be negative for localized gross margins and argues against extrapolating early sales.
- For any long MSOS exposure, define thesis failure as a delay in federal catalysts combined with broad state-level price compression; reduce if the ETF breaks below its pre-catalyst support level on rising volume rather than averaging into regulatory disappointment.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid