
Disney Cruise Line Returns to New York City, Offers More Ports to Explore in Fall 2027 and Spring 2028
Source: PR Newswire
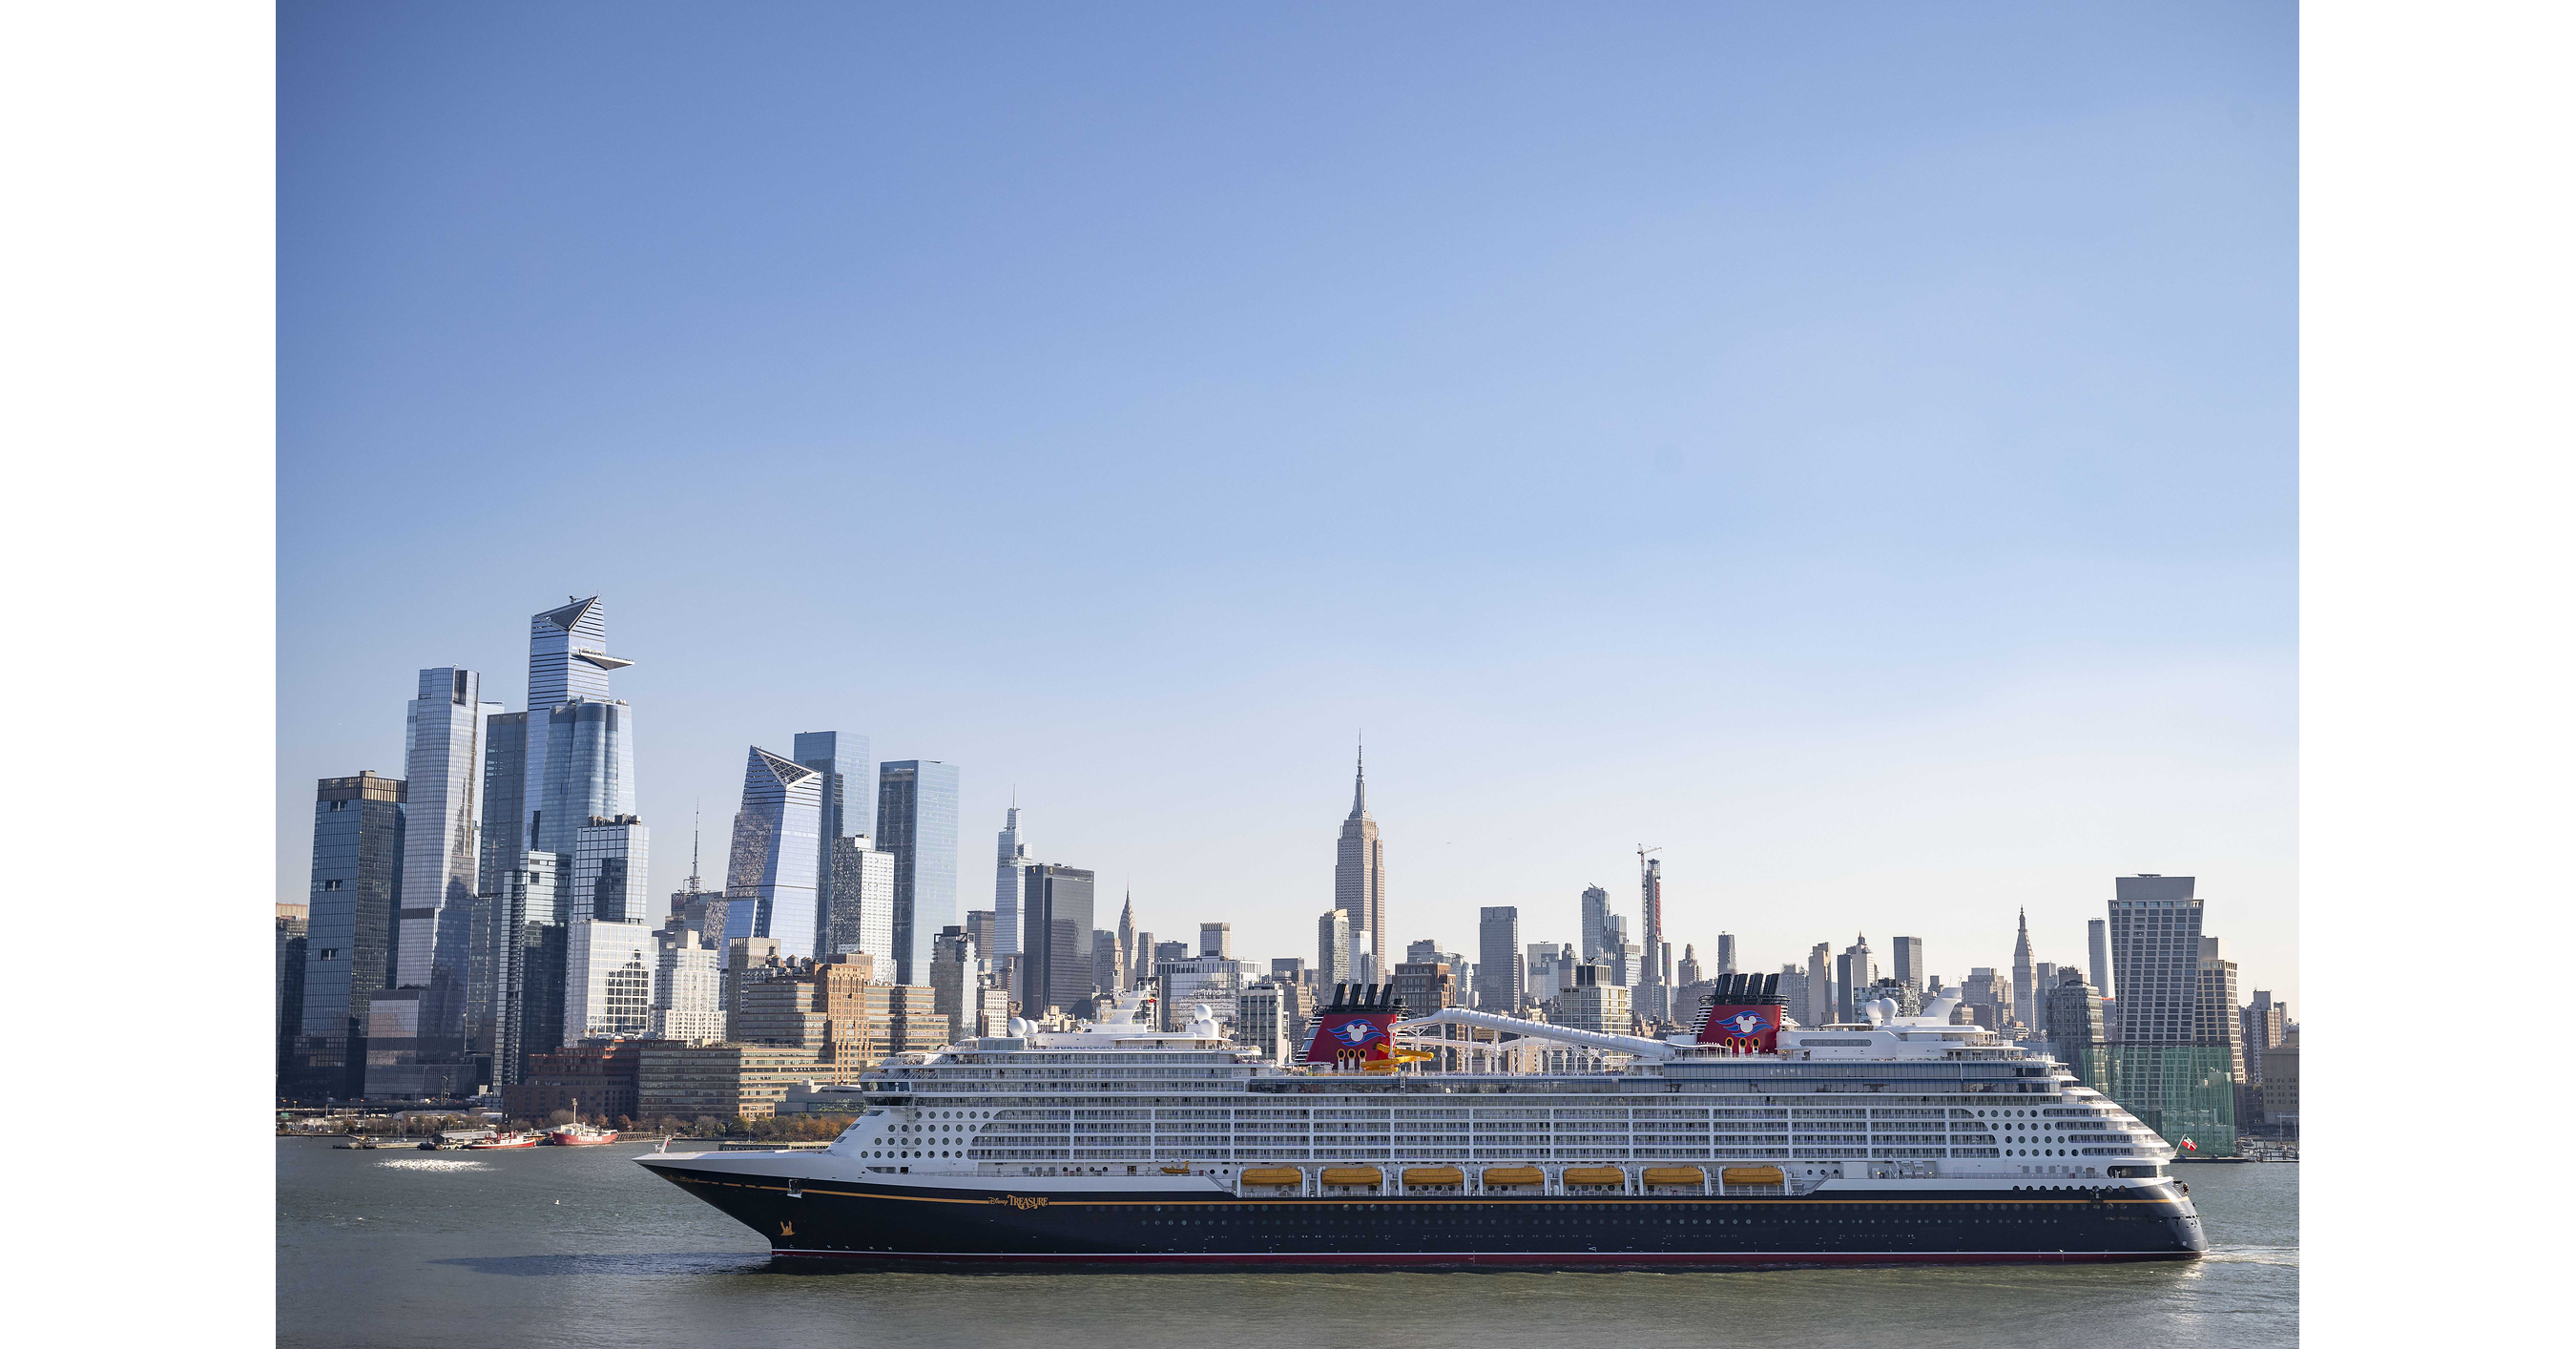
Disney Cruise Line announced Fall 2027 and Spring 2028 itineraries, including a return to New York City (first since 2023) with the Disney Wish arriving in late September and adding maiden port calls in Panama (Fuerte Amador and Colon). The lineup expands departures from San Juan, Puerto Rico, and adds new Singapore sailings with a new port call in Langkawi, Malaysia starting Dec. 31, 2026, plus holiday cruise programming (Halloween and “Very Merrytime”) in late 2027. Early bookings open Aug. 31, 2026 for Castaway Club members and general bookings begin Sept. 8, 2026.
Analysis
This reads more like a capacity-allocation signal than a true incremental demand shock. The important takeaway is that Disney is using its best asset, brand pricing power, to keep premium berth inventory filled across higher-value routes and long-lead bookings, which supports forward visibility more than current-quarter EPS. For DIS, the cruise business can move sentiment disproportionally because it carries a higher margin mix than many legacy entertainment assets, so even modest yield improvement matters to valuation more than the headline itself.
The competitive read-through is most relevant for RCL, with secondary pressure on CCL and NCLH: Disney is leaning harder into family-premium itineraries, private-island differentiation, and destination scarcity, which can siphon demand from higher-end family cruisers rather than the mass-market bucket. The 1-3 month catalyst is booking cadence and deposit behavior into the early booking window; if the market sees strong fill rates at unchanged or higher pricing, DIS can get a small but durable estimate revision. If bookings merely track normal seasonality, the move should fade quickly.
The contrarian point: the market may underappreciate how much of cruise economics is driven by route mix and yield management, not just ship count. That said, this is still a long-dated commercial announcement, so the thesis weakens fast if management does not cite accelerating booking windows, higher onboard spend, or sustained pricing in the next update. The main falsifier is any evidence that premium family travel softens into 2027, particularly if consumer discretionary data or cruise sector commentary points to discounting.
Second-order, the Panama/Singapore repositioning suggests Disney is maximizing utilization of the fleet, which is constructive for asset productivity and depressing for peers trying to buy the same premium customer. The bigger upside is structural: as the fleet matures, cruise can become a steadier cash engine that partially offsets cyclical weakness elsewhere in DIS, but that is a 6-18 month story rather than a day-trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Tactically add DIS on any post-news weakness, but size modestly: the setup is about forward yield visibility, not immediate earnings uplift. Best entry is into the early booking window; thesis works if management later confirms strong deposits and premium pricing.
- Pair trade: long DIS / short CCL for 1-3 months. Disney has the cleaner premium-family moat and better ability to defend pricing; invalidation would be any sign that CCL is sustaining higher occupancy without discounting pressure.
- For a cleaner sector expression, consider long DIS vs short a cruise ETF or basket proxy into the next booking-data update, with a tight stop if cruise commentary turns promotional or if RCL reports accelerating discounting.
- Watch RCL closely rather than chasing it here: if Disney’s premium routes are filling faster than expected, that is the tell that family demand is still willing to pay up. If RCL guides to softer Caribbean yields, this becomes a stronger relative-value short.
- No options trade is necessary unless a later earnings print confirms pricing power; if so, call spreads in DIS can express a 6-18 month margin-mix thesis with limited downside.
More News
- Disney offered a 13-year-old $2 million to sing in The Lion King—his mom took $100k plus royalties instead. He’s still getting paid 32 years later
- Oil Falls as Trump Says US Will Not Attack Iran Before Midterms
- Jim Cramer's top 10 things to watch in the stock market Thursday
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition