
Roborock Redefines Human-Centered Cleaning at IFA 2026: Unveiling a Comprehensive Ecosystem from the Living Room to the Pool
Source: PR Newswire
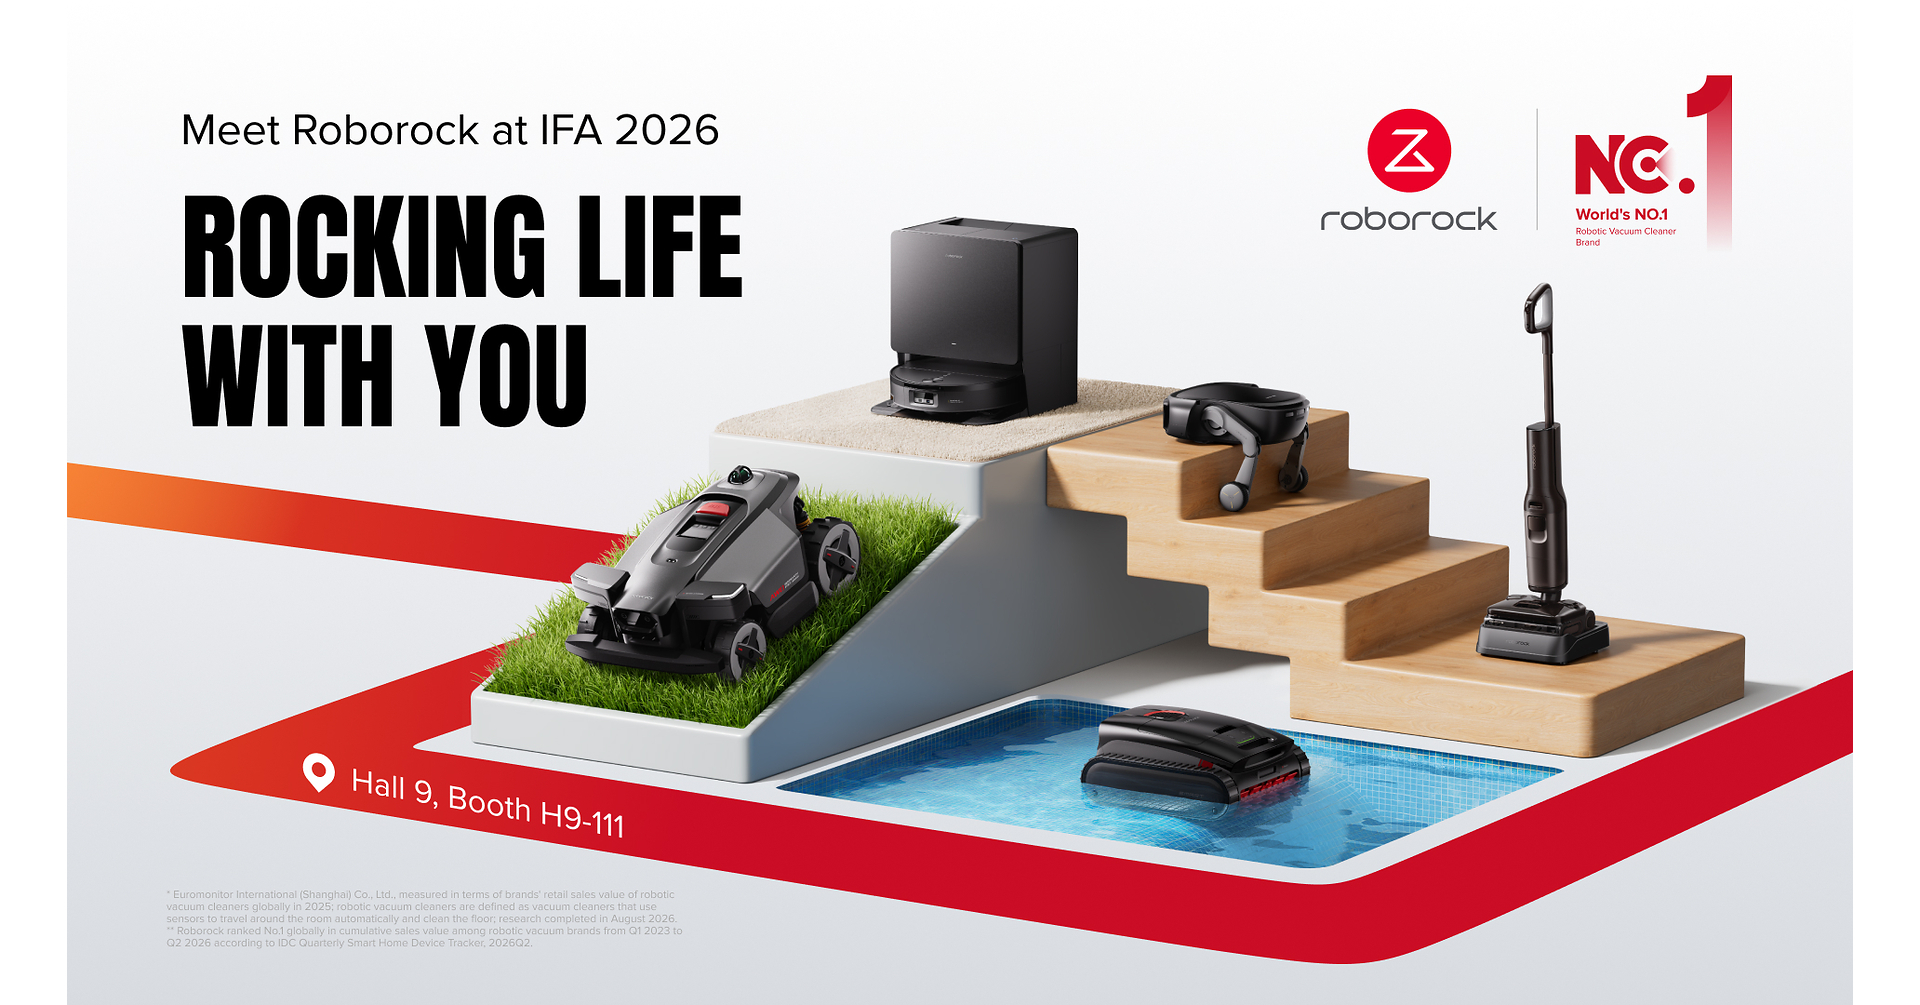
Roborock is showcasing a broad 2026 home-cleaning ecosystem at IFA, including its first pool cleaner, the RockAqua P1, featuring 6,800 GPH suction, a 4L dual-filtration debris basket, and up to 3.5 hours runtime with 3.5-hour recharge. The lineup also highlights new vacuum and wet-dry models (e.g., 36,000 Pa HyperForce suction systems, up to 8.8 cm threshold crossing) and a new LiDAR robotic mower (coverage up to 800 m²). The company reiterates scale traction—#1 best-selling robotic vacuum brand in H1 2026 (IDC)—and expanding household reach to 30M+ as of August 2026, signaling product momentum but with limited direct financial/market impact from the announcement alone.
Analysis
The market should treat this as a signal of category maturity, not just product breadth. When a leader pushes into adjacent chores, it usually means the core floorcare franchise is becoming harder to grow without more SKU sprawl, which often lifts top line but compresses gross margin via higher channel incentives, warranty risk, and heavier marketing. The better read is that the company is trying to convert brand strength into a broader household automation platform before competitors lock up shelf space.
For incumbents, the pressure is asymmetric: smaller pure-plays with weaker balance sheets are most exposed to price competition and feature inflation, while diversified brands can absorb share loss with better distribution and bundled offerings. Pool and lawn robotics are also slower monetization curves than indoor vacs; adoption is seasonal, installation-sensitive, and more dependent on retailer education, so the revenue impact should lag the PR cycle by 1-3 quarters. If sell-through data disappoints, this looks more like margin dilution than TAM expansion.
Contrarian view: consensus may be overrating the strategic significance of “ecosystem” expansion. The economics of consumer robotics are usually driven by consumables, replacement cycles, and software retention, not by launching more hardware categories; adding adjacent devices can actually increase complexity without improving lifetime value. The key falsifier is not the launch cadence but gross margin and inventory turns over the next two earnings prints—if those deteriorate, the market should discount the brand story.
Catalyst-wise, the immediate move is likely negligible, but over 1-3 months we should watch retailer placement, promo intensity, and any evidence of channel substitution against incumbent floorcare names. Over 6-18 months, the real question is whether the company can turn this into recurring consumables revenue; if not, the multiple should migrate toward a hardware brand, not a platform.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No direct trade in the first 1-2 weeks; treat this as a watch item until sell-through or pre-order data confirms demand. Falsifier: if launch commentary translates into materially better margin guidance on the next print, the skepticism is wrong.
- Pair trade for 1-3 months: long SN / short IRBT. Thesis: the category leader’s expansion raises competitive intensity, but SharkNinja’s broader distribution and product mix give it better ability to absorb pricing pressure; IRBT remains the cleaner short if robotics price competition intensifies.
- If you want a tactical short on the weakest link, use IRBT on rallies into any retail excitement, with a 2-quarter horizon. Risk/reward is favorable only if inventory and promo pressure stay elevated; cover if IRBT posts sequential gross margin expansion or materially better unit sell-through.
- Set an alert on consumer robotics channel checks and retailer shelf data over the next 30-60 days. A miss there would support a short basket in hardware-heavy consumer names; a beat would argue the category is still underpenetrated.
- Avoid chasing the broader consumer discretionary complex on this headline alone. The trade is idiosyncratic share shift, not a sector-wide re-rating unless there is evidence that ecosystem expansion is lifting repeat purchase rates.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance