
Morpho dévoile son imprimante UV de bureau à l'IFA 2026 avec une démonstration de création en direct en temps réel
Source: PR Newswire
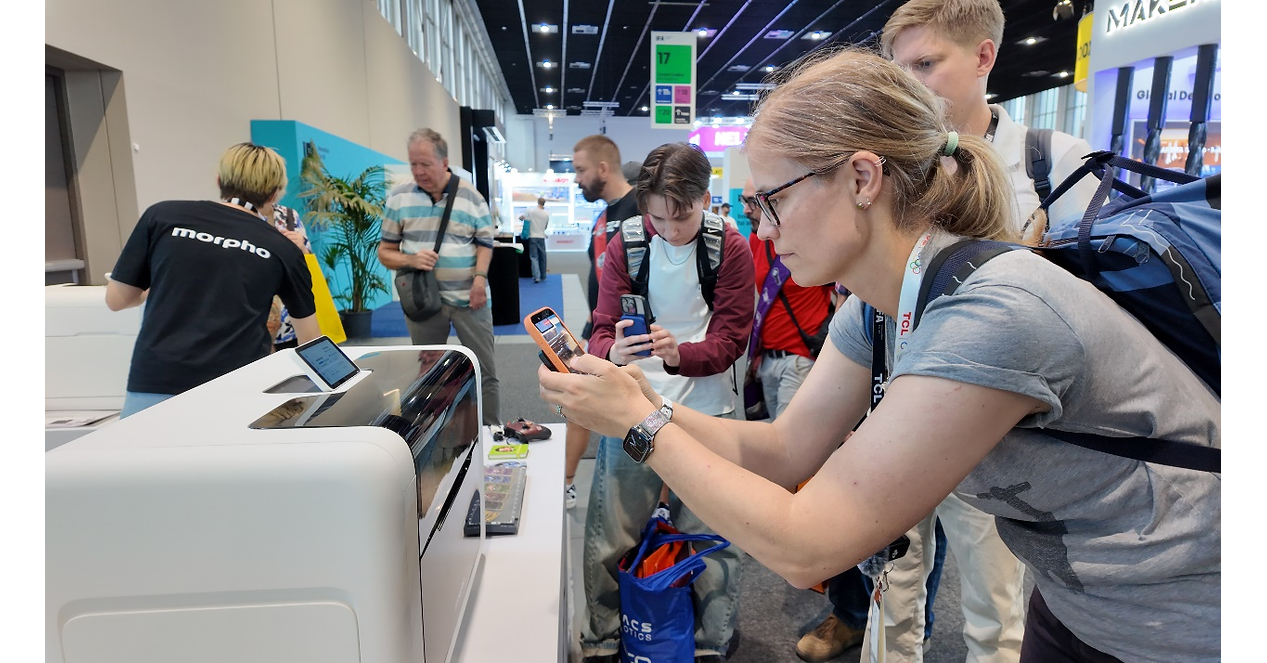
Morpho unveiled its first desktop UV printer at IFA 2026, featuring industrial-grade textured printing, G7 Master ColorSpace certification and carriage speeds of up to 600 mm/s. Its Kickstarter campaign surpassed $10 million from more than 2,800 backers ahead of the event, signaling strong early demand. The compact moving-gantry printer targets creators, educators, makers and small businesses with printing across wood, glass, leather and metal.
Analysis
The relevant signal is not near-term disruption of listed printing incumbents; it is validation that desktop UV printing is moving from a specialist-capex purchase toward a prosumer workflow category. If the product can reduce setup failures and substrate handling, it expands the addressable market among Etsy-scale sellers, schools, and small-format customization shops rather than merely displacing existing industrial UV installations. That would pressure entry-level product pricing and dealer margins for Mimaki (6638 JP) and Epson (6724 JP) over 6-18 months, while expanding recurring demand for UV inks, coatings, replacement heads, and software support.
Crowdfunded hardware demand should be discounted heavily until shipment quality is independently established. The principal economic risk is working capital: deposits fund initial production, but warranty claims, yield losses, certification delays, and global service infrastructure can consume cash faster than unit gross margins emerge. The key 1-3 month catalyst is evidence of production-unit delivery and third-party reviews; the key falsifier is rising delivery slippage, refund requests, or reports that print quality degrades outside controlled demonstrations.
Consensus may overstate the threat to established vendors because UV printing remains a service-intensive category. A low upfront hardware price can be offset by consumables, calibration, safety compliance, and downtime; incumbents retain advantages in channel coverage and installed-base service. The more credible second-order opportunity is in consumables suppliers—particularly DIC (4631 JP) and Fujifilm (4901 JP)—if desktop adoption creates a larger installed base, although the near-term revenue effect is too small to underwrite a standalone position.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No immediate directional trade: treat this as a private-market/product-category watch item rather than a catalyst for HPQ, SSYS, 6638 JP, or 6724 JP; the stated commercial signal is insufficient to alter listed-company estimates.
- Set a 1-3 month alert for verified volume shipments, retail pricing, ink cost per square meter, warranty terms, and independent throughput testing. A material desktop-UV price/performance gap versus Mimaki or Epson entry products would justify revisiting a relative short in 6638 JP versus long 4631 JP or 4901 JP.
- Monitor DIC (4631 JP) and Fujifilm (4901 JP) for consumables commentary in the next two earnings cycles; initiate only if management identifies incremental small-format UV ink demand or margin-accretive specialty-ink mix. Absent disclosed demand, expected financial impact is immaterial.
- Avoid shorting established printing OEMs solely on this launch. The thesis is falsified in the other direction if retail channels show sustained sell-through and competitors respond with lower-priced enclosed UV platforms, which would make entry-level hardware margin pressure more immediate.
More News
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Defense giant Saab sees orders triple after Gripen fighter jet deal with Ukraine
- Volvo Cars shares plunge 25% amid China sales slump and fresh job cuts
- Mark Zuckerberg owns 13% of Meta but controls 61% of its votes. California’s wealth tax would bill him on the 13%
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- AI Software for Buy-Side Teams: Build the Research Stack