
Agthia meldet Umsatzwachstum trotz herausforderndem Kostenumfeld
Source: PR Newswire
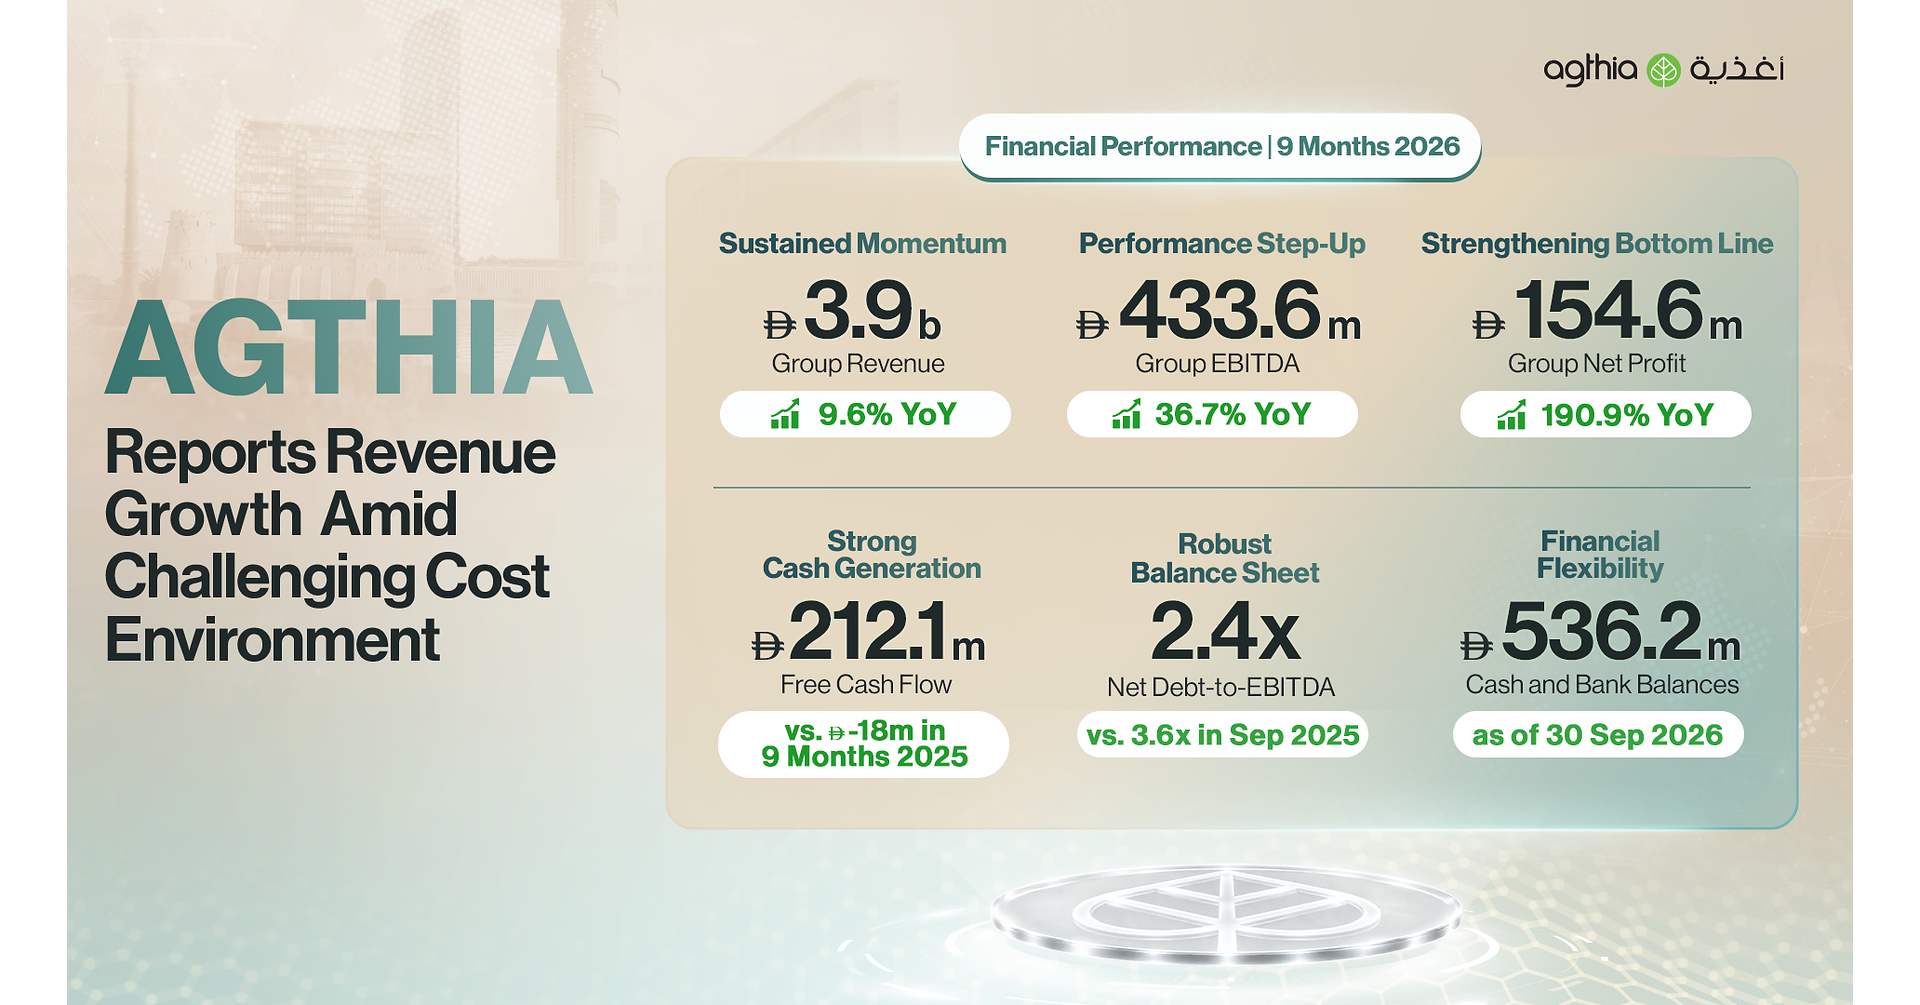
Agthia’s Q3 2026 revenue rose 14.4% year over year to AED 1.3 billion, including AED 104.7 million in one-off sales; excluding those sales, growth was 5.2%. EBITDA increased 39.0% to AED 123.1 million and net profit reached AED 33.2 million versus AED 4.1 million a year earlier, which included Snacking impairment charges. For the first nine months, revenue gained 9.6% to AED 3.9 billion and free cash flow was AED 212.1 million, but higher sourcing, PET, freight and distribution costs pressured some segment margins.
Analysis
The earnings quality is better than the headline growth rate implies in some areas, but less clean in others: one-off revenue inflates reported sales growth, while the prior-year impairment makes the profit comparison unusually easy. The more useful signal is whether operating leverage persists on a core-sales base. That is not yet established: procurement and distribution costs are pressuring Water & Food and sharply squeezing Agri-Business, so continued growth could fail to translate into group margin expansion if input costs remain elevated.
The balance-sheet and cash-generation improvement reduces downside financing risk and gives management more room to absorb temporary cost shocks. Conversely, the Saudi protein-capacity ramp and Abu Auf’s expansion add execution and working-capital demands before their returns are independently visible. Regional logistics disruption is also a two-sided risk: it may support demand for resilient local suppliers, but can simultaneously raise delivery costs and constrain exports.
Near term, the release supports a positive but not unambiguous reaction; the one-off and comparison effects argue against chasing reported growth. Over 1–3 months, monitor core revenue, segment EBITDA/margins, and cash conversion. Over 6–18 months, the thesis depends on cost recovery and whether new capacity and retail expansion earn returns without renewed leverage. Missing valuation, share-price reaction, and consensus data prevent a defensible target or assessment of whether the move is already priced in.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Key Decisions for Investors
- No immediate directional trade on the release alone. Treat Agthia as a conditional long on weakness only if subsequent reporting confirms core-sales growth alongside stable or improving margins; avoid paying for the headline growth rate without that confirmation.
- Set an alert for PET, freight, and feed procurement trends and for segment-level margin disclosure. Persistent input-cost pressure without pricing or mix offset would undermine the earnings-quality thesis, particularly in Agri-Business.
- Falsification checks: a renewed decline in group or segment EBITDA margins, reversal in free-cash-flow conversion, or net leverage turning higher would weaken the balance-sheet cushion and justify reducing exposure.
- Before sizing a position, verify the post-announcement share-price move, valuation versus regional food peers, and management’s quantified outlook for one-off sales, input costs, and returns on Saudi capacity and store expansion.
More News
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- Iran says tankers struck in Hormuz amid fears of new US attack
- The Iran war has cost U.S. households nearly $2,000 each. New strikes could keep the bill climbing
- Qualcomm slides 9% after earnings, leading post-election chip stock sell-off
- Costco is taking aim at its May record high — how it got here and where's it going