
Ballard schließt Übernahme von GeoPura ab und wird damit zu einem Anbieter integrierter Wasserstoff-Energielösungen
Source: PR Newswire
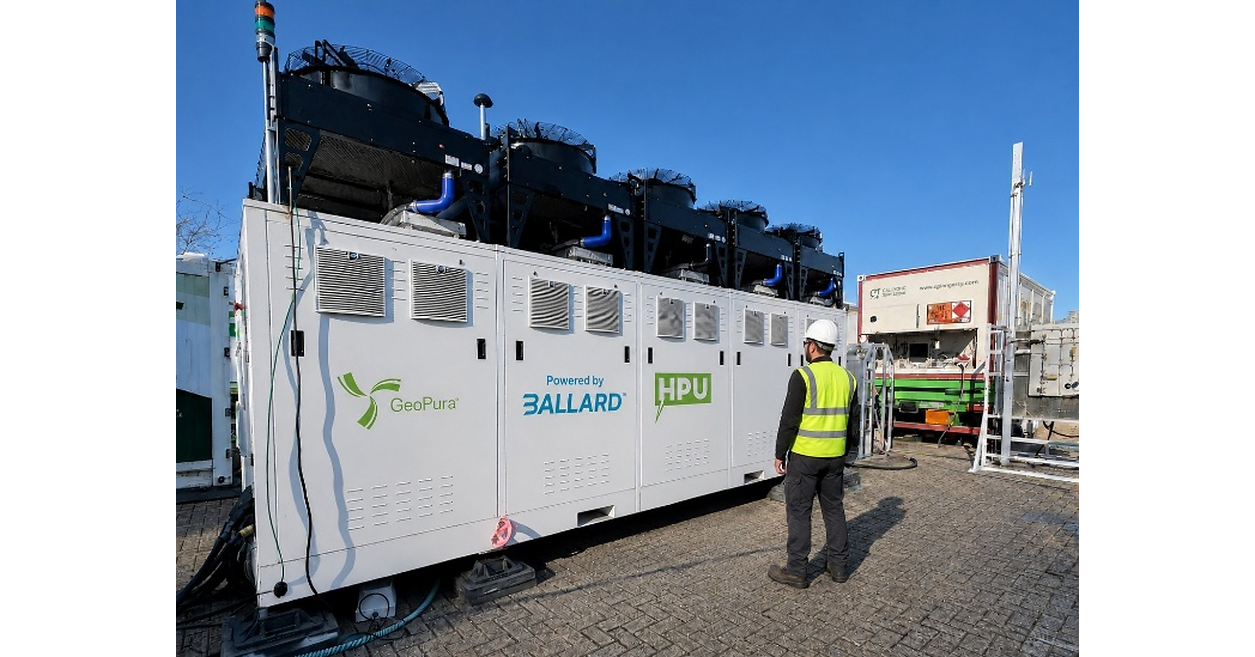
Ballard Power Systems has completed its acquisition of GeoPura, creating an integrated “Energy-as-a-Service” hydrogen-energy provider. The deal includes upfront consideration of £275.0m (£82.5m cash plus 49,584,212 new Ballard shares), with up to an additional £27.5m contingent on post-close financial milestones. On a pro-forma basis, former GeoPura shareholders will own ~14.1% of Ballard’s outstanding shares, a move that should strengthen Ballard’s Europe reach and expand growth opportunities in North America.
Analysis
Strategically, this is less about a near-term earnings pop than about BLDP trying to move up the value chain from a component supplier to a service-layer platform with stickier revenue. If the integration works, the market could eventually assign a higher multiple to recurring EaaS cash flows than to one-off module sales, but that rerating only happens if utilization, contract length, and maintenance economics prove durable. In the next 1-3 months, the key question is whether management can show evidence that the acquired customer base is financeable without structurally higher dilution or leverage.
The hidden risk is that BLDP may be buying revenue quality with its own equity. A stock-heavy deal that adds operating assets and fuel logistics increases working-capital drag and execution complexity, which is a bad trade if hydrogen utilization is still lumpy. That makes this more akin to a balance-sheet and project-finance story than a pure technology story; any disappointment on fleet utilization, hydrogen input costs, or contract renewals would compress the multiple quickly.
Relative winners are likely diesel generator and temporary power incumbents that remain the low-friction fallback for construction/events/backup power, because BLDP still has to prove it can win on total cost of ownership, not just emissions. The second-order beneficiaries may be electrolyzer and hydrogen-logistics suppliers if BLDP scales its captive fuel chain, but that also raises exposure to electricity prices and permitting. Contrarian view: the market may overrate the strategic elegance and underrate the dilution and capital intensity; unless disclosed backlog and gross margin improve, this could be a narrative upgrade with limited fundamental impact over 6-18 months.
The tradeable catalyst is the first post-close disclosure on pipeline conversion, not the announcement itself. If the stock rallies on headline M&A enthusiasm without a clear uplift in contracted revenue or margin, that move is vulnerable to fade once investors model the cash burn and share count increase.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- BLDP: do not chase the first-day move; wait 2-3 sessions for volume to normalize, then fade strength if the stock holds a headline-driven gap-up without upgraded FY guidance or quantified synergy targets.
- BLDP downside hedge: buy 1-3 month put spreads into any post-announcement squeeze if the market assigns a premium for 'integrated hydrogen' before management discloses unit economics; thesis breaks if backlog conversion or gross margin expands in the next earnings release.
- Relative-value watch: long BLDP / short PLUG only if management shows the GeoPura model materially improves recurring revenue mix and customer stickiness; otherwise PLUG remains the cleaner call on hydrogen scale while BLDP absorbs integration risk.
- Earnings catalyst alert: if BLDP does not raise revenue quality metrics, gross margin, or operating cash flow at the next print, treat the deal as dilution first and strategy second; revisit shorts on any 10%+ rally into that release.
- Sector hedge: for investors wanting hydrogen exposure, prefer a basket or pair against BLDP rather than outright longs until there is evidence that EaaS economics can scale without persistent equity funding.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Saudi Arabia says 1 dead, 11 injured in latest attack on Riyadh airport
- Why is LG Innotek stock plunging today?
- RBI Tightens Rupee Defense as Pricey Crude, Foreign Outflows Bite: USD/INR
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?