
Parks Associates: 275 SVOD Services, 141 AVOD, and 60 FAST Platforms Compete in the US Streaming Market
Source: PR Newswire
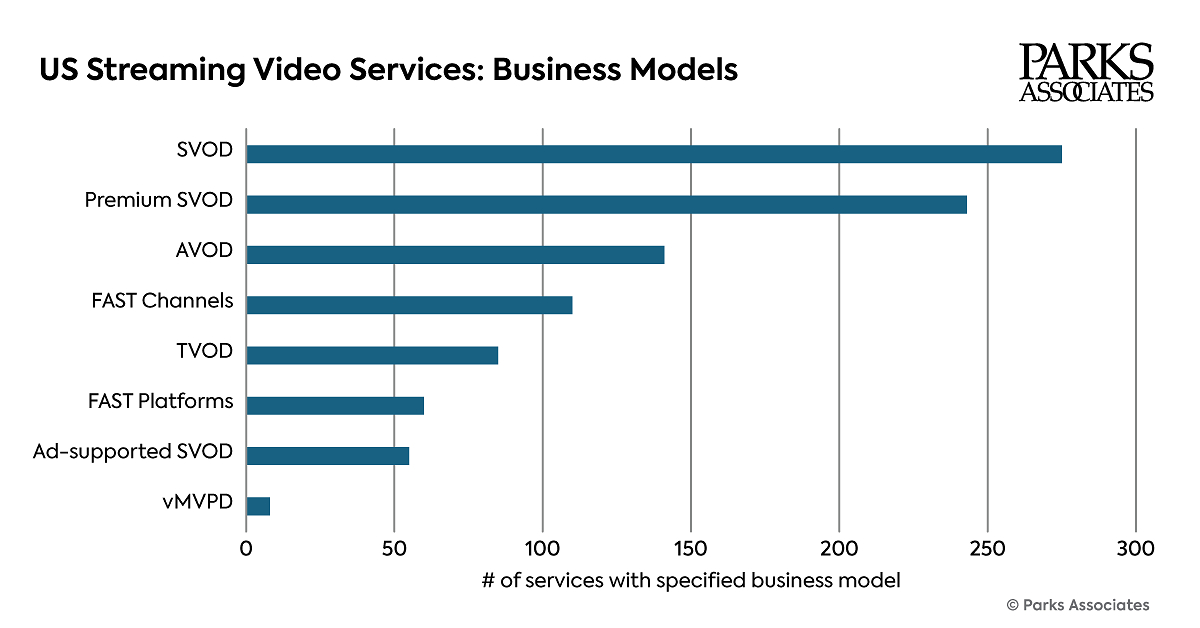
Parks Associates counts 275 U.S. SVOD services, 141 AVOD services, and 60 FAST platforms, reflecting a streaming market with increasingly varied monetization models. Its tracker also identifies 110 FAST channels; categories may overlap as providers combine subscription, advertising, and free offerings. Industry executives will discuss these models at the Future of Video conference on November 17–18, 2026, in Marina del Rey, California.
Analysis
The headline counts are a weak proxy for investable demand: service categories overlap, and a larger provider universe does not establish growth in viewing hours, ad dollars, or paid retention. The more useful implication is that monetization is shifting toward hybrid models while audience attention remains finite. That favors platforms with scaled distribution, first-party viewing data, and ad-sales infrastructure—such as Roku, Amazon, and YouTube—over small standalone FAST operators, which may face weaker fill rates and pricing as inventory proliferates. Content owners could gain incremental licensing outlets, but more outlets also fragment audiences and may dilute the scarcity value of individual libraries.
Near term, this is industry color, not a catalyst; the conference itself is unlikely to change earnings estimates. Over 1–3 months, watch reported connected-TV ad pricing, fill rates, and viewing-hour trends for evidence that inventory growth is being absorbed. Over 6–18 months, the key question is whether hybrid offerings improve retention and lifetime value enough to offset content, distribution, and ad-tech costs. A contrarian risk to the bullish “more models mean more monetization” narrative is that abundance shifts negotiating leverage to scaled aggregators and advertisers, compressing economics for niche services. Do not infer market share or revenue growth from the service counts alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No event-driven trade is warranted from this announcement alone; treat it as a watch item rather than a change to sector exposure.
- For a relative-value watchlist, compare scaled CTV distribution businesses such as Roku and Amazon with smaller standalone streaming operators. Consider a pair only if valuation and earnings data support the view that scale is translating into stronger ad monetization; the article supplies neither.
- Track quarterly connected-TV ad pricing, fill rates, viewing hours, and ad-tier retention. Improving monetization alongside stable engagement would challenge the oversupply thesis; falling pricing or engagement despite rising inventory would strengthen it.
- Reassess the thesis if major platforms disclose material ad-revenue acceleration without deterioration in retention, or if content owners demonstrate durable licensing-price gains. Verify those metrics independently rather than relying on conference claims.
More News
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell-Lumentum Deal Puts Optical Networking at the Center of the AI Boom
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- 5 things to watch on Election Day as Democrats push for control of Congress
- AI Inference Startup Fal Raises Capital at $16 Billion Valuation